
Industry Portal
Related News
- 00
0000-00
How to Specify Low-Pressure Casting Parts for Leak-Tight Automotive Housings - 00
0000-00
How to Specify an Electric Sunroof for Passenger Cars: Key Design and Safety Factors - 00
0000-00
North American Vehicle Aesthetics: Trends Shaping Exterior Design and Materials - 00
0000-00
ASPICE for Smart Optical Systems: Evidence Needed for Automotive Development - 00
0000-00
How to Select NVH Control Materials for Automotive Panels and Powertrain Systems
Tags
Sumitomo Electric Raises Epoxy Resin Prices 10–20% Effective June 1, 2026: Laser Headlight Packaging Costs Under Pressure
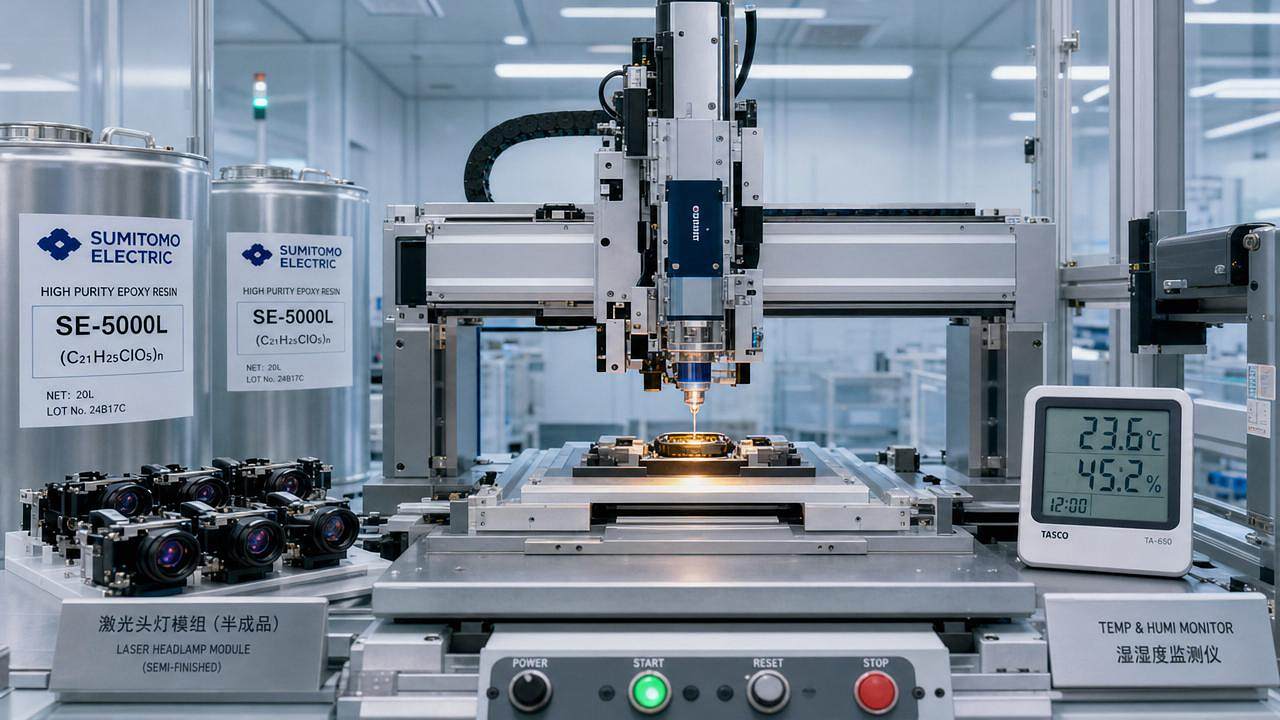
Effective June 1, 2026, Sumitomo Electric Industries, Ltd. announced a 10–20% price increase for semiconductor-grade epoxy resins—key materials used in optical module encapsulation for automotive laser headlights (Laser Headlights). The adjustment stems from tightening supply-demand balance driven by rapid expansion of advanced packaging capacity and rising upstream costs for phenol and bisphenol A.
Confirmed Price Adjustment Announcement
On June 1, 2026, Sumitomo Electric officially implemented a 10–20% price hike for epoxy resins designated for semiconductor packaging applications. These resins are widely deployed in the optical encapsulation of automotive-grade laser headlight modules. The increase directly affects Chinese laser light source module manufacturers, influencing both quotation terms and delivery lead times. Customers with existing orders for customized laser headlight systems are advised to immediately verify and lock in bill-of-materials (BOM) cost clauses.
Supply Chain Impact Across Stakeholder Roles
Direct Trading Enterprises
Trading firms handling import/export of epoxy resins face revised landed cost structures and potential margin compression. Since Sumitomo Electric is a primary supplier, price adjustments may trigger cascading renegotiations with downstream buyers—and require updated customs valuation documentation and commercial invoices reflecting the new pricing tier.
Raw Material Procurement Entities
Procurement departments at electronics and automotive component manufacturers must reassess material cost forecasts and vendor allocation strategies. With phenol and bisphenol A prices rising upstream, alternative sourcing or long-term contracts may now carry higher strategic weight—even for non-Sumitomo resin grades.
Contract Manufacturing & Assembly Firms
EMS and ODM providers integrating laser headlight modules into vehicle subsystems will experience cost pass-through pressure. This impacts quoting accuracy, profitability modeling per project, and may necessitate technical validation of alternative encapsulants if substitution is pursued.
Supply Chain Services Providers
Logistics, customs brokerage, and quality assurance service providers should anticipate increased demand for cost-justification documentation, tariff classification support (e.g., HS code 3907.30 for epoxy resins), and compliance verification related to automotive-grade material traceability (e.g., IATF 16949 alignment).
Key Actions for Affected Companies
Review and Lock BOM Cost Clauses Immediately
Overseas customers with active purchase orders for custom laser headlight assemblies must urgently confirm whether their contracts include fixed-price BOM provisions effective before June 1, 2026—or if cost escalation clauses apply. Delayed action risks unplanned cost absorption post-implementation.
Evaluate Encapsulant Qualification Pathways
Manufacturers considering alternative epoxy resins must assess requalification timelines under AEC-Q200 or ISO/TS 16949 requirements. Even minor formulation changes may trigger optical stability, thermal cycling, and humidity resistance retesting—adding weeks to production ramp-up.
Assess Lead Time Implications Across Tiered Suppliers
Chinese laser module makers may extend quoted lead times due to procurement delays, inventory buffering, or secondary qualification cycles. Buyers should proactively request updated delivery commitments and monitor order book visibility from Tier-2 and Tier-3 encapsulant distributors.
Industry Perspective: Beyond Short-Term Cost Pressure
Analysis shows this price move reflects deeper structural shifts—not just cyclical input cost inflation. The surge in advanced packaging demand is accelerating consolidation among high-purity epoxy resin suppliers, raising barriers to entry for new vendors seeking automotive qualification. From an industry perspective, the tightening of material availability underscores growing interdependence between semiconductor packaging infrastructure and automotive lighting innovation. What deserves closer attention is how quickly second-source qualification pathways can scale—especially given the extended validation timelines inherent in laser headlight optical performance and safety standards.
Strategic Implication for Automotive Electronics Sourcing
This adjustment signals a broader recalibration of cost assumptions in next-generation automotive lighting supply chains. It is more appropriate to understand this as a marker of maturing technology adoption—where raw material economics begin to constrain system-level scalability. While not a regulatory mandate, it functions as a de facto cost gate for laser headlight commercialization outside premium vehicle segments. Rational planning requires treating such material-level volatility as a permanent feature—not an exception—in procurement and product lifecycle costing.
Source Attribution and Monitoring Guidance
This article was generated based solely on the user-provided title, event date (2026-06-01), and summary. Specific official source links were not provided in the input and should be verified continuously. Stakeholders are advised to monitor upcoming updates from Sumitomo Electric’s global procurement portal, industry bulletins from the Japan Electronics and Information Technology Industries Association (JEITA), and technical advisories issued by international automotive standards bodies—including those related to encapsulant material specifications under ISO 16750 and UNECE Regulation 112. Further clarity on implementation scope, regional applicability, and customer communication protocols remains subject to ongoing observation.