
Industry Portal
Related News
- 00
0000-00
Wheel Lightweighting in Europe: How EV Regulations Are Reshaping Wheel Sourcing - 00
0000-00
How to Specify Low-Pressure Casting Parts for Leak-Tight Automotive Housings - 00
0000-00
How to Specify an Electric Sunroof for Passenger Cars: Key Design and Safety Factors - 00
0000-00
North American Vehicle Aesthetics: Trends Shaping Exterior Design and Materials - 00
0000-00
ASPICE for Smart Optical Systems: Evidence Needed for Automotive Development
What is driving the NEV industry beyond policy support?
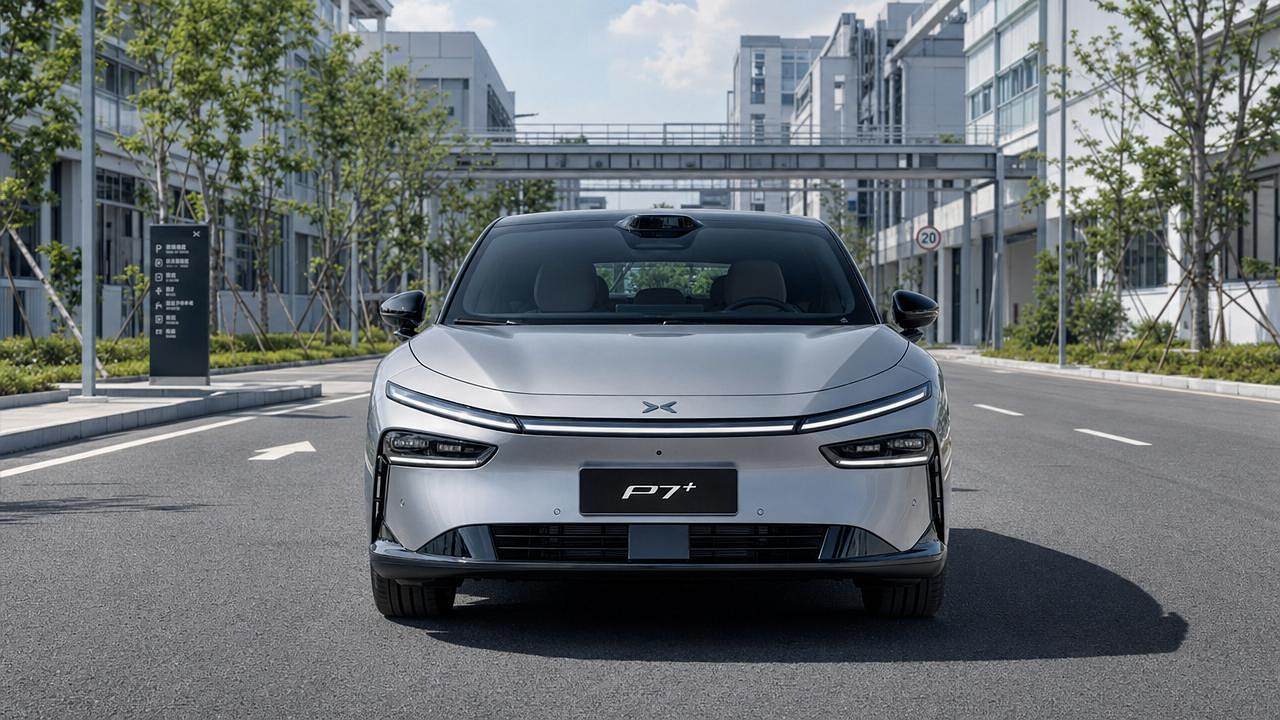
Beyond policy incentives, the NEV industry is being propelled by a deeper mix of technology, cost efficiency, safety expectations, and consumer demand for smarter, lighter, and more energy-efficient vehicles. For business evaluators, understanding how innovations in wheels, tires, lighting, sensing, and exterior systems reshape vehicle performance and market value is now essential to identifying sustainable growth opportunities.
The short answer is clear: the NEV industry is no longer moving mainly because governments want it to. It is moving because the product is improving, the economics are changing, and the supply chain is becoming more capable.
For business evaluators, this matters because policy support can fade, vary by region, or become more targeted. What supports long-term value is different: lower total cost of ownership, better user experience, stronger safety performance, and scalable component innovation.
That is why the most important question is not whether subsidies remain generous. The better question is which technical and commercial drivers now make NEV growth more self-sustaining across passenger vehicles, fleets, and premium mobility segments.
What are users really asking when they search what is driving the NEV industry beyond policy support?
In practical terms, searchers want to know whether the NEV industry has entered a healthier stage of growth. They are asking if demand can remain strong even when incentives weaken or market competition intensifies.
They also want evidence. Broad claims about electrification are not enough. Decision-makers need to see which technologies are improving margins, which components increase vehicle value, and which trends are durable rather than temporary.
For commercial readers, especially business evaluators, the search intent is tied to investment logic. They need to understand what actually drives revenue resilience, supplier opportunity, product differentiation, and future competitiveness in the NEV industry.
Why business evaluators should look beyond batteries and policy headlines
Most market commentary on the NEV industry focuses on battery cost, charging infrastructure, and regulation. Those factors remain important, but they no longer explain the full picture of competitive advantage or commercial upside.
Vehicle performance and customer acceptance are increasingly shaped by systems outside the battery pack. Exterior lightweighting, tire efficiency, intelligent lighting, sensor-linked body functions, and aerodynamic optimization now influence both range and perceived quality.
These systems are especially relevant because they affect multiple business outcomes at once. They can improve energy efficiency, reduce warranty risk, support premium pricing, strengthen compliance, and help brands differentiate in crowded markets.
For an intelligence platform like AEVS, this is where a more realistic reading of the NEV industry begins. Growth is being reinforced by the convergence of engineering detail and business value, not by one policy lever alone.
Technology progress is making NEVs commercially stronger, not just politically favored
The first major force behind the NEV industry is continuous technology improvement. Vehicles are becoming more refined in ways consumers can feel and operators can measure, from lower drag and quieter cabins to smarter visibility and safer driving assistance.
Lightweight exterior systems are a good example. Aluminum alloy wheels, optimized aerodynamic surfaces, and more efficient body components directly support range, handling stability, and thermal balance. These gains matter because they improve real-world performance without relying on larger batteries alone.
At the same time, high-performance tires are becoming a strategic category in the NEV industry. Electric vehicles impose unique demands because of instant torque, higher vehicle mass, and stricter expectations for noise control and rolling resistance.
A tire that reduces rolling losses while maintaining wet grip and durability does more than improve comfort. It affects range confidence, energy efficiency, replacement cycles, and safety perception, all of which influence vehicle value and aftermarket revenue.
LED headlight assemblies also show how the technology story has evolved. Smart lighting is no longer only about illumination. Matrix systems, adaptive beams, and projection functions improve visibility, energy use, and interaction with drivers and road environments.
Sensor-driven switches and body perception modules add another layer of value. They support automatic wipers, smart headlamp activation, blind-spot functionality, and better weather response. In the NEV industry, that means a more intelligent and integrated vehicle experience.
Cost efficiency is becoming a stronger demand driver than subsidy dependence
A second major driver is improving cost logic. Even where purchase incentives decline, NEVs are becoming more attractive because operating economics are often superior, especially in urban use, ride-hailing, logistics, and high-mileage ownership patterns.
Business evaluators should not look only at sticker price. The more relevant framework is total cost of ownership. Energy use, maintenance frequency, brake wear, tire life, software-enabled upgrades, and residual value all shape whether an NEV is commercially compelling.
Component innovation contributes directly to this equation. Low-drag wheels, low-rolling-resistance tires, and efficient lighting systems reduce energy waste. Smarter sensing systems can also lower accident exposure or improve preventive response in daily driving conditions.
As manufacturing scales, these component-level gains become more meaningful. What once looked like a premium feature can become standard equipment, spreading efficiency benefits across larger vehicle volumes and strengthening the business case for the NEV industry.
This matters especially in price-competitive markets. When brands cannot rely on subsidy-led demand, they must win through measurable user value. Better energy economy, lower cabin noise, stronger visual safety, and more durable components become competitive tools.
Consumers are buying a better mobility experience, not just an electric drivetrain
A third force behind the NEV industry is changing customer expectation. Buyers increasingly evaluate electric vehicles as complete products. They compare refinement, comfort, intelligence, and visual appeal, not only acceleration figures or battery range claims.
This shift benefits suppliers and manufacturers that understand vehicle exterior and perception systems. A panoramic or electrochromic sunroof can reshape cabin openness. Quiet tires can change how premium a vehicle feels. Smart headlights improve confidence during night driving.
These are not cosmetic details. In the NEV industry, user satisfaction is strongly connected to integrated design quality. Since electric platforms are often quieter by nature, drivers notice road noise, lighting performance, and body-system responsiveness more clearly.
That creates space for value migration. Categories once treated as secondary can now influence purchase decisions, customer reviews, and brand loyalty. For business evaluators, this means non-powertrain systems may carry more strategic importance than older valuation models assume.
In premium and upper-mid segments, exterior aesthetics and dynamic perception are becoming part of the competitive moat. Buyers want vehicles that look efficient, feel intelligent, and deliver sensory refinement consistent with next-generation mobility expectations.
Safety and compliance are accelerating innovation across the NEV industry
Another reason the NEV industry keeps advancing is the rising importance of safety and regulatory readiness. As electric vehicles scale globally, manufacturers must meet diverse standards while maintaining efficiency and design flexibility.
Lighting, sensors, tires, and wheel systems all sit close to this challenge. ECE and DOT compliance, anti-glare performance, road-contact reliability, and environmental adaptation are not side issues. They are foundational to market entry and brand trust.
For example, advanced headlight systems must now balance energy use, thermal management, optical precision, and legal requirements. That raises the strategic value of suppliers with strong engineering depth and validation capability.
The same is true for tires and wheels. In the NEV industry, heavy battery packs and instant torque place unusual stress on contact systems. Products that can preserve grip, noise performance, and structural integrity under these conditions become highly valuable.
Sensor-linked exterior functions also support safety expectations that consumers now assume as normal. Automatic activation, visibility assistance, and situational response are part of the modern driving baseline, especially in higher-spec NEV platforms.
Supply chain maturity is turning innovation into scalable business opportunity
The NEV industry grows faster when innovation can be manufactured reliably at scale. That is why supply chain maturity is one of the most important non-policy drivers, even if it receives less public attention than demand or regulation.
Suppliers that can deliver repeatable quality in forged wheels, advanced tire compounds, smart optical modules, and sensor assemblies enable automakers to launch differentiated products with less execution risk. That reduces delays and supports margin protection.
Raw material visibility also matters. Aluminum and rubber cost fluctuations can quickly affect profitability, sourcing strategy, and product positioning. Business evaluators should track whether suppliers have the technical and commercial discipline to adapt without eroding performance.
This is where strategic intelligence becomes valuable. Understanding brake airflow simulation in wheel design, self-sealing tire chemistry, or thermal models in smart lighting is not just technical curiosity. It reveals whether a company has defendable expertise.
In a crowded NEV industry, scale without specialization can become fragile. Suppliers and platforms with deep know-how in exterior and vision systems are better positioned to maintain relevance as product requirements become more demanding.
Where the strongest value pools are emerging for evaluators
For commercial assessment, not every part of the NEV industry offers equal opportunity. The strongest value pools are often found where efficiency, safety, intelligence, and premiumization overlap in one system or component category.
Aluminum alloy wheels are a good example because they affect lightweighting, aerodynamics, brake cooling, and aesthetics at the same time. That combination creates both OEM relevance and a profitable aftermarket story, especially in custom and performance segments.
High-performance NEV tires also present attractive economics. They serve immediate OEM needs while opening replacement demand as the installed base grows. Because EV-specific requirements differ from conventional vehicles, technical credibility can support pricing power.
LED headlight assemblies and smart optical systems offer similar upside where regulation, branding, and user interaction converge. As vehicles become more software-defined, lighting moves closer to being an active communication and safety platform.
Sensor switches and body perception modules are smaller in form factor but strategically important. They contribute to intelligent automation, energy-efficient operation, and user convenience, making them highly relevant in both volume and premium NEV programs.
How to evaluate whether NEV growth is sustainable in a specific market or supplier segment
Business evaluators need a framework, not just trend awareness. The first test is whether demand is supported by user economics and product quality rather than by temporary incentives alone. If yes, growth is more likely to persist.
The second test is whether component innovation solves real EV-specific problems. Look for improvements in rolling resistance, aerodynamic drag, thermal efficiency, structural strength, NVH control, and optical intelligence. These indicate practical value creation.
The third test is supply chain readiness. Can suppliers scale globally, manage compliance, absorb material volatility, and maintain product consistency? In the NEV industry, execution quality often separates market winners from promising but fragile players.
The fourth test is margin structure. Products with measurable performance benefits and high validation barriers often defend better margins than commoditized parts. This is especially true in categories tied to safety, efficiency, and premium user perception.
Finally, assess aftermarket potential. As the NEV installed base expands, replacement cycles for tires, wheels, lighting modules, and related systems can create long-tail revenue beyond original vehicle production.
The strategic takeaway for the NEV industry
The NEV industry is being driven beyond policy support by a more durable set of forces: better technology, stronger operating economics, rising safety expectations, more mature supply chains, and customer demand for smarter and more refined vehicles.
For business evaluators, this means the center of analysis should move from headline incentives to structural competitiveness. The key question is no longer whether electric mobility is encouraged. It is whether specific products and suppliers create recurring value.
That is why exterior and vision systems deserve closer attention. Wheels, tires, lighting, sunroof systems, and sensor switches are no longer peripheral categories. They are part of how NEVs improve efficiency, safety, comfort, and brand distinction.
In other words, the NEV industry is maturing from a policy-supported transition into a performance-driven market. The companies most likely to win are those that can translate engineering depth into real commercial advantage.
For readers evaluating growth opportunities, that is the clearest conclusion: the next phase of the NEV industry will be shaped less by incentives alone and more by the ability to deliver lighter, smarter, safer, and more energy-efficient vehicles at scale.