
Industry Portal
Related News
- 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects - 00
0000-00
Automatic Wipers for Buses: 7 Selection Criteria for Fleet Procurement - 00
0000-00
How Smart Optical Perception Prevents Collisions in Low-Light Driving Conditions - 00
0000-00
Private Label Tire Export: Evaluating Suppliers, Compliance, and Landed Cost - 00
0000-00
DOT-Compliant Truck Lighting: A Practical Guide to FMVSS 108 Requirements
What Is the NEV Industry? Market Structure, Supply Chain Roles, and Growth Drivers
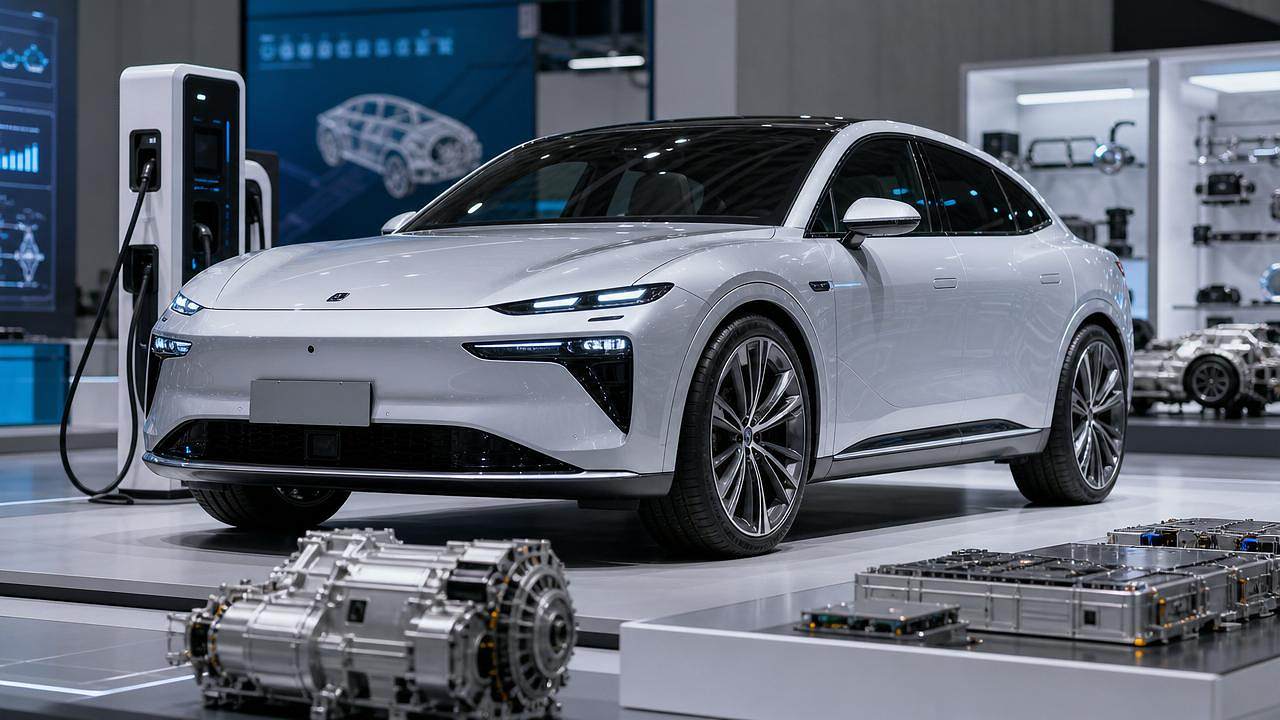
The NEV industry sits at the intersection of electrification, regulation, materials science, and intelligent vehicle design. It matters because value is no longer created only in batteries and powertrains. Exterior lightweight parts, tires, wheels, lighting, and sensor-based perception now shape range, safety, compliance, and user experience at the same time.
Understanding what the NEV industry really includes
At a basic level, the NEV industry covers vehicles powered partly or fully by non-traditional propulsion systems. That includes battery electric vehicles, plug-in hybrids, and fuel cell vehicles.
In practice, the NEV industry is much broader than vehicle assembly. It includes upstream raw materials, components, software, testing, charging ecosystems, aftermarket services, and compliance systems.
This broader view matters because performance is built across systems. A battery may define energy storage, but aerodynamic drag, rolling resistance, thermal behavior, and sensing accuracy also influence real-world efficiency.
That is why sectors once treated as supporting categories now carry strategic weight. In the NEV industry, exterior and vision systems increasingly affect both technical differentiation and commercial positioning.
Why the market is drawing so much attention
The global shift toward low-emission mobility is the obvious driver, but it is not the only one. Cost pressure, digital features, safety expectations, and regional policy also push the market forward.
More importantly, competition inside the NEV industry is moving beyond headline range numbers. Buyers and regulators now notice charging efficiency, cabin comfort, quietness, night visibility, and software-enabled perception.
This change has raised the profile of components that influence energy use indirectly. Lightweight sunroof systems, forged wheels, EV-focused tires, matrix LED headlamps, and body sensor switches all contribute measurable results.
For that reason, intelligence platforms such as AEVS are increasingly relevant. They help connect aerodynamics, optical algorithms, material costs, and global standards into a usable picture of market direction.
How the NEV industry market structure works
The market structure of the NEV industry can be understood as a layered ecosystem. Each layer creates value differently and faces different risks.
Upstream foundation
This layer includes metals, polymers, rubber compounds, optical materials, semiconductors, and specialty coatings. Aluminum and rubber prices, for example, directly affect wheel and tire economics.
Midstream component systems
This is where many competitive differences emerge. Suppliers design and manufacture assemblies that must balance weight, durability, energy efficiency, cost, and regulatory compliance.
In AEVS-covered categories, the core roles include electric sunroof systems, aluminum alloy wheels, high-performance tires, LED headlight assemblies, and auto sensor switches.
Vehicle integration and branding
OEMs turn subsystem performance into final product value. They decide trade-offs among drag reduction, styling, ride comfort, ADAS integration, thermal management, and price positioning.
Downstream services and aftermarket
The NEV industry does not end at vehicle delivery. Replacement tires, custom forged wheels, sensor maintenance, lighting upgrades, and compliance adaptation all create continuing revenue streams.
Where supply chain roles become strategic
The NEV industry rewards suppliers that solve several problems at once. A component is more valuable when it improves efficiency, helps meet safety rules, and strengthens the vehicle’s design identity.
Take aluminum alloy wheels. They are no longer only styling parts. In the NEV industry, wheel design affects unsprung mass, brake airflow, structural strength, and aerodynamic drag.
The same shift applies to tires. EVs create high torque instantly and often carry more weight. That changes the design logic for grip, wear, silence, and rolling resistance.
Lighting systems have also moved up the value chain. LED headlight assemblies now combine illumination, thermal control, compliance, and interactive projection functions.
Sensor switches play a quieter but equally important role. They link perception, automation, and body network decisions in functions such as blind-spot monitoring, automatic wipers, and smart headlamp activation.
Even electric sunroof systems fit the larger logic. In the NEV industry, cabin openness, solar load control, NVH performance, and weight management can all influence perceived product quality.
Growth drivers shaping the next phase
Several growth drivers are pushing the NEV industry into a more technically demanding stage. None of them works in isolation.
- Lightweighting pressure keeps rising because every kilogram affects range, handling, and energy consumption.
- Smart perception expands demand for better optics, sensors, and lighting architectures.
- Global regulation increases the need to track ECE, DOT, and other regional compliance requirements.
- Raw material volatility changes sourcing strategy and supplier risk evaluation.
- Premium aftermarket demand creates space for performance wheels, replacement tires, and advanced lighting upgrades.
- User expectations now include quietness, refined ride feel, visual identity, and digital interaction.
A useful way to read the NEV industry is to follow these drivers across connected systems. For example, lower drag can influence wheel geometry, tire compound strategy, and even airflow around lighting modules.
That systems view explains why AEVS positions intelligence as a stitching function. Market signals become more actionable when technical, commercial, and regulatory information are read together.
How to evaluate business relevance in real scenarios
A practical reading of the NEV industry starts with where value is created, protected, or lost. Not every innovation has the same impact across vehicle classes or regional markets.
For mass-market models, cost discipline and compliance timing may matter more than exotic materials. For premium models, intelligent lighting, forged wheels, and refined NVH solutions may justify stronger investment.
Regional conditions also reshape priorities. Climate, road quality, charging patterns, and traffic standards can change the ideal specification for tires, sensors, or optical systems.
This is where specialist intelligence becomes valuable. Thermal management models for smart headlights, CFD analysis of wheel airflow, and self-sealing tire chemistry are not isolated technical details. They point to competitive direction.
Useful evaluation questions
- Does the component improve range directly or indirectly?
- Is the performance gain durable under real operating conditions?
- Can the solution meet both engineering targets and regional standards?
- How exposed is the design to aluminum, rubber, or semiconductor cost swings?
- Is there meaningful aftermarket demand beyond original equipment supply?
What deserves closer monitoring next
The next chapter of the NEV industry will likely reward companies that connect aesthetics, efficiency, and perception rather than treating them as separate disciplines.
That means watching not only battery headlines, but also quieter indicators. Wheel aerodynamics, low-noise tire compounds, adaptive lighting logic, and sensor integration can reveal where future margins will form.
It also means reading the market through multiple lenses at once. Technical feasibility, regulatory readiness, commodity exposure, and replacement demand should be assessed together.
For anyone tracking the NEV industry, the most useful next step is to build a comparison framework around component function, compliance path, material sensitivity, and lifecycle value. That approach makes industry signals easier to rank and act on.