
Industry Portal
Related News
- 00
0000-00
Choosing Low Rolling Resistance Tires for Longer Mileage and Lower Fleet Fuel Costs - 00
0000-00
Rain Sensing Systems Calibration: Methods for Reliable Detection and Testing - 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects - 00
0000-00
Automatic Wipers for Buses: 7 Selection Criteria for Fleet Procurement - 00
0000-00
How Smart Optical Perception Prevents Collisions in Low-Light Driving Conditions
NEV Industry Signals That Point to the Next Supply Shift
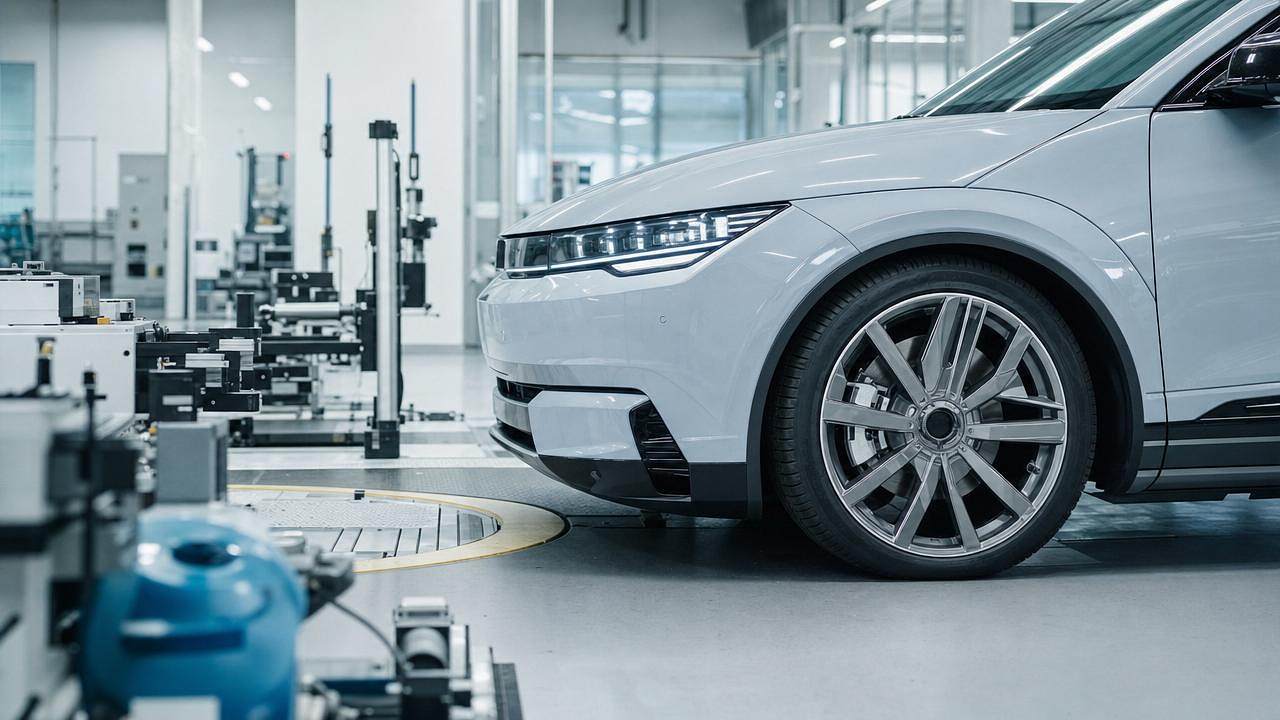
As the NEV industry moves into a new cycle of cost pressure, technology upgrades, and regional policy shifts, supply patterns are changing faster than many stakeholders expect. From lightweight exterior systems to smart lighting, tires, wheels, and sensor-driven components, the latest market signals reveal where sourcing risks and growth opportunities are emerging. This article helps information researchers decode those signals and anticipate the next supply shift with greater clarity.
For researchers tracking the NEV industry, the next supply shift is no longer defined by battery materials alone. Exterior and vision-related systems now carry growing strategic weight because they affect energy efficiency, safety performance, homologation readiness, software integration, and premium vehicle positioning at the same time. In many programs, a delay of just 4 to 8 weeks in one subsystem can disrupt launch timing across multiple regions.
This is especially relevant in the operating space covered by AEVS, where electric sunroof systems, aluminum alloy wheels, high-performance tires, LED headlight assemblies, and auto sensor switches increasingly interact as a connected engineering stack rather than isolated parts. For sourcing teams, product planners, and market analysts, understanding these interdependencies is essential to evaluating supplier resilience, cost exposure, and future demand concentration in the NEV industry.
Why the NEV Industry Is Entering a New Supply Transition
The current phase of the NEV industry is shaped by three overlapping forces: margin compression, platform standardization, and regional fragmentation. Vehicle makers are reducing part complexity where possible, but at the same time they are raising expectations for aerodynamic efficiency, intelligent lighting, quieter ride behavior, and integrated sensing. That creates a paradox: fewer supplier mistakes are tolerated even as technical requirements become more demanding.
In practical terms, the next supply shift is likely to appear in components that sit at the intersection of design, performance, and compliance. Wheels and tires affect rolling resistance, curb weight, noise, and braking stability. Headlights and sensor switches affect visibility, smart functions, and traffic regulation alignment under ECE or DOT pathways. Sunroof systems influence cabin comfort, roof weight, sealing reliability, and NVH targets. These are not secondary details; they are procurement-critical categories.
Three market pressures changing sourcing behavior
- Shorter product refresh cycles, often moving from 36 months toward 18 to 24 months for feature updates.
- Higher regional compliance variation, especially for lighting signatures, glazing, and road-contact performance.
- Stronger cost scrutiny on raw materials such as aluminum and rubber, where quarterly price swings can alter BOM assumptions.
Where information researchers should look first
A reliable reading of the NEV industry starts with supply signals that are measurable. Analysts should track at least 5 dimensions: tooling lead time, validation cycle length, raw material volatility, compliance complexity, and aftermarket pull. If 2 or 3 of these indicators tighten at the same time, a category is likely approaching a supply rebalancing event.
Fast-warning indicators
Examples include mold change requests rising within a 6-month period, wheel design revisions driven by brake cooling CFD updates, tire compound retuning for heavier vehicle classes, or higher demand for adaptive lighting modules with thermal management redesign. None of these signals should be read in isolation. Their value comes from pattern recognition across the broader NEV industry.
The Component Categories Most Likely to Trigger the Next Supply Shift
Not every category in the NEV industry will move at the same speed. The components most exposed to near-term supply shifts are those with multi-variable engineering requirements and a limited pool of qualified suppliers. In AEVS-relevant segments, five categories stand out because they combine technical complexity with direct impact on vehicle efficiency and customer-perceived quality.
1. Aluminum alloy wheels
Aluminum wheels remain a focal point because lightweighting targets are becoming tighter while design expectations continue to rise. In many NEV programs, moving from conventional cast configurations toward low-pressure casting or precision-forged solutions can reduce unsprung mass and improve aerodynamic behavior, but it also increases tooling precision demands and scrap sensitivity. Common lead times for new wheel programs can range from 8 to 16 weeks for tooling readiness, with validation extending beyond that depending on fatigue and impact testing requirements.
2. High-performance tires
Tires are under pressure from two sides in the NEV industry: heavier battery packs and stronger instant torque. Suppliers must balance grip, noise, wear resistance, and rolling resistance without making the ride too harsh. This often leads to compound reformulation, tread redesign, and sidewall reinforcement. A small performance adjustment can affect energy consumption, cabin acoustics, and replacement demand in the aftermarket within 12 to 24 months.
3. LED headlight assemblies
The transition from standard LED systems to matrix and projection-capable assemblies introduces thermal, optical, and software integration risks. As headlight functions expand, the supply chain becomes more sensitive to semiconductor availability, heat sink design, lens quality, and regulation-specific beam pattern requirements. In the NEV industry, this category can shift quickly because premium features often cascade down to mid-range vehicles within 2 product cycles.
The comparison below highlights how supply pressure differs across major AEVS component categories and why researchers should not treat them as equal-risk procurement lines.
The key takeaway is that the NEV industry will not experience one uniform shortage pattern. Instead, supply shifts will emerge by category, depending on whether performance requirements, validation demands, and regional certification rules tighten at the same time. Researchers who monitor these variables early can identify pressure points before they become visible in public pricing or delayed launch data.
The Signals Behind Regional and Technical Reallocation
Another reason the NEV industry is entering a new supply phase is regional divergence. A component that is easy to source for one market may require redesign, revalidation, or alternate materials for another. Lighting standards, wheel fitment preferences, climate exposure, road conditions, and consumer expectations all influence how suppliers allocate capacity. This means a nominally available part may not be practically available for a target program.
Policy and compliance as hidden capacity filters
In the NEV industry, compliance is not just a documentation matter. It can decide whether a supplier’s existing tooling, optical design, sealing architecture, or test process can be reused across 2 or 3 regions. If not, capacity becomes fragmented. For example, different beam-pattern or marking requirements in ECE and DOT environments may turn one global headlight concept into multiple engineering paths, each with separate validation workloads.
Material shifts that reshape vendor competitiveness
Aluminum price movement, specialty coating chemistry, and synthetic rubber availability do more than change cost. They can alter which suppliers remain competitive at a required quality level. A vendor that performs well during stable commodity conditions may struggle when input volatility exceeds 10% to 15% over two quarters and customers demand price hold periods of 90 to 180 days.
Common reallocation patterns
- Capacity shifts from high-mix premium parts to standardized high-volume parts.
- Regional production moves closer to final assembly to reduce logistics uncertainty.
- Programs adopt dual-source strategies for wheels, tires, or sensor-linked exterior parts.
- Aftermarket-oriented lines expand faster than OEM lines in replacement-heavy categories.
For AEVS-oriented research, the most valuable insight often comes from correlating design evolution with sourcing moves. If forged wheel demand rises while low-drag wheel CFD requirements become more detailed, or if self-sealing tire chemistry iterations accelerate while replacement cycles shorten, the NEV industry is signaling not just innovation, but likely supply reprioritization.
How Procurement and Research Teams Should Evaluate Suppliers Now
The next supply shift in the NEV industry will reward organizations that move beyond basic price comparisons. Information researchers and sourcing teams need a framework that captures engineering reliability, delivery resilience, compliance adaptability, and commercial logic together. In many cases, the difference between a stable supplier and a fragile one becomes visible only when multiple stress points appear within the same quarter.
Four evaluation dimensions that matter most
- Technical depth: ability to support simulation, testing, and application-specific tuning.
- Manufacturing flexibility: response capacity for variant changes, MOQ shifts, or schedule compression.
- Compliance readiness: familiarity with ECE, DOT, and market-specific validation expectations.
- Commercial resilience: ability to manage raw material fluctuations without quality drift.
The following table provides a practical screening approach for supplier review in the NEV industry, especially for exterior and vision-related component programs.
This framework helps decision-makers avoid a narrow lowest-cost mindset. In the NEV industry, a supplier that offers a 3% lower quote but requires 6 extra weeks for validation recovery or tooling correction may create a far larger commercial penalty than the initial savings suggest.
Questions researchers should ask during supply mapping
A structured interview or desk-review process should include at least 6 checks: What is the normal lead time? How often have material substitutions occurred in the past 12 months? Which test capabilities are internal versus external? How many platform variants can one line support? What are the usual MOQ terms? How quickly can compliance changes be absorbed without full redesign?
What the Next 12–24 Months May Look Like for AEVS-Relevant Segments
Looking ahead, the NEV industry is likely to favor suppliers and intelligence platforms that can connect engineering detail with market timing. In the next 12 to 24 months, exterior and vision systems will become even more decisive because they sit close to both regulatory pressure and customer-visible differentiation. That makes them highly sensitive to shifts in platform strategy.
Expected directional changes
- More wheel programs will be evaluated through both aerodynamic drag and brake-cooling simulations, not appearance alone.
- Tire development will increasingly focus on EV-specific load behavior, low-noise targets, and self-sealing or puncture-mitigation chemistry.
- Smart headlight demand will expand from premium trims toward broader segment deployment, increasing pressure on optics and thermal supply chains.
- Sensor-linked exterior components will need tighter integration with body electronics and perception logic.
Where opportunity is likely to grow
Growth is likely to be strongest where suppliers can prove both technical credibility and adaptation speed. This includes forged or precision-optimized wheels for efficiency-focused EV platforms, premium replacement tires for heavier NEV fleets, advanced lighting assemblies with superior anti-glare control, and sensor switch solutions that improve automation reliability in rain, low light, or dense traffic conditions.
A practical reading of the signal
When the NEV industry rewards parts that improve range, safety, and perceived quality at once, demand tends to consolidate around technically trusted vendors rather than purely low-cost entrants. For information researchers, that means the next supply shift may appear first in quality-qualified capacity allocation rather than in total nominal capacity. Watching who can deliver within 4 to 10 weeks, across 2 regulatory paths, without repeated engineering change orders, will matter more than headline expansion announcements alone.
The most important lesson is that supply change in the NEV industry is now a systems issue. Lightweight wheels, quiet high-load tires, matrix-capable headlights, advanced sunroof systems, and sensor-enabled exterior controls all reflect the same larger transition: vehicle makers want fewer compromises between efficiency, design, intelligence, and compliance. Organizations that read these signals early can make better sourcing decisions, identify higher-value demand pockets, and reduce launch risk before constraints become visible to the wider market.
AEVS is positioned to support that process through focused intelligence on exterior lightweighting, ground-contact performance, and smart optical perception. If you are evaluating sourcing risk, benchmarking suppliers, or planning the next move in the NEV industry, now is the right time to obtain a clearer component-level view. Contact us to explore tailored research support, product insight, or deeper strategic intelligence for your target market.