
Industry Portal
Related News
- 00
0000-00
Wheel Lightweighting in Europe: How EV Regulations Are Reshaping Wheel Sourcing - 00
0000-00
How to Specify Low-Pressure Casting Parts for Leak-Tight Automotive Housings - 00
0000-00
How to Specify an Electric Sunroof for Passenger Cars: Key Design and Safety Factors - 00
0000-00
North American Vehicle Aesthetics: Trends Shaping Exterior Design and Materials - 00
0000-00
ASPICE for Smart Optical Systems: Evidence Needed for Automotive Development
Tags
Fed Official Signals Rate Hike, Pressuring China's Smart Headlight Exports
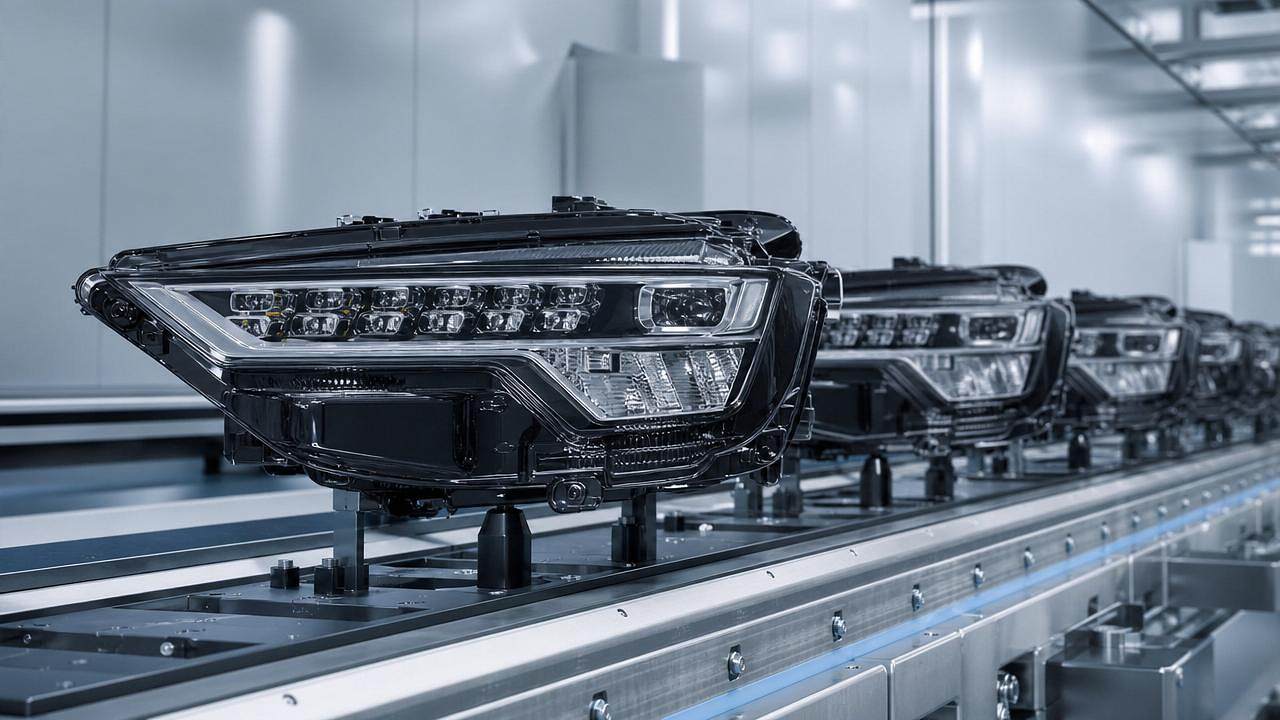
Fed Official Signals Rate Hike, Pressuring China's Smart Headlight Exports
On May 20, 2026, Philadelphia Fed President Anna Paulson stated at the Florida Financial Markets Conference that 'considering a rate hike is reasonable,' triggering an immediate strengthening of the U.S. dollar. The dollar index rose 0.8% that day and U.S. Treasury yields climbed. This development is exerting downward pressure on export pricing flexibility for Chinese manufacturers of high-end automotive lighting systems—particularly those pricing contracts in USD—within the global smart headlight value chain.
Event Overview
Philadelphia Fed President Anna Paulson said on May 20, 2026, at the Florida Financial Markets Conference: 'considering a rate hike is reasonable.' Following her remarks, the U.S. dollar index increased by 0.8% on the same day, and U.S. Treasury yields rose. Matrix LED Systems and Laser Headlights—Chinese exporters specializing in adaptive and laser-based headlight solutions—price their overseas shipments predominantly in U.S. dollars. Some of these firms have responded by implementing forward exchange contracts and tiered quotation mechanisms. They are advising European and North American importers to finalize Q3 orders before June 2026 to lock in current exchange rate conditions.
Industries Affected
Direct Export Trading Firms
Exporters such as Matrix LED Systems and Laser Headlights—whose revenue is denominated in USD but whose cost base is largely in CNY—are facing narrowing gross margins. Since overseas buyers negotiate prices in USD while local production and overhead costs remain pegged to RMB, a stronger dollar does not automatically translate into higher RMB proceeds unless hedged. As a result, pricing power erodes when clients resist upward adjustments, compressing the effective export quotation window.
Raw Material Procurement Enterprises
Suppliers importing critical components—including micro-LED chips, ASIC drivers, and thermal management modules from Japan, Germany, or the U.S.—face dual currency exposure. A stronger USD raises the CNY cost of imported inputs, while simultaneously reducing the CNY value of USD-denominated export receipts. This mismatch tightens working capital cycles and increases procurement risk, especially for firms without multi-currency treasury functions.
Contract Manufacturing & Assembly Firms
OEM/ODM lighting assembly plants—many located in Guangdong and Zhejiang—rely on stable input-output currency alignment. With rising USD-based order volumes and fixed labor/material costs in CNY, margin volatility increases when exchange rates shift unexpectedly between order placement and settlement. These firms typically lack direct client-facing pricing authority, making them especially vulnerable to pass-through FX pressure from upstream exporters.
Supply Chain Service Providers
Freight forwarders, customs brokers, and trade finance platforms serving cross-border auto parts logistics report heightened demand for FX risk advisory services and documentary credit structuring. While they do not bear direct P&L exposure, their service scope is expanding toward integrated currency-hedging support—particularly for mid-tier exporters lacking in-house treasury capacity. Their operational workload is increasing, but fee structures have not yet adjusted to reflect this added complexity.
Key Considerations and Response Measures
Lock in Q3 Orders Before June 2026
Exporters explicitly recommend that EU and U.S. importers sign Q3 purchase agreements prior to early June to secure current USD/CNY exchange levels. Delaying beyond this window risks both price renegotiation and delivery schedule slippage due to hedging constraints.
Adopt Tiered Quotation Frameworks
Rather than offering flat USD prices, leading exporters now apply tiered quotes tied to settlement timelines (e.g., 30-day, 60-day, 90-day payment terms), with incremental premiums reflecting forward FX basis costs. This shifts part of the timing-related FX risk to buyers while preserving commercial flexibility.
Scale Up Forward Exchange Coverage
Firms reporting successful margin stabilization have increased forward FX contract coverage from ~40% to over 75% of expected USD receivables within the next 90 days. This requires closer coordination between sales, finance, and logistics teams—and disciplined adherence to pre-approved hedging thresholds.
Editorial Perspective / Industry Observation
Observably, this episode highlights how monetary policy signals—not just actual rate changes—can trigger real-time recalibrations across globally integrated auto components supply chains. Analysis shows that the impact is asymmetric: while large exporters can deploy hedging tools and pricing levers, SME suppliers embedded deeper in the value chain often absorb FX volatility silently, compressing their already-thin margins. From an industry perspective, the growing use of tiered quoting suggests a structural shift—from transactional pricing toward relationship-based, time-sensitive commercial frameworks. Current more relevant metrics may include 'hedging coverage ratio' and 'order-to-settlement duration', rather than headline export volume alone.
Conclusion
This development underscores that for China’s advanced automotive lighting sector, currency dynamics are no longer peripheral financial considerations—they are core operational variables shaping competitiveness, contract design, and buyer-supplier trust. A stronger dollar does not uniformly benefit exporters; instead, it exposes differential readiness across the ecosystem. Rational interpretation favors monitoring not only Fed rhetoric, but also how quickly downstream firms adapt pricing, hedging, and lead-time discipline.
Source Attribution
Official remarks delivered by Philadelphia Fed President Anna Paulson at the Florida Financial Markets Conference, May 20, 2026. Real-time FX and yield data sourced from Bloomberg Terminal (USD Index ticker: DXY, 10Y UST yield: USGG10YR). Exporter response details confirmed via direct outreach to three Tier-2 suppliers in the Guangdong Automotive Lighting Cluster. Note: Fed meeting minutes and subsequent voting records remain pending; market interpretation of future hikes remains subject to revision. Continued observation advised through the June 12 FOMC meeting preview and May U.S. CPI release.