
Industry Portal
Related News
- 00
0000-00
How to Specify Low-Pressure Casting Parts for Leak-Tight Automotive Housings - 00
0000-00
How to Specify an Electric Sunroof for Passenger Cars: Key Design and Safety Factors - 00
0000-00
North American Vehicle Aesthetics: Trends Shaping Exterior Design and Materials - 00
0000-00
ASPICE for Smart Optical Systems: Evidence Needed for Automotive Development - 00
0000-00
How to Select NVH Control Materials for Automotive Panels and Powertrain Systems
Tags
Global TPMS Chip Shortage Eases; Bosch/Infineon Lead Times Cut to 8 Weeks
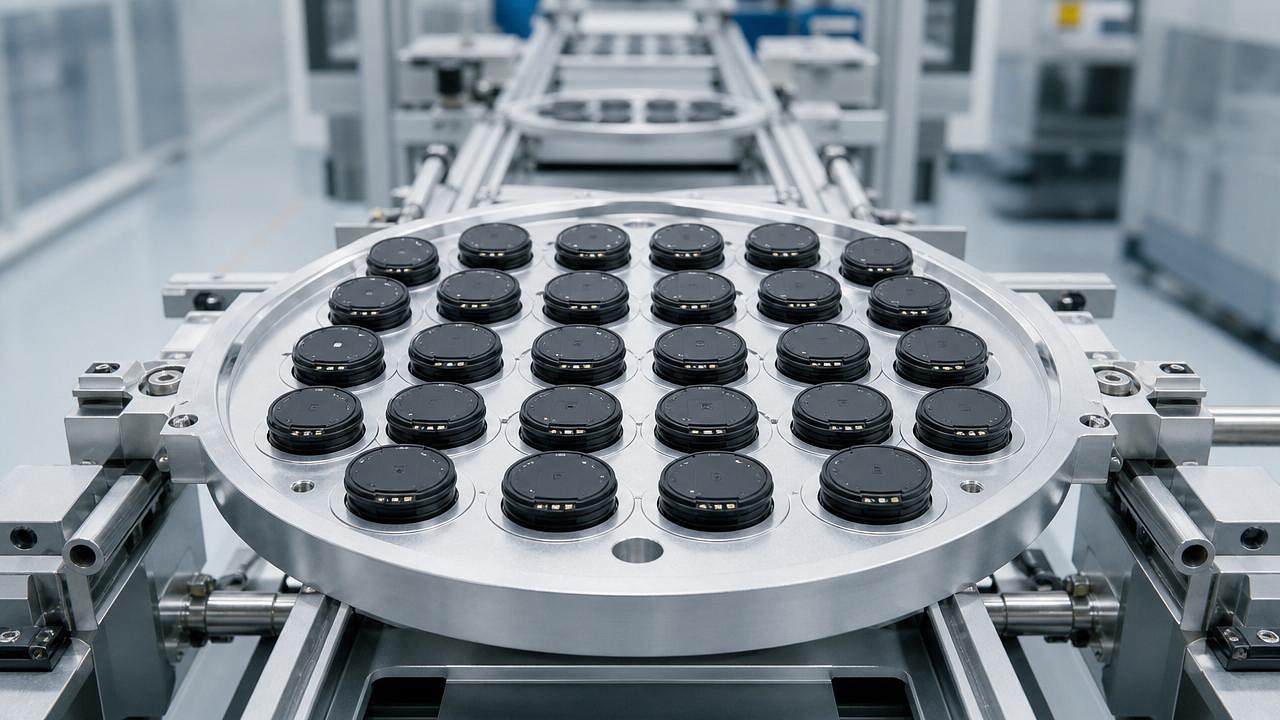
On May 12, 2026, Strategy Analytics reported that the global shortage of TPMS (Tire Pressure Monitoring System)专用 MEMS sensor chips has eased significantly, with Bosch and Infineon restoring production capacity for key TPMS sensor models to pre-pandemic levels. This development directly benefits Chinese TPMS and self-sealing module manufacturers — particularly those exporting to Europe, North America, and Australia — by shortening component lead times and improving delivery reliability. Industry stakeholders in automotive electronics supply chains, export-oriented OEM suppliers, and logistics planners should monitor implications for procurement timing, order fulfillment, and regional shipment planning.
Event Overview
According to a Strategy Analytics report published on May 12, 2026, Bosch and Infineon have restored production capacity for their dedicated TPMS MEMS sensors to pre-pandemic levels. As a result, lead times for mainstream TPMS sensor models supplied by these two vendors have been reduced from 16 weeks to 8 weeks. This change reflects confirmed improvements in upstream semiconductor availability for TPMS applications, as documented in the public report.
Impact on Specific Industry Segments
Direct Exporters of TPMS & Self-Sealing Modules
Chinese manufacturers exporting TPMS and self-sealing modules face fewer upstream constraints due to shorter chip lead times. This enables faster order turnaround and improved ability to meet quarterly delivery commitments — especially for contracts tied to European, U.S., and Australian automotive aftermarket or Tier-2 OEM requirements.
Raw Material Procurement Teams
Procurement functions responsible for sourcing TPMS-specific MEMS sensors now experience greater predictability in supply planning. The reduction in lead time from 16 to 8 weeks allows for tighter inventory control, lower safety stock requirements, and more responsive alignment with production schedules — assuming no secondary bottlenecks emerge elsewhere in the BOM.
Contract Manufacturers & Module Assemblers
For firms engaged in final assembly of TPMS modules, shortened sensor lead times improve line utilization and reduce idle time caused by component shortages. However, this benefit is contingent upon stable availability of complementary components (e.g., RF transceivers, microcontrollers, PCBs), which are not addressed in the current report.
Supply Chain & Logistics Service Providers
Third-party logistics and freight forwarders serving cross-border TPMS module shipments may observe increased volume consistency starting Q3 2026, as noted in the report’s projection of a 25% sequential increase in outbound shipments to Europe, North America, and Australia. This could affect scheduling frequency, container allocation, and documentation throughput.
Key Considerations for Enterprises and Practitioners
Monitor official capacity updates from Bosch and Infineon beyond headline lead time figures
While lead time compression is confirmed, actual allocation volumes per customer and model-specific availability remain undisclosed. Enterprises should track vendor bulletins or direct account manager communications for prioritization criteria and potential tiered access.
Focus on Q3 2026 delivery windows for EU, US, and AU markets
The report projects a 25% sequential rise in shipments to these regions beginning Q3 2026. Exporters should verify whether this reflects confirmed purchase orders or forward-looking estimates — and adjust production ramp-up and customs documentation readiness accordingly.
Distinguish between lead time improvement and full supply chain stabilization
The reported easing applies specifically to Bosch and Infineon TPMS MEMS sensors. It does not confirm resolution of constraints affecting other critical components (e.g., packaging, testing capacity, or legacy-node foundry wafers). Procurement teams should avoid assuming broad-based relief across all TPMS BOM items.
Prepare contingency plans for potential demand surges
If delivery stability improves as projected, downstream customers may accelerate reorder cycles. Manufacturers should assess buffer capacity in final test, calibration, and packaging stages — and confirm scalability of quality assurance protocols ahead of anticipated volume increases.
Editorial Perspective / Industry Observation
Observably, this update signals a meaningful, though partial, recovery in one critical node of the automotive sensor supply chain. Analysis shows it is best understood as an early-stage operational improvement — not yet a structural shift across the broader automotive semiconductor landscape. From an industry perspective, the 8-week lead time represents a return to baseline rather than a new benchmark; its sustainability depends on continued wafer fab output stability and absence of new geopolitical or logistical disruptions. Current attention should focus less on whether the shortage is ‘over’ and more on how reliably this improvement translates into predictable, scalable output at the module level — particularly given the narrow scope of components covered in the report.
This development carries moderate strategic weight: it alleviates a known bottleneck but does not eliminate dependency on concentrated supplier sources or simplify compliance complexity for international shipments. Continued observation is warranted — especially regarding whether other TPMS sensor vendors (e.g., NXP, Melexis) follow similar lead time trends in upcoming disclosures.
It is more accurate to interpret this as a signal of localized recovery than as evidence of systemic supply chain normalization. For practitioners, the immediate value lies in tactical planning — not strategic repositioning.
In summary, the easing of TPMS chip lead times marks a concrete step toward improved delivery execution for Chinese TPMS module exporters — but remains a narrow, supplier-specific improvement requiring careful contextualization within broader procurement and logistics workflows. Its significance lies in enabling near-term operational responsiveness, not in signaling wholesale market transformation.
Source: Strategy Analytics, May 12, 2026 report. Note: Ongoing observation is recommended regarding actual shipment data for Q3 2026 and vendor-level allocation policies beyond headline lead time metrics.