
Industry Portal
Related News
- 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects - 00
0000-00
Automatic Wipers for Buses: 7 Selection Criteria for Fleet Procurement - 00
0000-00
How Smart Optical Perception Prevents Collisions in Low-Light Driving Conditions - 00
0000-00
Private Label Tire Export: Evaluating Suppliers, Compliance, and Landed Cost - 00
0000-00
DOT-Compliant Truck Lighting: A Practical Guide to FMVSS 108 Requirements
Tags
CBP Rule Takes Effect for TPMS and Self-Sealing Tire Declarations
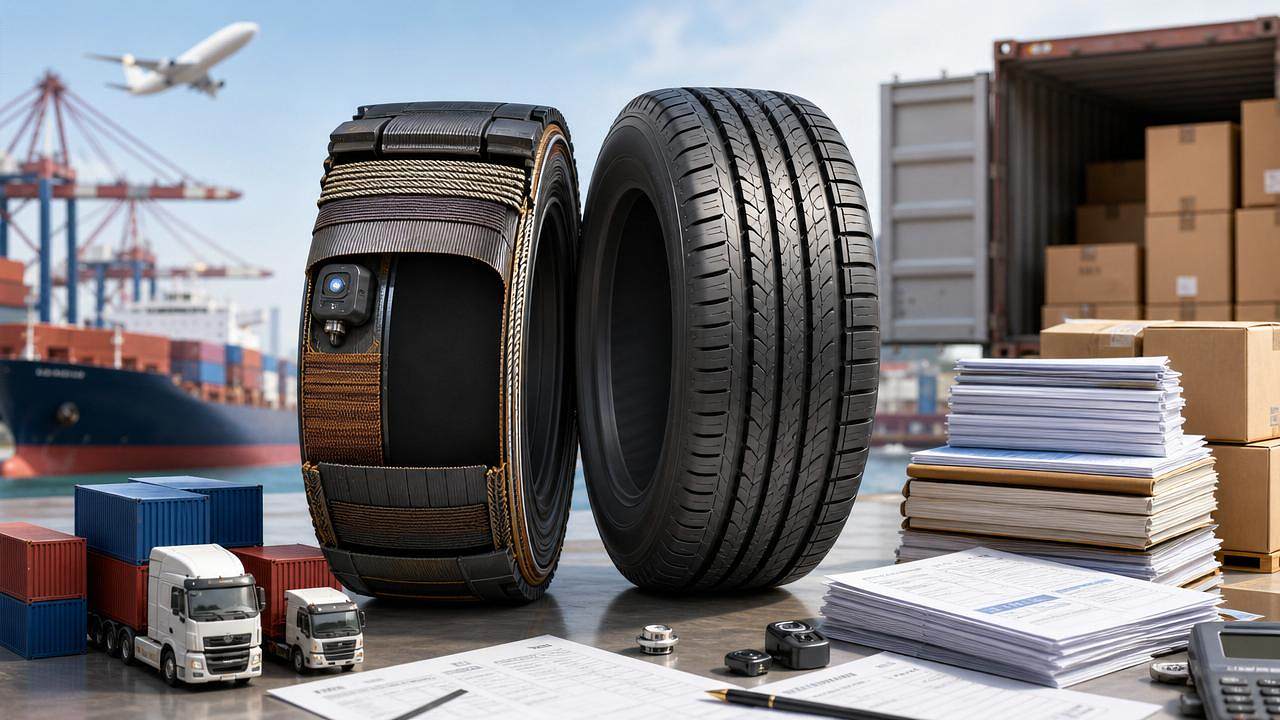
On June 14, 2026, U.S. Customs and Border Protection (CBP) put into effect a special declaration rule for imported tire products that include TPMS sensors or self-sealing layers. The change matters because it shifts these products from a more general tire declaration approach to a more component-specific compliance review, affecting exporters, importers, sourcing teams, customs filing workflows, and delivery planning. For companies shipping such products into the U.S. market, the immediate issue is not only how the goods are classified at entry, but also whether supporting origin and substance declarations are ready at the time of customs clearance.
What the new customs requirement specifically changes
According to the provided event summary, CBP's special guidance for imported intelligent tire components became effective on 2026-06-14.
The requirement applies to tire products containing either TPMS sensors or self-sealing coatings.
At customs declaration, the TPMS module and the sealant layer must be separately listed with 6-digit HS codes. The codes cited in the provided information are 8536.50 for the TPMS-related module and 3903.90 for the sealant material layer.
The same guidance also requires submission of a declaration covering the country of origin of the rubber raw materials and the REACH SVHC content.
The provided summary further states that non-compliant declarations will trigger 100% inspection and a 72-hour port hold.
Where the operational pressure is likely to appear first
For exporters shipping finished tire products
From an industry perspective, exporters are likely to feel the impact first at the documentation and shipment release stage. If a tire had previously been handled mainly as a finished product for customs filing purposes, the new rule introduces a clearer obligation to break out the TPMS module or self-sealing layer separately in the declaration set. That means product mapping, internal SKU review, and customs paperwork preparation may require closer coordination before cargo departure.
For sourcing and raw material compliance teams
Analysis shows that sourcing and compliance personnel will need to pay closer attention to traceability records for rubber inputs and to declarations related to REACH SVHC content. The practical challenge is not only having supplier data on file, but ensuring that the data can support a customs-facing declaration in a timely and consistent way. This can affect supplier communication, document collection, and internal approval workflows.
For manufacturers integrating sensors or sealant structures
Manufacturers using embedded TPMS components or self-sealing designs may need to review how product structures are described across technical files, bills of materials, and trade documentation. What deserves closer attention is whether the commercial description, customs declaration details, and supporting compliance statements align well enough to avoid mismatch during entry review.
For logistics and customs service providers
For customs brokers, freight teams, and other supply chain service providers, the rule raises the importance of pre-entry document checks. Observably, the stated consequence of 100% inspection and a 72-hour port hold means filing errors may quickly turn into scheduling disruption, delivery delay, and added coordination pressure across inland transport, warehousing, and customer communication.
What companies should review now
Check product classification readiness before shipment
It is more appropriate to understand the immediate task as a filing-readiness review. Companies handling affected tire products should verify whether the TPMS-related module or self-sealing layer is clearly identified in customs documentation and whether the required 6-digit HS coding treatment is reflected consistently across internal and external documents.
Reconfirm supplier declarations and traceability files
Analysis shows that the rubber origin declaration and REACH SVHC content statement are not peripheral paperwork under this rule; they are part of the customs compliance package described in the provided summary. Businesses should therefore pay attention to whether supplier-origin records, material statements, and compliance declarations can be produced in a usable format when shipments are booked or filed.
Review delivery planning for higher clearance sensitivity
Because the provided information states that non-compliance may lead to full inspection and a 72-hour hold, shipment planning deserves closer attention. Companies with tighter delivery windows, seasonal procurement schedules, or customer-specific fulfillment commitments may need to account for a higher risk of customs delay if documentation is incomplete or inconsistent.
Keep watching for execution detail and filing interpretation
The provided information confirms the effective date, the declaration obligations, and the stated consequence of non-compliance, but it does not provide further operational detail on filing interpretation. For that reason, companies should continue monitoring how the requirement is expressed in official practice, including customs-facing document expectations and any follow-on clarification relevant to declaration consistency.
Why this should be read as an execution signal
Observably, this development is more than a routine paperwork adjustment. By requiring separate HS identification for TPMS and self-sealing elements, together with rubber-origin and REACH SVHC declarations, the rule points toward more granular scrutiny of product composition within tire imports. Analysis shows that the market should read this primarily as an implemented compliance change rather than a preliminary policy discussion, because an effective date is stated and a concrete enforcement consequence is already attached to non-compliance.
At the same time, it would be premature to treat all downstream effects as settled. What deserves closer attention is how consistently the rule is applied in day-to-day clearance, how companies adapt their supporting files, and whether commercial documentation practices change across supply chains serving the U.S. market.
How to understand the change at this stage
At this stage, the most balanced reading is that the June 14 CBP requirement represents a landed rule change with immediate customs relevance for tire products containing TPMS sensors or self-sealing layers. Its significance lies less in headline policy language and more in the operational burden it creates for classification, traceability, and declaration consistency. From an industry perspective, this is best understood as a live compliance and delivery-risk issue that companies should address through document alignment and closer supply chain review, while still watching for further clarification in practical execution.
Basis of this article and points that still need verification
This article is generated based on the user-provided news title, event date, and event summary.
For developments of this kind, commonly relevant source types may include official notices, releases from regulatory authorities, customs or trade administration updates, industry association communications, standard-setting documents, and reporting by authoritative trade media.
No specific official source link was provided in the input, so the precise official publication path still needs ongoing verification.
Areas that remain worth monitoring include any further policy detail, customs interpretation in actual filing practice, compliance implementation standards, procurement and tender document changes, industry feedback, and how affected companies execute the requirement in shipment preparation and customs clearance.