
Industry Portal
Related News
- 00
0000-00
Choosing Low Rolling Resistance Tires for Longer Mileage and Lower Fleet Fuel Costs - 00
0000-00
Rain Sensing Systems Calibration: Methods for Reliable Detection and Testing - 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects - 00
0000-00
Automatic Wipers for Buses: 7 Selection Criteria for Fleet Procurement - 00
0000-00
How Smart Optical Perception Prevents Collisions in Low-Light Driving Conditions
Tags
Global Aluminum Price Surges 3.2%; Forged Lightweight Wheel Lead Times Extend to 14 Weeks
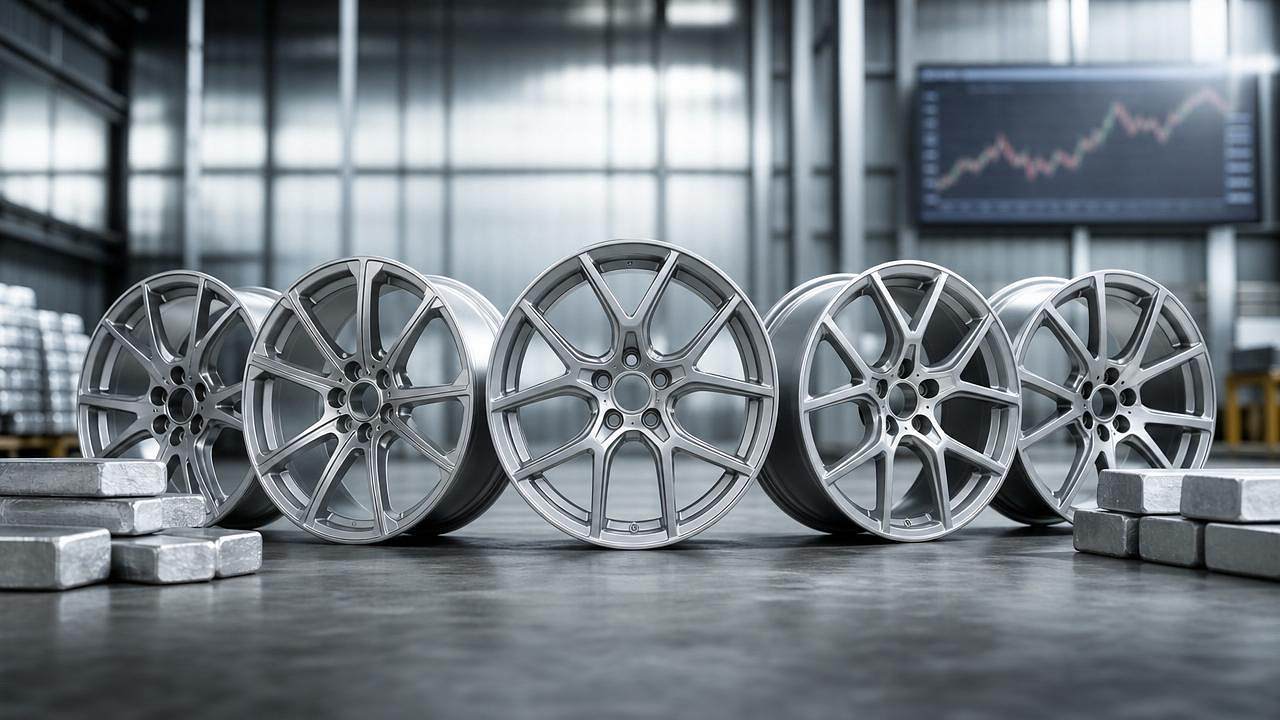
On May 26, 2026, LME aluminum futures closed at USD 2,841 per ton—the highest level since October 2025—driving extended delivery timelines for forged lightweight wheels across global supply chains. This development stems from concurrent disruptions in Middle East maritime logistics and intensified electrolytic aluminum production curbs in China.
Confirmed Market Developments
LME aluminum futures rose 3.2% on May 26, 2026, closing at USD 2,841/ton—the strongest settlement since October 2025. The surge is attributed to two concurrent supply-side pressures: sustained shipping delays in key Middle East transit corridors and upgraded output restrictions on Chinese primary aluminum smelters. As reported by major domestic suppliers of forged lightweight wheels, average export order lead times have increased from 10 weeks to 14 weeks. Several European OEMs and Tier-1 automotive suppliers have initiated evaluations of secondary or alternative wheel suppliers to mitigate delivery risk.
Impact Across Supply Chain Roles
Direct Exporters and Trading Firms
Export-oriented trading companies face compressed margin buffers due to sudden input cost escalation and inflexible forward pricing agreements. Contractual delivery clauses—particularly those referencing fixed lead times or liquidated damages—now carry heightened execution risk. Monitoring of Incoterms® application (e.g., FOB vs. CIF) and freight cost pass-through mechanisms has become operationally critical.
Raw Material Procurement Entities
Purchasers of primary aluminum, alloy ingots, and master alloys are confronting tighter availability and less predictable spot market liquidity. The linkage between LME price volatility and landed cost for billets used in forging operations has shortened significantly—requiring more frequent re-pricing cycles and revised hedging strategies against both price and physical availability risk.
Forging and Component Manufacturers
Manufacturers of forged lightweight wheels must reassess capacity allocation, inventory buffer policies, and furnace scheduling under extended raw material wait times. The shift from 10- to 14-week lead times signals a structural adjustment—not a transient delay—impacting production planning, tooling maintenance windows, and quality assurance cycle timing.
Logistics and Supply Chain Service Providers
Freight forwarders, customs brokers, and bonded warehousing operators report increased demand for real-time shipment visibility, alternative routing options (e.g., Red Sea bypass via Cape of Good Hope), and documentation readiness for aluminum-related export controls. Documentation accuracy—including metal composition certificates and origin declarations—is now subject to higher scrutiny by EU import authorities.
Key Operational Priorities for Enterprises
Reassess Delivery Commitments in Active Contracts
Review force majeure clauses, delivery tolerance windows, and penalty triggers in current export orders—especially those governed by EU automotive purchasing terms. Proactive communication with European customers regarding revised lead time expectations is essential to avoid contractual disputes.
Validate Raw Material Traceability and Compliance Documentation
Confirm that all aluminum billets and forgings meet REACH Annex XVII restrictions on heavy metals, as well as EU Battery Regulation-aligned carbon footprint reporting requirements where applicable. Suppliers should prepare mill test reports (MTRs), EN 10204 3.1 certifications, and updated environmental product declarations (EPDs).
Strengthen Secondary Supplier Qualification Protocols
Given European clients’ active evaluation of alternate wheel suppliers, manufacturers must ensure their own sub-tier forging partners hold valid IATF 16949 certification, dimensional inspection capability (CMM/CT scanning), and process validation records (e.g., heat treatment curve logs, ultrasonic testing reports) aligned with ISO 11484 and SAE J443.
Adjust Procurement Planning Cycles
Extend internal procurement lead times for aluminum-based inputs by at least four weeks; integrate LME price trend monitoring into quarterly raw material budgeting. Consider strategic pre-buying of certified billet stock for high-priority SKUs—subject to warehouse capacity and shelf-life constraints for surface-treated forgings.
Industry Perspective: Structural Shift in Aluminum-Intensive Supply Chains
Analysis shows this is not merely a cyclical price spike but a signal of tightening systemic constraints—both geographic (Middle East chokepoints) and regulatory (China’s energy-intensity-driven smelter caps). From an industry perspective, the 4-week extension in wheel lead times reflects deeper recalibration: longer billet casting-to-forging intervals, stricter emissions-linked dispatch protocols at smelters, and heightened due diligence on downstream carbon accounting. What deserves closer attention is how OEMs may begin embedding aluminum price volatility clauses into long-term sourcing agreements—and whether forged wheel qualification cycles will expand to include verified low-carbon aluminum sourcing pathways.
Strategic Implications for the Automotive Light-Weighting Ecosystem
This event underscores that material availability and regulatory compliance are now inseparable drivers of technical feasibility and commercial viability in lightweight component manufacturing. While aluminum remains indispensable for weight reduction targets, its supply chain is increasingly governed by intersecting trade, environmental, and transport governance frameworks—not just metallurgical performance. A rational assessment suggests resilience will depend less on cost arbitrage and more on integrated traceability, multi-sourcing agility, and proactive alignment with evolving EU sustainability reporting mandates.
Source Attribution and Verification Notes
This article synthesizes the user-provided headline, event date (May 26, 2026), and factual summary only. Specific official source links were not provided in the input and should be verified continuously. Stakeholders are advised to monitor updates from the London Metal Exchange (LME), China Nonferrous Metals Industry Association (CNIA), European Commission Directorate-General for Mobility and Transport (DG MOVE), and IATF Oversight Office for related regulatory implementation guidance, certification interpretation bulletins, and tender specification revisions.