
Industry Portal
Related News
- 00
0000-00
Which ISO Standards Govern Vehicle Lightweighting Materials and Validation Testing? - 00
0000-00
Wheel Lightweighting in Europe: How EV Regulations Are Reshaping Wheel Sourcing - 00
0000-00
How to Specify Low-Pressure Casting Parts for Leak-Tight Automotive Housings - 00
0000-00
How to Specify an Electric Sunroof for Passenger Cars: Key Design and Safety Factors - 00
0000-00
North American Vehicle Aesthetics: Trends Shaping Exterior Design and Materials
NEV Industry Trends: What Is Driving Battery Supply, Pricing, and Platform Decisions
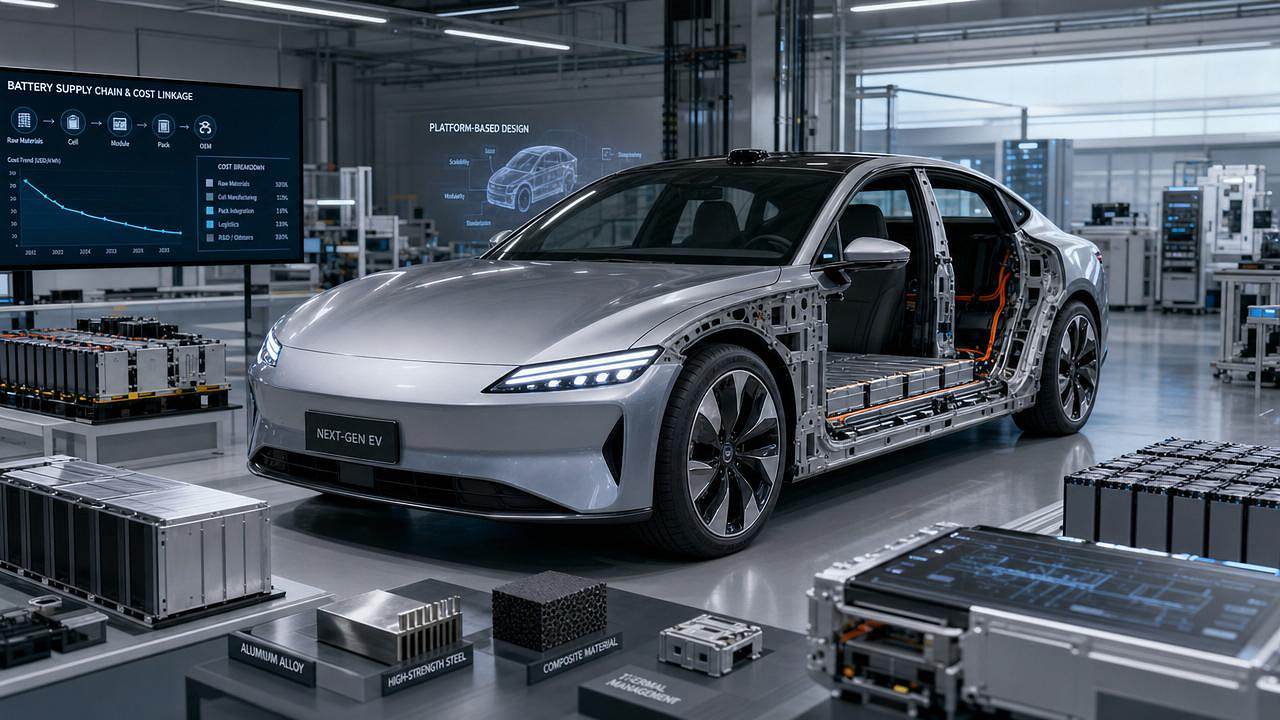
NEV industry growth is no longer shaped by demand alone
The NEV industry has entered a more complex phase. Volume still matters, but battery availability, material volatility, and platform speed now shape competitive position just as strongly.
That shift is visible across vehicle programs, supplier negotiations, and product architecture decisions. Pricing pressure no longer comes from one direction, and cost relief in one component can create strain elsewhere.
A more revealing signal is how battery strategy now affects the full vehicle. In the NEV industry, chemistry choices influence weight, wheel design, tire tuning, thermal balance, and even lighting energy management.
This is where broader vehicle intelligence becomes valuable. Observers such as AEVS increasingly connect battery economics with exterior lightweighting, ground contact systems, and smart optical perception rather than treating them separately.
Battery supply looks more stable, but the risk profile has changed
The headline story is no longer simple shortage. The NEV industry is moving from pure supply anxiety toward selective imbalance across chemistry, region, and quality tier.
Cell manufacturing capacity has expanded quickly. Yet usable supply depends on processing capability, localization rules, qualification cycles, and the ability to match pack design with platform targets.
This matters because not all batteries solve the same problem. LFP can support cost control and scale, while nickel-rich chemistries still serve premium range, performance, and cold-weather expectations.
As a result, supply resilience in the NEV industry is becoming a portfolio issue. The strongest programs are not only locking volume, but also preserving chemistry flexibility and pack-level design options.
- Regional content rules increasingly influence sourcing choices.
- Battery qualification timelines remain longer than many platform cycles.
- Revisions in safety standards can quickly reshape supplier rankings.
- Mid-market models need cost stability more than maximum energy density.
In practical terms, the NEV industry is shifting from securing any supply to securing the right supply with fewer downstream compromises.
Pricing pressure now travels through the entire vehicle bill of materials
Battery prices have eased from earlier peaks, but pricing behavior remains unstable. Lithium, graphite, copper, aluminum, and energy costs continue to move on different timelines.
That creates a more uneven cost environment for the NEV industry. One quarter may favor pack economics, while another exposes higher wheel, tire, or electronics costs.
The result is a new pricing logic. Vehicle cost control is less about one dramatic reduction and more about coordinated trade-offs across materials, software, aerodynamics, and component integration.
This broader cost transmission is one reason the NEV industry increasingly values cross-functional intelligence rather than isolated commodity tracking.
Platform decisions are getting faster, but not simpler
A second major shift is platform acceleration. Automakers want shorter launch cycles, shared architectures, and hardware that can support multiple battery sizes and software roadmaps.
On paper, modularity reduces risk. In reality, the NEV industry often pays for flexibility through added complexity in cooling, load paths, packaging, and exterior integration.
Battery packs are central here, but surrounding systems decide whether the platform actually delivers efficiency. Wheel aerodynamics, tire load behavior, sensor placement, and headlamp thermal design now interact more tightly.
That makes vehicle architecture a business decision as much as an engineering one. A platform that supports faster sourcing shifts may outperform a theoretically optimal design that cannot absorb market shocks.
Why exterior and vision systems matter more in this cycle
In the NEV industry, battery range is still a headline metric. Yet marginal gains increasingly come from the systems around the battery rather than from chemistry alone.
Low-drag aluminum alloy wheels can reduce aerodynamic penalties while managing brake airflow. High-performance tires now need to balance heavier vehicle mass with low noise and rolling resistance.
LED headlight assemblies and sensor switches also carry more strategic weight. Smarter optical systems improve safety, but they also influence energy use, thermal management, and compliance across regions.
This broader systems view aligns with AEVS coverage. It reflects a market reality where exterior aesthetics, dynamic perception, and energy efficiency are converging inside the same NEV industry decision chain.
The effects are spreading far beyond battery procurement
One common mistake is to treat battery uncertainty as a standalone sourcing issue. The stronger signal is how it changes product positioning, aftermarket demand, and technical priorities across the value chain.
When battery packs become heavier or less expensive, platform teams may shift budget toward lightweight wheels, upgraded tires, or more efficient sensor-driven body functions. Those moves reshape supplier opportunity.
When premium range becomes harder to justify, design differentiation matters more. In the NEV industry, lighting signatures, panoramic roof comfort, and wheel appearance can carry greater commercial weight.
The aftermarket also responds quickly. Replacement tire demand, forged wheel upgrades, and higher-end lighting retrofits often rise when owners want visible performance gains without changing vehicles.
- Vehicle programs face tighter trade-offs between cost, mass, and feature value.
- Regional compliance can force different hardware strategies on shared platforms.
- Aftermarket channels gain importance when replacement cycles accelerate.
- Technical branding becomes more valuable when raw range claims converge.
What deserves closer attention over the next planning cycle
For the NEV industry, the next phase will likely reward disciplined observation rather than aggressive assumptions. A few indicators now matter more than broad market sentiment.
Signals worth tracking
- The spread between entry-level battery chemistry pricing and premium chemistry pricing.
- Localization requirements that change the economics of cross-border sourcing.
- Material cost trends in aluminum and rubber, not only battery minerals.
- ECE and DOT related compliance shifts affecting lighting and sensing systems.
- Platform decisions that increase commonality but reduce room for regional tuning.
These signals help explain where the NEV industry may see margin pressure, where feature migration will continue, and where technical differentiation can still command attention.
A practical response starts with connected decisions
The immediate challenge is not simply to predict battery prices. It is to build decision routines that connect battery planning with vehicle mass, exterior efficiency, optical intelligence, and replacement economics.
That means comparing sourcing options against platform flexibility, testing cost assumptions against real material exposure, and checking whether feature content still supports market positioning.
In the NEV industry, resilience increasingly comes from coordinated architecture choices. A battery strategy performs better when matched with lightweight wheels, EV-specific tire tuning, efficient lighting, and smart sensing integration.
The market is still expanding, but the easy gains are fading. The next advantage will come from reading linked signals earlier, revisiting platform assumptions more often, and building phased response plans around real cost and compliance movement.
A useful next step is to map current exposure across batteries, aluminum, rubber, and optical electronics, then test how each shift changes product value, technical feasibility, and launch timing.