
Industry Portal
Related News
- 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects - 00
0000-00
Automatic Wipers for Buses: 7 Selection Criteria for Fleet Procurement - 00
0000-00
How Smart Optical Perception Prevents Collisions in Low-Light Driving Conditions - 00
0000-00
Private Label Tire Export: Evaluating Suppliers, Compliance, and Landed Cost - 00
0000-00
DOT-Compliant Truck Lighting: A Practical Guide to FMVSS 108 Requirements
NEV Industry Trends: How Battery Costs, Policy, and Exports Are Reshaping Competition
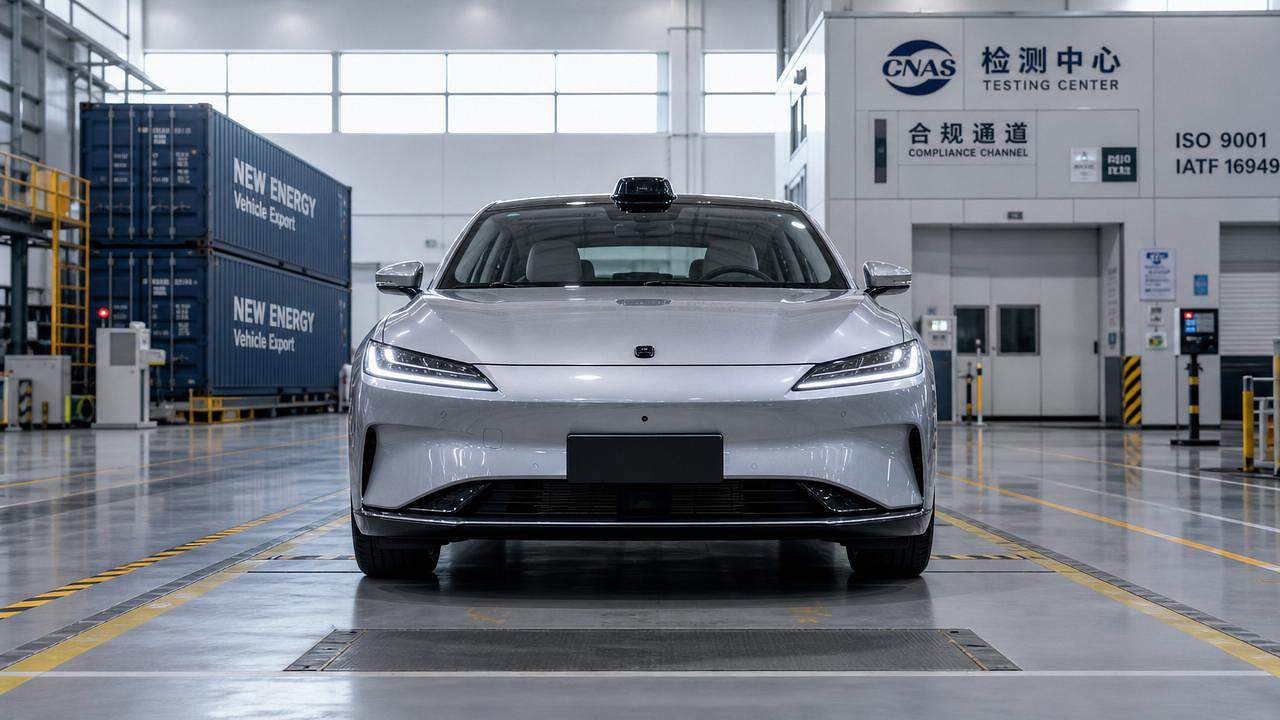
The NEV industry is moving into a tougher and more revealing phase of competition. Battery costs are easing, policy support is becoming more selective, and exports are no longer a side story. Together, these shifts are changing how vehicles are priced, where capacity is deployed, and which suppliers gain strategic relevance.
That matters far beyond battery packs and final assembly. In the current NEV industry, lightweight exteriors, wheel and tire efficiency, smart lighting, and sensor-linked body systems are becoming decision levers because they affect range, compliance, safety, and brand positioning at the same time.
For platforms such as AEVS, this is exactly where market intelligence becomes practical. The competitive edge now comes from connecting raw material trends, aerodynamic design, optical perception, and export compliance into one operating view rather than treating them as separate technical topics.
Why this cycle in the NEV industry looks different
Previous growth in the NEV industry was often driven by volume expansion, subsidies, and early adoption momentum. The current cycle is more complex. Cost reductions are real, but they do not automatically translate into stable margins.
Battery prices have fallen from earlier peaks, helping entry-level and mid-range models become more competitive. Yet lower battery costs also intensify price pressure, because automakers are expected to pass part of that benefit to the market.
At the same time, policy is becoming more conditional. Incentives increasingly reward local production, emissions performance, recycling capability, software safety, and trade compliance. In other words, access to demand now depends on operational discipline as much as technology.
Exports add another layer. Cross-border growth opens new revenue pools, but it also exposes the NEV industry to tariffs, certification hurdles, logistics risks, and regional preferences that can quickly alter the profitability of a model line.
Battery cost relief changes more than pricing
It is tempting to view battery cost decline as a simple margin benefit. In practice, it changes the entire product equation. When battery costs fall, automakers can reallocate value into range, software, cabin features, or exterior systems that improve efficiency and differentiation.
This is where the NEV industry connects directly with AEVS coverage areas. Lighter aluminum alloy wheels, lower rolling resistance tires, and aerodynamic exterior optimization can extend real-world range without increasing battery size.
That shift matters because battery savings are finite. If price competition absorbs all cost gains, the remaining path to profitability comes from smart engineering choices that improve energy efficiency per vehicle and raise perceived value without excessive material burden.
LED headlight assemblies and auto sensor switches also fit this logic. They are not cosmetic add-ons. Better optical control, adaptive lighting, and responsive sensing contribute to safety, energy management, and premium positioning, especially in export markets with stricter road standards.
Where cost pressure shifts next
As battery costs normalize, scrutiny moves to surrounding systems. Procurement teams and strategy leads increasingly look at:
- aluminum and rubber volatility, which affects wheels and tires;
- thermal efficiency of lighting and sensor modules;
- drag reduction from exterior form and wheel airflow;
- NVH performance in roof and upper-body systems;
- aftermarket replacement demand for higher-margin components.
Simple cost-down programs are no longer enough. The stronger play is cost intelligence linked with functional performance.
Policy is now shaping market structure, not just demand
Policy still supports the NEV industry, but the form of support is changing. Instead of broad stimulus alone, regulators are using standards, localization rules, and safety frameworks to influence who can compete sustainably.
In Europe and North America, compliance is extending beyond tailpipe logic. Authorities are paying closer attention to battery sourcing, recyclability, software assurance, lighting performance, and road safety alignment under ECE or DOT frameworks.
This matters for exterior and vision systems because seemingly secondary components can delay launch timing or complicate homologation. A headlamp design that performs well in one market may require meaningful adaptation in another.
The same applies to sensor-linked features such as automatic wipers, smart headlight activation, and blind-spot related body electronics. What counts as a convenience feature in one region may be treated as a safety-critical function elsewhere.
Exports are expanding, but the playbook is narrower
Export growth remains one of the clearest opportunities in the NEV industry. Still, the era of assuming that scale alone ensures overseas success is fading. Market entry now depends on fit, certification, and cost resilience.
Vehicle exterior and vision systems become more important during this stage because they are highly visible to regulators and end users. Tire behavior, headlamp performance, roof integration, and wheel durability directly influence local acceptance.
In practical terms, export-ready design means balancing aerodynamic efficiency with road conditions, climate, service infrastructure, and local taste. A silent low-resistance tire may perform differently across hot climates, rougher roads, or high-speed corridors.
More importantly, export competition rewards suppliers that can translate technical depth into commercial readiness. AEVS highlights this through intelligence on traffic regulations, raw material trends, aftermarket demand, and technical evolution in components that shape both driving quality and compliance.
What export-oriented programs usually prioritize
- stable homologation pathways across major regions;
- lighter components that protect range under real driving conditions;
- premium visible features that justify pricing abroad;
- replacement parts potential in local aftermarket channels;
- supplier responsiveness on documentation and validation.
Why exterior and vision systems are moving closer to strategy
In an earlier phase, many companies treated exterior systems as styling territory and vision systems as technical subassemblies. The NEV industry no longer has that luxury. These systems now affect efficiency, user trust, regulation, and lifecycle revenue.
Consider the five areas AEVS tracks closely. Electric sunroof systems influence thermal comfort, cabin acoustics, and energy use. Aluminum alloy wheels shape unsprung mass and aerodynamic drag. High-performance tires carry the burden of EV torque and weight.
LED headlight assemblies are becoming software-defined interaction points, not just light sources. Auto sensor switches connect body functions to perception logic, enabling safer automation in everyday use cases such as rain response, lighting activation, and blind-spot awareness.
Taken together, these systems create a bridge between vehicle aesthetics and dynamic driving perception. That bridge is commercially valuable because it links visible differentiation with measurable efficiency and safety outcomes.
How to read the next moves in the NEV industry
A useful reading of the NEV industry starts with the idea that not all growth signals are equal. Rising shipment numbers may look positive, but they reveal little without context on mix, geography, margin quality, and compliance exposure.
A better framework is to compare cost direction, policy fit, and export readiness at the same time. When these three vectors align, product programs tend to scale with fewer surprises.
Several questions usually sharpen the picture:
- Are battery savings being converted into durable product value?
- Do exterior and vision components support range and compliance together?
- Can the sourcing model withstand tariff or standards disruption?
- Is there aftermarket upside in wheels, tires, lighting, or sensors?
- Does technical documentation match the needs of export certification?
This is also where deeper intelligence matters. Data on raw material movement, brake airflow simulation, headlight thermal management, and coating evolution can directly improve scenario planning instead of sitting as isolated engineering detail.
A practical direction for the next decision cycle
The NEV industry is not entering a simpler stage. It is entering a more integrated one. Battery costs, policy shifts, and export momentum are all important, but their real effect appears in the interaction between cost structure, component performance, and market access.
That is why the most useful next step is not to chase a single headline indicator. It is to build a clearer evaluation model around lightweighting, optical safety, tire-road efficiency, standards alignment, and regional demand patterns.
For companies tracking the NEV industry closely, the stronger position comes from treating exterior and vision systems as strategic variables. Reviewing those variables through an intelligence lens such as AEVS can help clarify where pricing power is weakening, where compliance risk is rising, and where the next defensible opportunity is likely to emerge.
The most reliable path forward is to compare platform choices, supplier depth, and export assumptions before the next investment or sourcing decision. In this cycle, better judgment often starts with seeing the links others still treat as separate.