
Industry Portal
Related News
- 00
0000-00
Choosing Low Rolling Resistance Tires for Longer Mileage and Lower Fleet Fuel Costs - 00
0000-00
Rain Sensing Systems Calibration: Methods for Reliable Detection and Testing - 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects - 00
0000-00
Automatic Wipers for Buses: 7 Selection Criteria for Fleet Procurement - 00
0000-00
How Smart Optical Perception Prevents Collisions in Low-Light Driving Conditions
Tags
- smart optical perception
- LED headlight assemblies
- auto sensor switches
- dynamic driving perception
- automotive vision systems
- alloy wheels
- forged wheels
- silent tires
- headlight assemblies
- smart headlights
- replacement tires
- custom forged wheels
- lightweight wheels
- automotive vision systems Europe
- lightweight alloy wheels
Automotive Vision Systems Europe: Market Drivers, Regulation, and Supplier Outlook
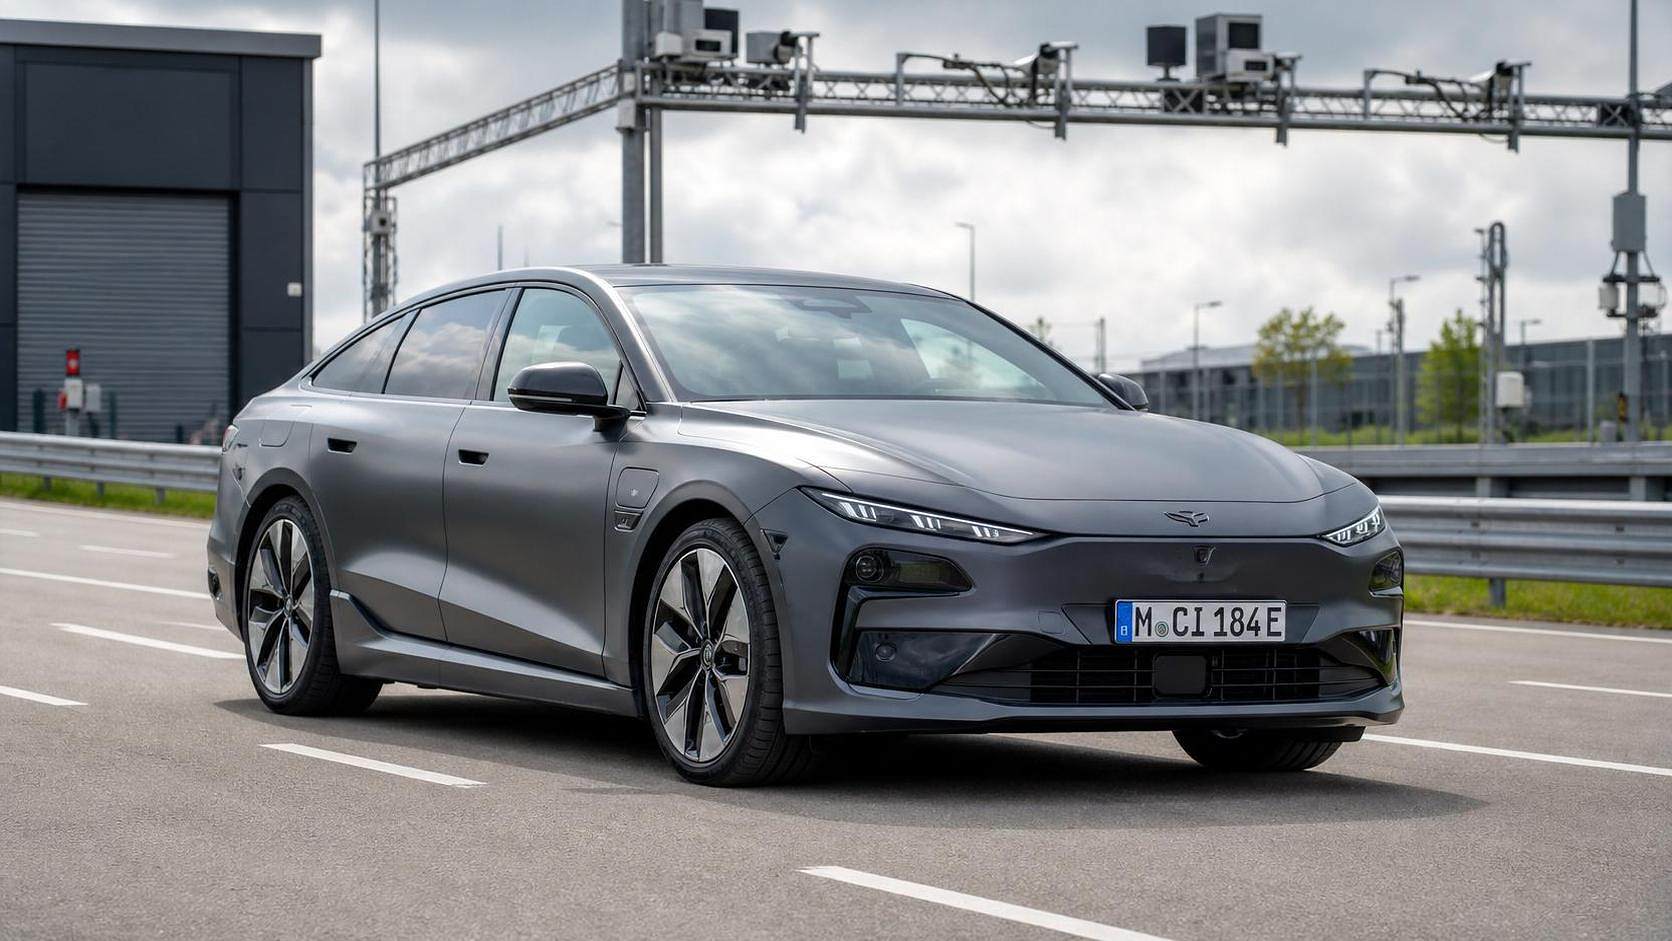
Automotive vision systems Europe is moving from a niche engineering topic to a board-level market issue. The shift is being driven by tighter safety regulation, faster EV adoption, and rising expectations for intelligent exterior functions.
What makes this market more complex is that vision performance no longer sits inside headlamps alone. It now connects lighting, sensing, software, wheels, tires, aerodynamics, and energy efficiency across the full vehicle exterior.
That broader view matters in Europe, where compliance, design sophistication, and electrification are advancing together. For companies tracking growth and risk, automotive vision systems Europe has become a useful lens for judging supplier strength and future positioning.
Why the market is expanding beyond traditional lighting
In simple terms, automotive vision systems Europe covers the technologies that help vehicles see, signal, interpret surroundings, and support safer driving decisions. That includes adaptive lighting, sensor-triggered systems, optical perception modules, and related exterior components.
The definition has widened because modern vehicles rely on coordinated exterior intelligence. A matrix LED headlamp, for example, performs better when it is integrated with sensors, control logic, thermal management, and vehicle energy strategy.
The same logic now reaches components once treated as separate categories. Wheel aerodynamics, tire behavior, body-mounted sensors, and smart sunroof systems all affect visibility, driver perception, and vehicle efficiency in real operating conditions.
This is where the AEVS perspective is useful. Its focus on smart optical perception, lightweight exterior components, and dynamic driving perception reflects how the European market increasingly evaluates performance as a connected exterior system, not a standalone part.
The forces shaping automotive vision systems Europe
The first force is regulation. European safety requirements continue to raise the baseline for driver assistance, visibility, glare control, and sensor reliability. Compliance is no longer a final checkpoint. It shapes product architecture from the start.
The second force is EV growth. Electric vehicles bring heavier curb weights, different thermal loads, stronger torque delivery, and sharp pressure on range. Those conditions change how exterior systems are designed, sourced, and optimized.
The third force is customer expectation. Premium and upper-mid vehicle segments increasingly treat intelligent lighting, silent tires, lightweight wheels, and automatic sensor response as part of the overall driving experience rather than optional add-ons.
A fourth driver is software-led differentiation. European OEMs are looking for more than physical hardware. They want adaptive beam control, road guidance projection, anti-glare masking, sensing accuracy, and integration with broader body electronics.
Regulation is creating both pressure and opportunity
In automotive vision systems Europe, regulation often acts as a market filter. Suppliers that understand ECE requirements, validation protocols, and traceability expectations are better placed to win long-term programs.
This also affects aftermarket opportunities. Replacement lighting, premium wheel packages, and high-performance tire products face stricter scrutiny when they influence safety, vehicle handling, or energy consumption.
Where exterior intelligence is creating business value
The value case is no longer limited to crash avoidance. In Europe, vision-related exterior systems now contribute to brand identity, decarbonization targets, cabin comfort, and operating efficiency.
LED headlight assemblies are a clear example. They have evolved from illumination hardware into software-managed optical platforms. Their value sits in beam precision, thermal stability, power efficiency, and interaction with sensing architecture.
Auto sensor switches also matter more than before. Rain sensing, light sensing, blind-spot support, and activation logic influence both safety and user experience. In a crowded market, small perception improvements can shape overall vehicle quality.
Even wheels and tires belong in this conversation. Lightweight alloy wheels can improve EV efficiency and brake airflow. Tire compounds and structures affect grip, rolling resistance, road noise, and how well vehicles maintain stable sensing and handling behavior.
That is why automotive vision systems Europe should be viewed through a cross-functional lens. Exterior aesthetics, aerodynamic performance, perception accuracy, and range management are increasingly interdependent commercial variables.
How the supplier landscape is changing
Supplier competition in Europe is shifting from component delivery to system credibility. Buyers are looking for partners that can show regulatory fluency, materials expertise, simulation capability, and production consistency across multiple exterior categories.
This favors suppliers with deeper engineering resources. Thermal models for smart headlights, CFD work on wheel airflow, and chemistry knowledge around self-sealing tire coatings are no longer fringe capabilities. They support mainstream sourcing decisions.
Another important change is the growing premium on intelligence portals and sector analysis. AEVS reflects that shift by combining compliance tracking, raw material signals, optical research, and commercial insight across exterior and vision technologies.
For many companies, the real differentiator is not only manufacturing scale. It is the ability to explain how a product performs under European operating conditions, how it fits EV design priorities, and how it supports long-term platform evolution.
Practical scenarios that deserve closer attention
One high-value scenario is the premium EV segment. Here, automotive vision systems Europe is tightly linked to range anxiety, silent ride expectations, and visual brand language. Headlights, wheels, and tires all influence purchase perception and operating efficiency.
Another scenario is urban mobility and compact platforms. These vehicles need smart sensing and dependable visibility without cost inflation. Integration discipline matters more than feature quantity.
Commercial and fleet applications create a different challenge. Durability, maintenance cycles, and legal conformity can outweigh design novelty. In that setting, a reliable sensor switch or long-life lighting unit may deliver stronger returns than advanced display effects.
The aftermarket is also gaining relevance. Europe continues to show demand for custom forged wheels, premium replacement tires, and lighting upgrades. However, aftermarket growth depends on technical credibility and careful navigation of compliance boundaries.
How to assess opportunities without missing hidden risk
The first step is to avoid evaluating automotive vision systems Europe as a single category. The market is made up of connected subfields with different cost structures, qualification cycles, and performance metrics.
It helps to test opportunities against a few concrete questions:
- Does the solution align with current and upcoming European regulatory requirements?
- Can the supplier prove performance under EV-specific loads and thermal conditions?
- Is the value based on measurable efficiency, safety, or perception gains rather than feature claims?
- How exposed is the cost base to aluminum, rubber, electronics, or optical component volatility?
- Can the technology scale across OEM and aftermarket channels without weakening compliance confidence?
This is also why intelligence quality matters. A market signal is more useful when it combines policy tracking, materials movement, engineering interpretation, and demand-side evidence instead of isolated news fragments.
What stronger positioning looks like
Stronger positioning usually comes from connecting product capability with a clear use case. In automotive vision systems Europe, that may mean linking optical precision with anti-glare compliance, or lightweight wheel design with EV range and airflow benefits.
The same applies to communication. Companies that translate engineering detail into commercial relevance often perform better in long-cycle European programs, where trust is built through evidence and consistency.
What to watch next
The next phase of automotive vision systems Europe will likely be defined by convergence. Lighting, sensing, lightweighting, and exterior comfort technologies will keep moving closer together as OEM platforms become more software-led and energy-sensitive.
That makes narrow category analysis less reliable. A better approach is to map where regulation, optical intelligence, material science, and user experience intersect. Those intersections are where the strongest opportunities usually emerge.
For the next round of decisions, it is worth building a simple review framework: track European compliance shifts, compare supplier engineering depth, test EV relevance, and examine whether the value proposition holds across both OEM and aftermarket conditions.
Used that way, automotive vision systems Europe becomes more than a trend label. It becomes a practical framework for deciding where to invest attention, where to reduce exposure, and where exterior intelligence can create durable competitive advantage.