
Industry Portal
Related News
- 00
0000-00
Choosing Low Rolling Resistance Tires for Longer Mileage and Lower Fleet Fuel Costs - 00
0000-00
Rain Sensing Systems Calibration: Methods for Reliable Detection and Testing - 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects - 00
0000-00
Automatic Wipers for Buses: 7 Selection Criteria for Fleet Procurement - 00
0000-00
How Smart Optical Perception Prevents Collisions in Low-Light Driving Conditions
Tags
- electric sunroof systems
- aluminum alloy wheels
- high-performance tires
- LED headlight assemblies
- vehicle aesthetics
- electrochromic dimming
- electric sunroof
- alloy wheels
- performance tires
- LED headlights
- headlight assemblies
- matrix LED headlights
- smart headlights
- automotive optical systems
- lightweight wheels
- automotive optical systems Europe
Automotive Optical Systems in Europe: Key Market Shifts and OEM Demand Signals
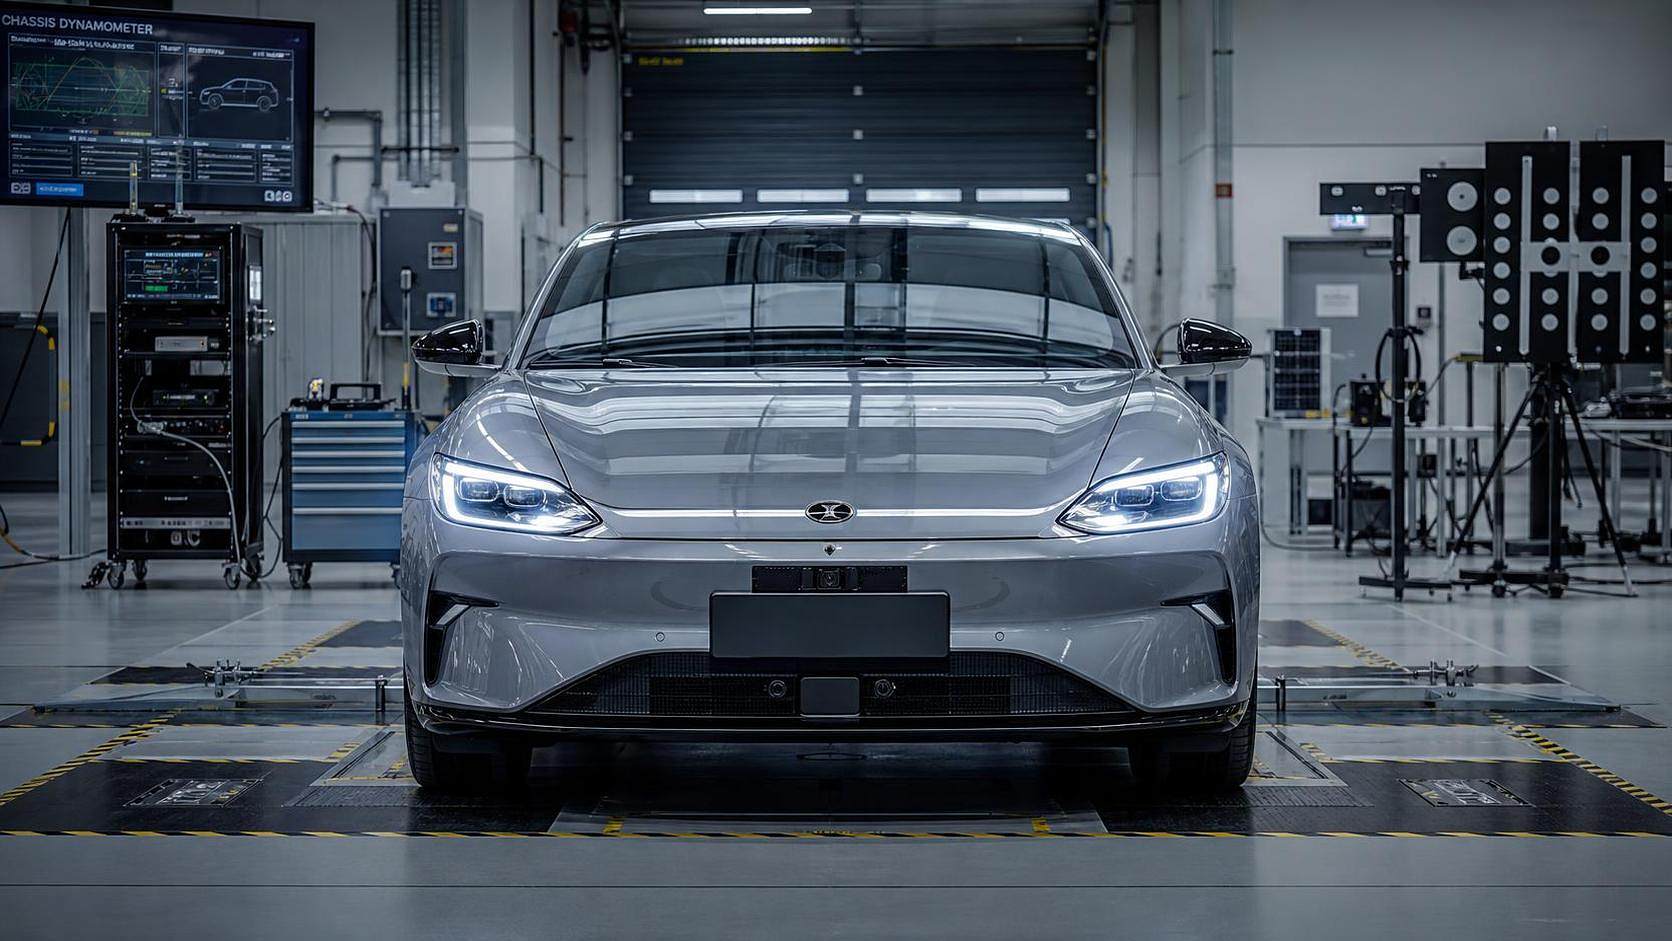
Europe’s vehicle vision landscape is moving into a sharper competitive phase. In automotive optical systems Europe, regulation, electrification, and software-defined vehicle design are no longer separate topics. They now shape the same sourcing conversation.
That matters because optical systems are no longer limited to illumination. They now connect headlights, sensors, switches, thermal control, exterior styling, and perception logic into one operational layer around safety, energy use, and brand positioning.
For companies tracking OEM demand signals, Europe offers an unusually clear view of where exterior intelligence is heading. The region combines strict homologation pressure, premium design expectations, and rapid EV platform rollout.
Why automotive optical systems Europe is gaining strategic weight
Automotive optical systems Europe sits at the intersection of compliance and product differentiation. Carmakers need better visibility, cleaner sensor performance, lower energy draw, and more recognizable lighting signatures at the same time.
In practice, this means the headlamp is no longer a standalone part. It is part of a broader exterior architecture that includes electronics, sensing interfaces, body integration, and software control.
The same shift affects adjacent systems. Smart sunroof glazing changes cabin light management. Wheel aerodynamics influence thermal behavior and range. Sensor switches support automated wipers and headlight activation.
This is why the AEVS perspective is useful. It treats vehicle aesthetics, driving perception, lightweighting, and optical intelligence as connected business variables rather than isolated component categories.
What counts as an optical system now
The market definition has widened. In automotive optical systems Europe, optical value comes from how light is generated, directed, sensed, interpreted, and integrated into the vehicle exterior.
LED headlight assemblies remain the most visible category. Yet demand is increasingly linked to matrix capability, adaptive beam shaping, anti-glare masking, thermal stability, and digital control readiness.
Sensor-linked optical functions are also moving up the priority list. Rain-light automation, blind-spot support, ambient sensing, and road-scene response require tighter coordination between optics and body electronics.
Even non-lighting exterior parts can influence optical performance. Surface quality, airflow, vibration behavior, and heat management affect sensor accuracy and lamp durability over time.
The practical scope of current demand
The market shifts driving current demand signals
The first shift is regulatory intensity. European rules around visibility, glare, pedestrian safety, and driver assistance readiness are pushing OEMs toward more advanced optical architectures.
The second shift is EV platform scaling. Electric vehicles need lower power consumption and tighter package efficiency. Lighting modules, sensor covers, and exterior interfaces are all being redesigned around that constraint.
The third shift is styling competition. Brand identity in Europe increasingly depends on front-end and rear-end light signatures. Optical systems now carry both safety performance and visual differentiation.
A fourth shift is software control. OEM demand is moving from hardware-only specifications toward systems that support updates, calibration, and broader perception architectures over the vehicle lifecycle.
This is where automotive optical systems Europe becomes more than a component market. It becomes a decision space where optics, electronics, and exterior engineering are evaluated together.
Signals that deserve closer reading
- More RFQs asking for integrated thermal and optical validation, not just photometric output.
- Greater interest in scalable lamp platforms for multiple EV trims and regional variants.
- Rising attention to sensor cleanliness, lens protection, and weather-response consistency.
- Higher value placed on suppliers that understand ECE compliance and design-language execution together.
How adjacent exterior systems influence optical decisions
One mistake is to assess optical systems in isolation. In Europe, OEM programs increasingly evaluate them against the wider exterior and dynamic-driving package.
Take aluminum alloy wheels. Their aerodynamic design affects airflow around the vehicle and can indirectly influence brake heat behavior and local thermal conditions near exterior sensing components.
High-performance tires matter as well. Noise reduction, grip behavior, and EV load characteristics shape the driving environment in which visibility and optical confidence are judged.
Electric sunroof systems add another layer. Electrochromic dimming and cabin light control influence interior perception quality, reinforcing the broader move toward managed optical environments inside and outside the vehicle.
AEVS frames these connections well. It links smart headlights, lightweight wheels, advanced tires, and sensor switches through a shared logic of efficiency, perception, and exterior value creation.
What to evaluate in real business terms
In automotive optical systems Europe, technical capability alone is not enough. The better question is whether a solution can hold its value across regulation, integration complexity, and production scale.
Thermal management is one critical lens. Advanced LEDs and matrix systems perform only as well as their heat control, especially in compact EV front-end designs.
Validation depth is another. A polished prototype can still fail under road contamination, vibration, humidity, or long-cycle switching demands common in European use conditions.
Supply resilience also matters. Material volatility, especially in electronics, aluminum, and specialty polymers, can shift total project economics faster than many sourcing models assume.
Finally, commercial credibility matters more when systems become cross-functional. Suppliers that can explain optical performance, compliance pathways, and exterior integration in one story tend to travel further.
A practical evaluation framework
- Check whether performance claims are tied to ECE-ready validation, not lab-only demonstrations.
- Review how the system behaves under EV packaging limits and thermal density.
- Compare software upgrade potential with current vehicle electrical architecture.
- Assess whether exterior styling demands create extra tooling or calibration risk.
- Look for evidence of cross-domain knowledge, especially between optics, sensing, and lightweight exterior structures.
Where opportunity is likely to concentrate next
Short term, demand should remain strongest in premium and upper-mid EV platforms. These programs have the clearest business case for matrix lighting, perception-linked switching, and signature-based front-end design.
Mid term, more value may shift toward scalable architectures. OEMs want common hardware blocks that can be tuned across markets, trim levels, and software packages without full redesign.
There is also growing room in replacement and upgrade channels. As optical systems become more complex, aftermarket demand may tilt toward premium, certified, and technically trusted solutions rather than generic substitution.
That trend aligns with AEVS intelligence priorities. The strongest commercial insight often comes from reading technology performance together with compliance, materials cost, and channel behavior.
A grounded next step for market assessment
The most useful approach is to treat automotive optical systems Europe as a connected market map rather than a single product category. Headlights, sensors, switches, materials, thermal design, and exterior aerodynamics increasingly influence one another.
A workable next step is to build a comparison grid around three factors: compliance exposure, integration difficulty, and value per vehicle platform. That makes demand signals easier to rank.
It is also worth tracking whether a target program rewards feature depth, software flexibility, or cost-stable modularity. Those paths can look similar at concept stage, but they lead to different sourcing outcomes.
In a market where perception systems increasingly shape both safety and brand identity, the better decisions will come from reading technical detail in its full vehicle context. That is where the strongest signals in automotive optical systems Europe are now emerging.