
Industry Portal
Related News
- 00
0000-00
How to Specify Low-Pressure Casting Parts for Leak-Tight Automotive Housings - 00
0000-00
How to Specify an Electric Sunroof for Passenger Cars: Key Design and Safety Factors - 00
0000-00
North American Vehicle Aesthetics: Trends Shaping Exterior Design and Materials - 00
0000-00
ASPICE for Smart Optical Systems: Evidence Needed for Automotive Development - 00
0000-00
How to Select NVH Control Materials for Automotive Panels and Powertrain Systems
Tags
EU Smart Sunroof Demand Jumps 34% in Q2
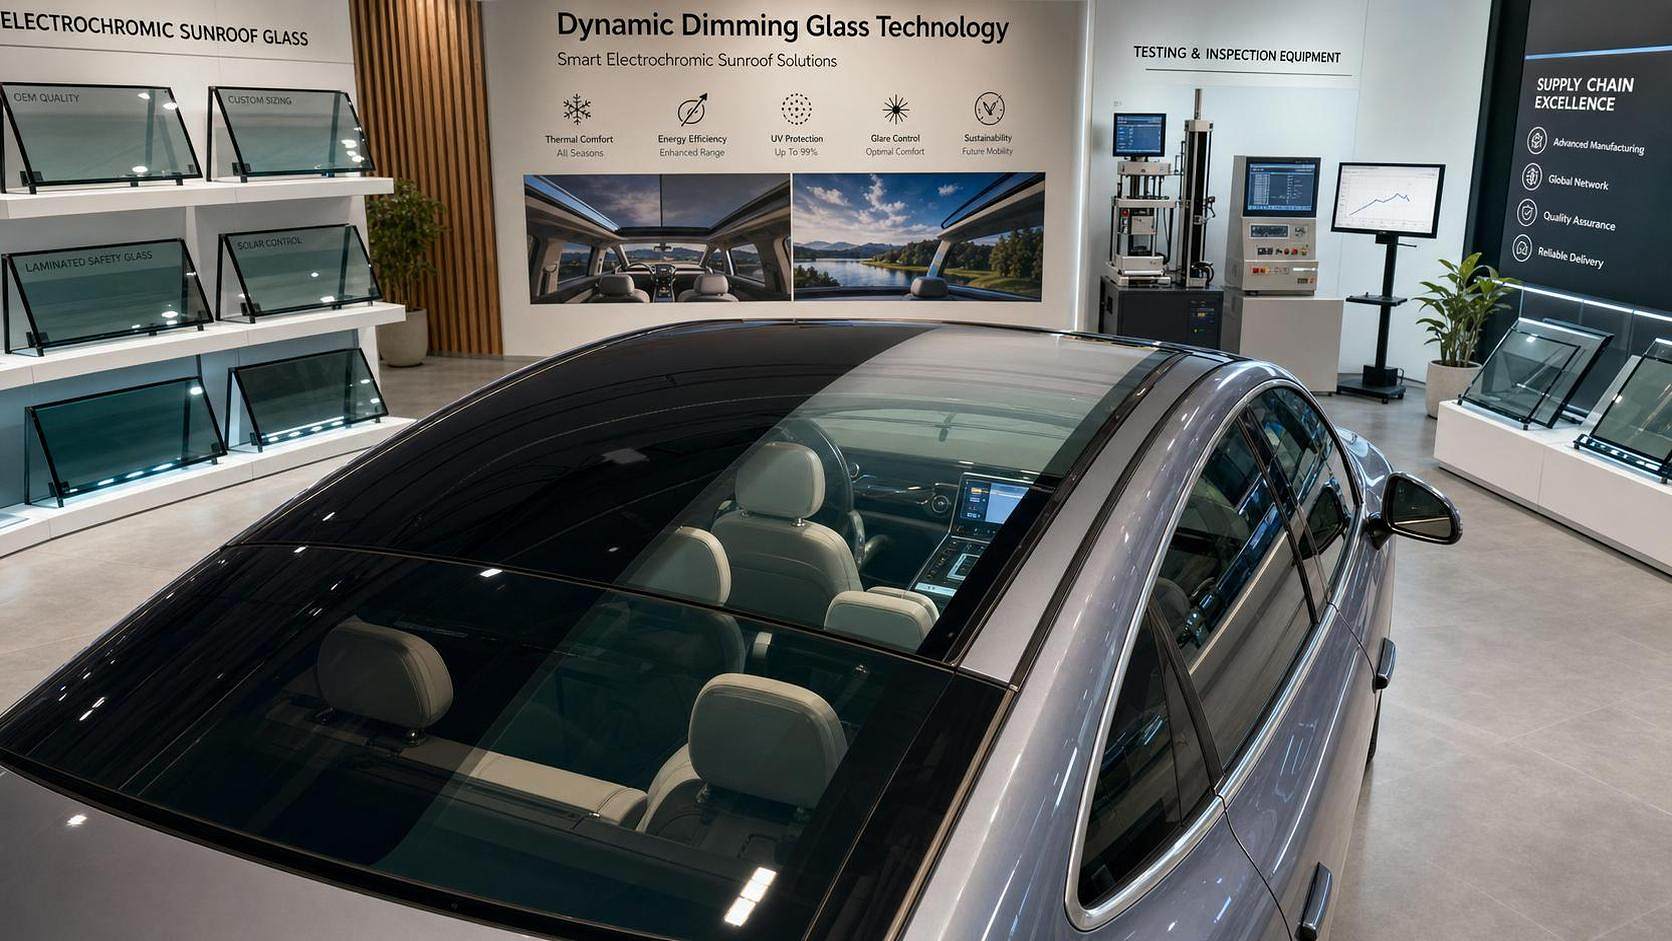
The timing of the underlying event was not explicitly stated in the source input, but the market signal is clear: ACEA’s latest aftermarket intelligence brief released on July 4 shows that EU demand for panoramic sunroofs using smart dimming glass rose 34% year over year in Q2 2026. The development is worth close attention from component suppliers, distributors, procurement teams, and vehicle cabin solution providers because it links climate-driven comfort demand directly to product mix, inventory pressure, and supplier qualification activity.
What the latest market brief confirms
Based on the information provided, the confirmed facts are limited but meaningful. ACEA’s latest aftermarket intelligence brief indicates that demand across the EU for panoramic sunroofs equipped with smart dimming glass increased 34% year over year in Q2 2026. The cited drivers are extreme summer temperatures and stronger consumer preference for cabin environments that improve UV blocking and NVH performance.
The same input states that distributors in Germany and the Netherlands are reporting stockouts of electrochromic panels measuring 1.8 square meters and above. It also states that Chinese suppliers holding ISO 11452-8 EMC and EN 16777 thermal stability certifications are moving through qualification processes more quickly.
Where the pressure is likely to appear across the chain
Inventory strain is becoming visible at the distribution end
From an industry perspective, distributors are among the first to feel this shift because the reported stockouts in Germany and the Netherlands point to immediate pressure in availability rather than only a change in end-market preference. What deserves closer attention is whether larger-format electrochromic panels remain the main bottleneck, since that can affect order allocation, replenishment timing, and quotation validity.
Qualified suppliers may gain attention faster than before
Analysis shows that suppliers already carrying the cited ISO 11452-8 EMC and EN 16777 thermal stability certifications may be better positioned in current sourcing discussions. The impact is likely to appear in customer screening, sample approval, and commercial negotiation stages, because qualification speed matters more when distributors are already facing shortages.
Procurement and program teams need to watch specification shifts
For procurement teams and downstream application businesses, the reported demand increase is relevant not only as a volume issue but also as a specification issue. Observably, the market signal is tied to UV-blocking and NVH-optimized cabin expectations, which means buying decisions may become more sensitive to performance documentation, not just panel availability.
Supply-chain service providers may face shorter response windows
For logistics and supply-chain coordination roles, the practical effect may be tighter delivery planning and less room for reactive scheduling. Analysis shows that when qualification cycles accelerate at the same time that stockouts are reported, service providers may need to manage faster document turnover, shipment timing, and communication between distributors and certified suppliers.
What companies should be tracking now
Certification readiness and technical documentation
What deserves closer attention is whether suppliers can clearly present the certifications specifically mentioned in the market brief. In this case, ISO 11452-8 EMC and EN 16777 thermal stability references are not a side detail; they are part of the market context behind faster qualification. Companies involved in sourcing or sales should therefore pay attention to the completeness and consistency of technical files and compliance materials used in customer review.
Exposure to large-format electrochromic panels
Businesses active in panoramic roof systems should closely monitor demand and supply conditions around 1.8m²+ electrochromic panels, because that is the size category explicitly associated with stockouts in the provided information. For distributors and purchasing teams, the immediate issue is not broad market storytelling but whether current commitments, lead-time assumptions, and alternative supply arrangements remain realistic.
Customer communication on comfort-related value points
Analysis shows that the demand increase is being linked to extreme summer temperatures and to preference for UV-blocking and NVH-optimized cabin environments. That means customer-facing teams should pay attention to how product value is described in quotes, technical exchanges, and account discussions. The key point is alignment with the performance concerns now visible in the market signal, rather than generic feature promotion.
Distinguishing demand momentum from durable market reset
Companies should also separate immediate aftermarket tightness from a confirmed long-term structural shift. Observably, the information provided supports stronger demand and faster qualification activity, but it does not on its own confirm how long those conditions will persist. For management teams, this affects how aggressively to plan stock, allocate engineering support, or lock in supply commitments.
How this signal should be interpreted at this stage
Analysis shows that this development is best read as a meaningful near-term market signal with possible longer-term implications, rather than as a fully settled industry outcome. The combination of a 34% year-over-year increase, stockouts in specific EU markets, and accelerated qualification of certified Chinese suppliers suggests that cabin comfort features are gaining more operational weight in purchasing and distribution decisions.
At the same time, it is more appropriate to understand this as a development that still requires observation. The provided information does not establish whether the demand spike is primarily seasonal, whether it will broaden beyond the currently highlighted panel segment, or how sustained the faster qualification trend will be across the wider market.
Why the development matters beyond a single quarter
From an industry perspective, the importance of this update lies in how several signals are appearing together: climate-related demand pressure, preference for specific comfort functions, inventory shortages in named distribution markets, and a visible role for certification-backed suppliers. That combination matters because it can influence sourcing priorities and channel behavior even before a longer trend is fully confirmed.
It is more appropriate to understand this update as a focused but credible indicator of changing demand conditions in the EU panoramic sunroof segment. The prudent conclusion is not that the market has reached a final new equilibrium, but that relevant businesses should monitor specification-led demand, availability of larger electrochromic panels, and the pace of supplier qualification very closely.
Source basis and verification notes
This article is generated from the user-provided news title, event timing note, and event summary. The specific official source link was not provided in the input, so continued verification remains necessary. For this type of industry update, commonly relevant source categories may include industry association briefings, official company disclosures, authoritative media reporting, distributor market updates, and standard or certification-related documentation.
Where continued observation is required, the main follow-up areas are whether additional official statements clarify timing, whether stockout conditions persist in the cited EU markets, and whether accelerated qualification activity continues among suppliers holding the certifications named in the source summary.