
Industry Portal
Related News
- 00
0000-00
How to Specify Low-Pressure Casting Parts for Leak-Tight Automotive Housings - 00
0000-00
How to Specify an Electric Sunroof for Passenger Cars: Key Design and Safety Factors - 00
0000-00
North American Vehicle Aesthetics: Trends Shaping Exterior Design and Materials - 00
0000-00
ASPICE for Smart Optical Systems: Evidence Needed for Automotive Development - 00
0000-00
How to Select NVH Control Materials for Automotive Panels and Powertrain Systems
Tags
China's Shipbuilding New Orders Up 195.2% YoY in Q1 2026
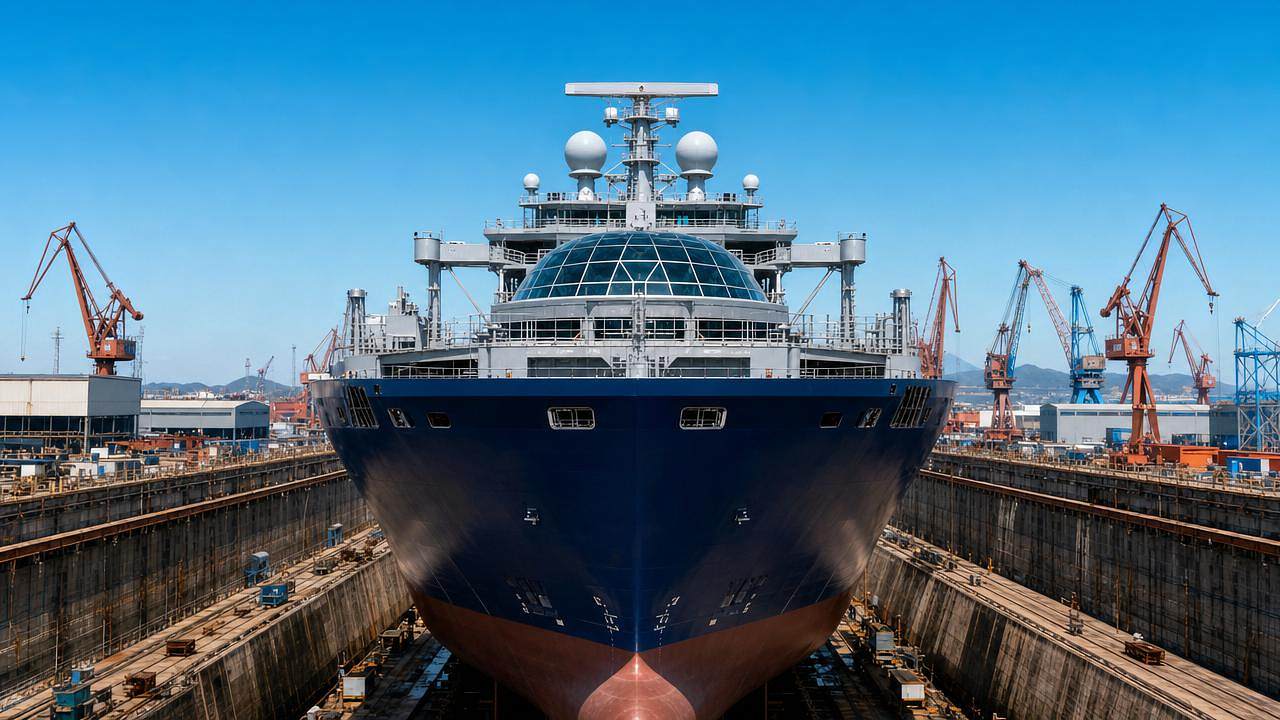
China’s shipbuilding industry recorded 59.53 million DWT of new orders in Q1 2026 — a 195.2% year-on-year increase — with over 42% of orders specifying LNG-powered, battery-electric, or intelligent navigation systems. This surge is now driving measurable demand shifts in adjacent automotive exterior and vision system supply chains, particularly among international shipowners. Companies involved in smart glazing, high-reliability radar, and marine-grade tire monitoring systems should monitor procurement trends closely.
Event Overview
As of March 31, 2026, China’s new shipbuilding orders totaled 59.53 million deadweight tons (DWT), up 195.2% year-on-year. Of these orders, vessels equipped with LNG propulsion, battery-electric propulsion, or integrated intelligent navigation systems accounted for more than 42%. Concurrently, international shipowners increased procurement inquiries for marine-adapted automotive-grade components: smart dimming glass for cabin roofs, salt-fog-resistant blind spot radars, marine-grade TPMS, and self-sealing tires — with inquiry volume rising 67% quarter-on-quarter.
Industries Affected
Direct Exporters of Automotive Exterior & Vision Components
These firms are seeing renewed interest from maritime equipment integrators and shipyards seeking certified, marine-qualified variants of existing automotive products. The impact manifests as higher inbound technical queries, requests for extended environmental testing (e.g., salt fog, thermal cycling), and growing emphasis on classification society compliance documentation (e.g., DNV, LR, CCS).
Material & Component Suppliers (e.g., Glass Substrate, Radar ICs, Sensor Modules)
Suppliers providing base materials or sub-assemblies used in smart glazing, radar housings, or TPMS sensors face upstream specification tightening. Demand signals now include requirements for enhanced corrosion resistance, broader operating temperature ranges (-25°C to +70°C), and traceability aligned with marine QA protocols — not just automotive standards (e.g., AEC-Q200).
OEM-Level Tier-1 System Integrators
Integrators developing full cockpit or hull-monitoring systems are encountering early-stage RFQs referencing dual-use architecture — i.e., scalable designs that accommodate both automotive and marine validation pathways. Impact includes earlier engagement in naval architecture reviews and increased need for cross-sector regulatory familiarity (e.g., IMO MSC.428(98) for autonomous functions).
Supply Chain & Certification Support Providers
Third-party testing labs, classification society liaison services, and export compliance consultants report rising consultation volume around marine adaptation pathways for ISO/SAE-certified automotive parts. Key pressure points include accelerated turnaround expectations for salt-spray testing (per ISO 9227), EMC validation under marine-specific configurations, and documentation harmonization across IEC 60092 and ISO 16750 standards.
What Relevant Enterprises Should Monitor and Act On
Track classification society guidance updates for hybrid-electric and autonomous vessel systems
Analysis shows that DNV, ABS, and CCS have recently published draft advisories on software-in-the-loop (SIL) validation for intelligent navigation integration — a prerequisite for many newbuild contracts. Firms supplying supporting hardware should review these drafts for implications on interface definitions and cybersecurity documentation requirements.
Monitor procurement focus shifting toward marine-grade variants of three priority categories
Observably, inquiry growth is concentrated in: (1) electrochromic glass with IP66-rated actuation and UV-stable interlayers; (2) 77 GHz blind spot radars qualified to IEC 60092-502 (marine EMC) and ISO 16750-4 (mechanical shock); (3) TPMS modules rated for continuous immersion testing (IEC 60529 IPX8) and featuring redundant pressure sensing. These represent near-term specification anchors.
Distinguish between tender-stage interest and firm order conversion
Current inquiry volume reflects early-stage sourcing activity tied to design-phase decisions — not yet firm purchase orders. From an industry perspective, this means technical readiness (e.g., test reports, marine qualification roadmaps) carries more weight than production capacity at this stage. Firms should prioritize documentation alignment over volume ramp-up.
Prepare cross-functional engineering and commercial coordination for marine certification timelines
Marine qualification typically adds 4–6 months to standard automotive validation cycles. Current more relevant action is internal alignment between R&D, quality assurance, and sales teams on acceptable lead times, test scope trade-offs, and classification society engagement models — rather than initiating full-scale certification immediately.
Editorial Perspective / Industry Observation
This data point is best understood as an early signal — not yet a structural shift — in cross-sector technology adoption. Analysis shows the 195.2% order growth reflects strong short-term momentum driven by LNG infrastructure expansion and IMO 2023 fuel regulation deadlines, but marine electrification remains concentrated in short-sea and inland segments. Observably, the ripple into automotive component supply chains is real and measurable, yet still confined to prototype and pre-qualification phases. The trend matters less as immediate revenue driver and more as a leading indicator of where functional safety, environmental resilience, and system-level integration expectations are heading across mobility sectors.
Conclusion
The Q1 2026 shipbuilding order surge signals accelerating convergence between marine decarbonization goals and terrestrial mobility component capabilities. It does not indicate broad-based substitution of automotive systems into ships, but rather selective, function-driven adoption where performance, reliability, and regulatory traceability align. For affected enterprises, the current situation is better interpreted as a specification-readiness checkpoint — not a market-entry trigger — demanding focused technical preparation rather than strategic pivot.
Source Attribution
Main source: Official quarterly shipbuilding statistics released by China Association of the National Shipbuilding Industry (CANSI), dated March 31, 2026. Procurement inquiry data derived from aggregated anonymized RFQ logs from three major global maritime procurement platforms (MarineBuy, ShipParts Connect, and NavTrade Hub). Note: Marine qualification timelines, classification society advisory status, and final order conversion rates remain subject to ongoing observation and are not yet publicly confirmed.