
Industry Portal
Related News
- 00
0000-00
Choosing Low Rolling Resistance Tires for Longer Mileage and Lower Fleet Fuel Costs - 00
0000-00
Rain Sensing Systems Calibration: Methods for Reliable Detection and Testing - 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects - 00
0000-00
Automatic Wipers for Buses: 7 Selection Criteria for Fleet Procurement - 00
0000-00
How Smart Optical Perception Prevents Collisions in Low-Light Driving Conditions
What Is Driving Demand for Electrochromic Sunroof Systems in Europe?
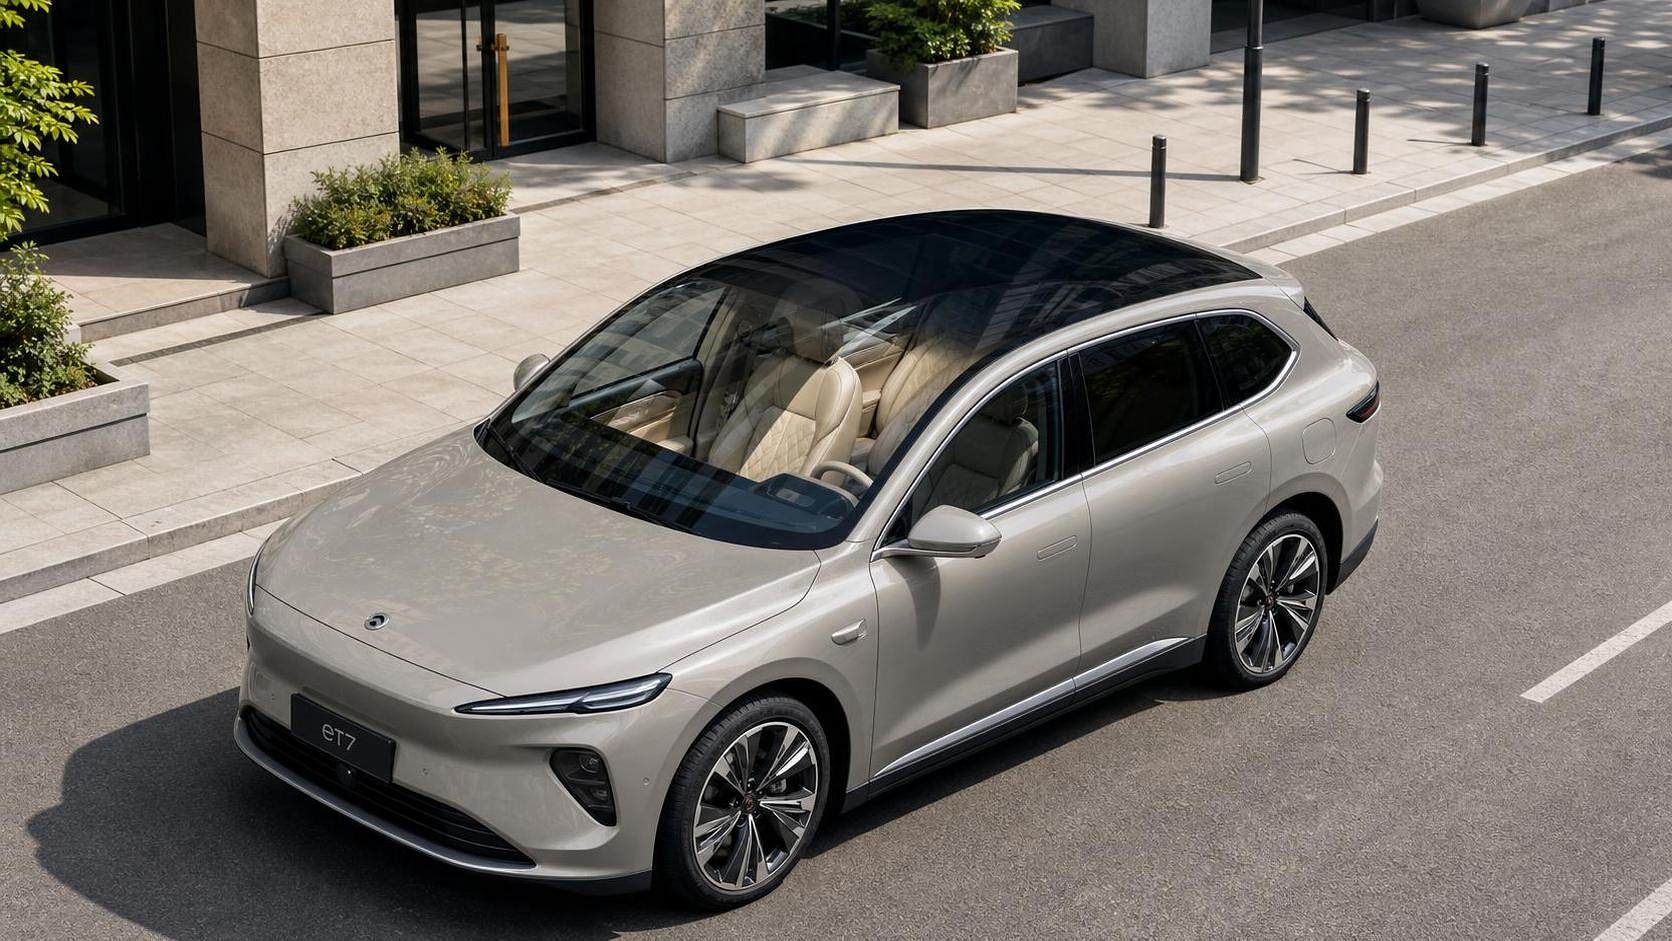
What Is Driving Demand for Electrochromic Sunroof Systems in Europe?
Demand for electrochromic sunroof Europe solutions is no longer confined to a few showcase models. The stronger signal is that glass roof strategy has become part of a broader vehicle architecture discussion in Europe: cabin comfort, thermal load, energy use, perceived premium value, and software-defined user experience are now being evaluated together. For OEMs operating in the region, a roof is not simply an opening panel or fixed glazing area. It is increasingly treated as a controllable interface that affects both design language and vehicle efficiency.
That shift matters because Europe is a market where design restraint and engineering discipline tend to meet. Consumers have shown sustained interest in panoramic glazing, especially in battery-electric and upper-trim vehicles, yet regulators and fleet buyers continue to pressure manufacturers on energy consumption and lifecycle emissions. Electrochromic sunroof systems sit exactly in that tension. They promise a brighter, more open cabin without the same dependence on mechanical shades, and they offer a route to managing solar gain more intelligently than conventional tinted glass alone.
The immediate driver is simple: large glass roofs have become mainstream faster than legacy shading concepts have evolved. In an EV, every watt used for cooling and every kilogram added above the beltline draws scrutiny. A panoramic roof improves showroom appeal, but it can also increase heat ingress and create NVH and weight trade-offs if the system is not carefully engineered. Electrochromic dimming gives OEMs another calibration layer. Instead of treating cabin comfort as a static glazing choice, they can adjust transparency to weather, route, occupancy, or drive mode. That moves the roof from passive component to managed system.
Why Europe Is a Particularly Active Test Bed
Europe’s demand pattern is shaped by several overlapping realities rather than one headline trend. The first is the region’s uneven climate. A vehicle sold across Southern Europe, Germany, France, the Nordics, and the UK faces very different daylight intensity and seasonal use cases. Static tinting works reasonably well for a narrow set of conditions; dynamic glazing is more attractive where solar exposure, glare control, and winter light preferences vary by geography and by driver habit.
The second is the premium-to-mainstream diffusion path common in European automotive markets. Features often appear first in luxury sedans, SUVs, and technology-led EVs, then migrate selectively into higher trims of volume brands once suppliers bring cost, switching speed, durability, and integration risk into a more acceptable range. Electrochromic roofs still lean premium, but the commercial question has changed. It is no longer whether the technology belongs only in halo vehicles. The question is where the value stack becomes defensible in broader segments.
The third factor is regulation around energy efficiency and visibility-related performance, even where there is no rule aimed specifically at electrochromic roofs. Europe’s policy environment keeps pushing automakers toward lower operating energy use, smarter thermal management, and material choices that support decarbonization narratives. A roof system that reduces reliance on physical blinds, supports HVAC load management in hot conditions, and aligns with lightweighting priorities gets attention even without a dedicated policy incentive.
The EV Interior Has Changed the Value Equation
Electrochromic adoption in Europe is tied closely to how EV cabins are being repositioned. In internal combustion vehicles, a sunroof was often a lifestyle option. In EVs, the glass roof increasingly supports a broader brand promise: open space, quietness, digital controls, and lounge-like comfort. That promise is easy to market but difficult to engineer cleanly. A large roof opening or fixed panoramic glass can affect body stiffness, acoustic behavior, and heat management. Mechanical sunshades solve part of the comfort issue, but they add packaging complexity and moving parts while doing little for the minimalist interior theme many EV brands now prefer.
This is where electrochromic systems have gained traction with product planners. They fit the software-centric story of the vehicle. They can be linked to ambient light sensors, occupancy logic, or thermal preconditioning. They also remove some of the visual clutter associated with conventional shade hardware. For European OEMs, especially those trying to distinguish upper trims without adding excessive mass or obvious ornamentation, that matters more than it did a decade ago.
Still, the business case is not automatic. A business evaluator should watch for whether the roof is being sold as a comfort enhancer alone or as part of a wider energy and cabin-control package. The latter is more durable. When electrochromic glazing is integrated into thermal strategy, HMI logic, and premium differentiation, it is harder to remove in future refresh cycles.
What Buyers Are Actually Rewarding
European end-user demand is not really centered on the chemistry of smart glass. Buyers respond to a bundle of outcomes: glare reduction without a closed-in feeling, lower heat build-up during summer parking, a cleaner interior ceiling design, and the sense that the vehicle adapts to context rather than asking the driver to manage everything manually. In higher-end segments, passengers increasingly expect the roof to behave like the rest of the digital cabin.
This is one reason fixed panoramic roofs have remained attractive despite well-known comfort concerns. People like the openness; they dislike the penalties when the system underperforms in direct sun or harsh temperature swings. Electrochromic roofs attempt to preserve the emotional upside while reducing the practical annoyances. That is a more credible demand story than the older assumption that smart glass sells mainly because it looks futuristic.
Fleet and leasing channels may also become more relevant than many suppliers expect. In Europe, residual value logic strongly influences option strategy. A feature that improves perceived premium quality and helps differentiate higher trims can matter if it supports stronger used-vehicle desirability, especially in EVs where cabin condition and thermal comfort are scrutinized. The residual value effect is not yet proven across the market, but it is a signal worth monitoring.
Supply Chain Reality: Promise Meets Industrial Discipline
The strongest restraint on wider adoption remains industrial, not conceptual. Electrochromic roof systems demand coordination across smart glazing materials, lamination, control electronics, sealing, roof module integration, and long-term reliability validation. European OEMs may welcome the feature, but they will not relax standards on durability, switching consistency, optical quality, or temperature performance. Any supplier pitch that treats the roof as a plug-in visual upgrade is likely to run into resistance.
Cost structure is another constraint. Energy prices, raw material volatility, and pressure on EV margins have made OEMs more selective about premium content. That does not eliminate demand for electrochromic roofs; it changes where demand appears. The near-term growth path is more likely to be concentrated in premium brands, high-spec electric crossovers, and flagship trims where the feature can replace other hardware or support a broader cabin-value narrative. Wider volume-market penetration depends on whether suppliers can simplify integration and improve yield without compromising optical performance.
For AEVS watchers, this is familiar territory. In exterior and vision systems, technologies rarely scale in Europe because of novelty alone. They scale when the engineering stack starts to converge: aerodynamic targets, NVH requirements, thermal behavior, electronics architecture, and manufacturing repeatability all need to line up. Electrochromic roofs are moving into that convergence phase, but not every program will clear it at the same speed.
Signals That Matter More Than Hype
For anyone assessing the market, a few signals are more useful than broad claims about “smart mobility.”
- Roof systems appearing in EV platforms where range messaging and cabin comfort are both central to positioning.
- Supplier partnerships that combine glazing, electronics, and roof-module expertise instead of treating them as separate procurement islands.
- OEM communications that frame smart roofs in terms of thermal management, user personalization, or digital cabin integration, not just visual drama.
- Evidence that physical sunshade content is being reduced or redesigned in upper trims to offset complexity and weight.
- Aftermarket restraint. If a feature remains tightly OEM-controlled, that usually indicates the technology is being treated as a structural and electronic system rather than a cosmetic accessory.
None of these signs alone proves rapid mass adoption. Together, they point to a market that is becoming more serious, less experimental, and more tied to platform-level decisions.
What Could Slow the Market
The main risks are not hard to identify. Durability under repeated cycling and varied European climates remains a credibility issue whenever OEMs consider multi-year warranty exposure. Switching speed and uniformity matter because premium users notice visual inconsistency immediately. So does haze, color neutrality, and the roof’s behavior at the edges of the glass area. If the user experience feels compromised, the technology loses its premium justification very quickly.
There is also a strategic risk: some OEMs may decide that improved low-emissivity coatings, better fixed-tint optimization, or advanced mechanical shading still offer a more predictable cost-performance ratio for mid-segment vehicles. In that case, electrochromic roofs would remain important but concentrated, rather than universal. That would still represent meaningful demand in Europe, just not the kind of adoption curve often implied in promotional material.
Where the Market Appears to Be Heading
The most reasonable outlook is measured expansion. Europe is likely to remain an influential market for electrochromic sunroof systems because it combines premium vehicle demand, strong EV penetration in several countries, persistent efficiency pressure, and customers who value cabin refinement. That does not guarantee scale across all segments. It does suggest that smart roof systems will increasingly be judged as part of the exterior-and-vision value chain, not as isolated comfort options.
For business evaluators, the real question is not whether interest exists. It clearly does. The more useful assessment is whether a supplier or OEM can connect the roof to three things at once: thermal and energy logic, premium user experience, and manufacturable system integration. Programs that achieve that balance are likely to shape the next wave of electrochromic sunroof Europe demand. Programs that rely on novelty alone probably will not hold their position for long.