
Industry Portal
Related News
- 00
0000-00
How to Specify Low-Pressure Casting Parts for Leak-Tight Automotive Housings - 00
0000-00
How to Specify an Electric Sunroof for Passenger Cars: Key Design and Safety Factors - 00
0000-00
North American Vehicle Aesthetics: Trends Shaping Exterior Design and Materials - 00
0000-00
ASPICE for Smart Optical Systems: Evidence Needed for Automotive Development - 00
0000-00
How to Select NVH Control Materials for Automotive Panels and Powertrain Systems
Tags
Panoramic Sunroof Lead Times Stretch to 14 Weeks
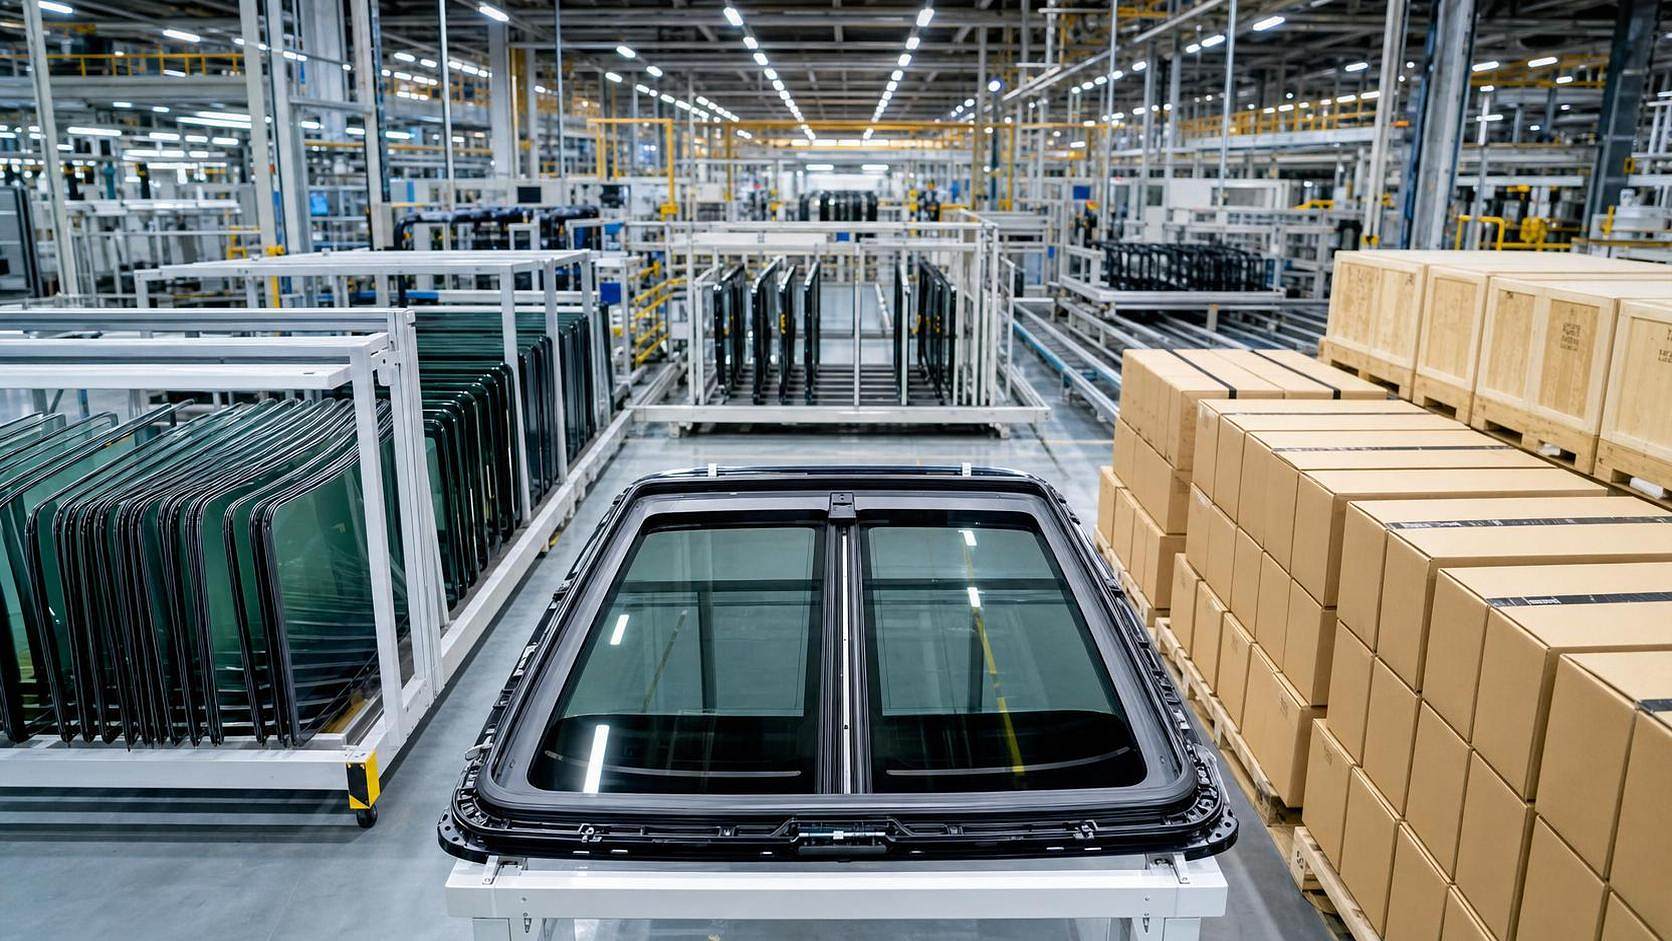
On 2026-06-15, feedback from multiple Chinese panoramic sunroof manufacturers indicated that average lead times for export orders to Europe had extended from 9 weeks to 14 weeks. The change is tied to tighter allocation of high-transparency low-iron glass substrates from AGC and the global prioritization of Henkel NVH damping adhesive for domestic automakers in Germany. For companies involved in export delivery, procurement coordination, production scheduling, and model launch planning, this is worth watching not as a routine logistics issue, but as a sign that supply-side allocation rules are directly affecting execution in the European vehicle program cycle.
What has been confirmed in the June delivery shift
According to the information provided, multiple Chinese manufacturers of panoramic sunroofs reported in mid-June 2026 that average delivery cycles for export orders to Europe had lengthened from 9 weeks to 14 weeks.
The stated reasons are twofold: tighter quota allocation for AGC high-transparency low-iron glass substrates, and Henkel NVH damping adhesive being globally prioritized for domestic automakers in Germany.
The reported impact has already reached production timing for premium-trim versions of several 2026 Q3 new vehicle models under BMW and Stellantis.
Where the pressure is likely to appear across the supply chain
Export delivery is no longer only a transport issue
For exporters of panoramic sunroof systems, the immediate effect is likely to appear in order confirmation, delivery commitment, and shipment planning. From an industry perspective, what deserves closer attention is whether contractual delivery windows, customer communication records, and schedule revisions are being managed with enough precision when upstream material allocation changes rather than physical transport disruption are driving the delay.
Procurement teams face a tighter material allocation environment
For procurement functions, the reported change points to pressure in two specific inputs: glass substrate availability and NVH adhesive access. Analysis shows that buyers may need to pay closer attention to supplier allocation notices, material availability statements, and any technical documentation tied to approved material use, because substitution or rescheduling in these categories can affect both timing and compliance review.
Manufacturing schedules may become more exposed to approved-material constraints
For processing and assembly manufacturers, the main risk is not only a longer inbound cycle but also the operational effect of waiting on materials that sit within product performance and specification control. Observably, if a production plan depends on designated glass substrate and NVH adhesive inputs, then workshop sequencing, final assembly timing, and shipment readiness may all be affected before the export stage itself.
OEM buyers and program teams may need earlier execution checks
For purchasing organizations and vehicle program teams, the reported impact on BMW and Stellantis model timing suggests that the issue reaches beyond supplier-level inconvenience. What deserves closer attention is whether sourcing plans, premium-trim configuration timing, and supply assurance reviews are being adjusted early enough when critical components are exposed to regional allocation priorities.
What companies should monitor now
Recheck material-linked compliance documents
Where orders depend on designated glass substrates or NVH adhesive systems, companies should closely review the status of technical files, approved material records, and any customer-facing documentation tied to the current bill of materials. Since no additional execution details were provided, this should be understood as a practical monitoring point rather than evidence of a confirmed compliance change.
Track how delivery commitments are being revised
Companies with European export exposure should pay attention to how revised lead times are reflected in quotations, order confirmations, shipping schedules, and downstream customer notices. Analysis shows that the commercial handling of a longer cycle can become as important as the physical delay itself when model launch timing is sensitive.
Watch supplier allocation language and priority rules
The reported tightening of AGC substrate quotas and Henkel priority support for domestic automakers makes supplier allocation language especially important. Businesses should monitor whether further clarifications emerge in supplier notices, commercial terms, or customer communications that change the practical order of supply access across regions or customer groups.
Prepare for tighter traceability around delayed programs
Where deliveries are linked to affected 2026 Q3 vehicle programs, companies should keep documentation on schedule changes, material arrival timing, and customer coordination complete and current. From an industry perspective, this is less about assuming a dispute and more about preserving traceability if delivery, quality, or after-sales questions later arise.
Why this looks more like an execution signal than a one-off delay
Analysis shows that this development is better understood as an execution signal from upstream allocation behavior rather than as an isolated late-shipment event. The key point is that supply priority and quota tightening at material level can directly alter export lead times for a finished automotive system.
At the same time, it is more appropriate to understand this as a developing market signal than as a fully defined rule change with complete public execution detail. Observably, the industry still needs to watch whether the current situation remains limited to specific materials and customer groups, or whether it begins to reshape broader delivery expectations, sourcing reviews, and customer documentation practices.
How the market may need to read this development
The practical significance of this event lies in the fact that a change in upstream supply allocation has already been reflected in export delivery cycles and in the production rhythm of named vehicle groups. That makes it relevant not only for sunroof manufacturers, but also for procurement, export operations, and OEM scheduling teams connected to Europe-bound programs.
Current evidence does not support broad conclusions beyond the reported facts. A neutral reading is that the market should treat this as a concrete delivery-side change with possible compliance, procurement, and execution implications, while continuing to verify how far the effect extends in actual business practice.
Basis of this article and points still requiring verification
This article is generated based on the user-provided news title, event date, and event summary. For events of this kind, commonly relevant source categories may include official announcements, regulator releases, customs or trade authority information, industry association updates, standard-setting documents, and reporting by authoritative media.
No specific official source link was provided in the input. For that reason, any subsequent assessment still requires continued verification against later supplier communications, customer execution notices, certification and specification interpretations, tender document changes, market feedback, and company-level implementation developments.