
Industry Portal
Related News
- 00
0000-00
Choosing Low Rolling Resistance Tires for Longer Mileage and Lower Fleet Fuel Costs - 00
0000-00
Rain Sensing Systems Calibration: Methods for Reliable Detection and Testing - 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects - 00
0000-00
Automatic Wipers for Buses: 7 Selection Criteria for Fleet Procurement - 00
0000-00
How Smart Optical Perception Prevents Collisions in Low-Light Driving Conditions
What Drives Raw Material Cost Fluctuations in Auto Parts Supply Chains?
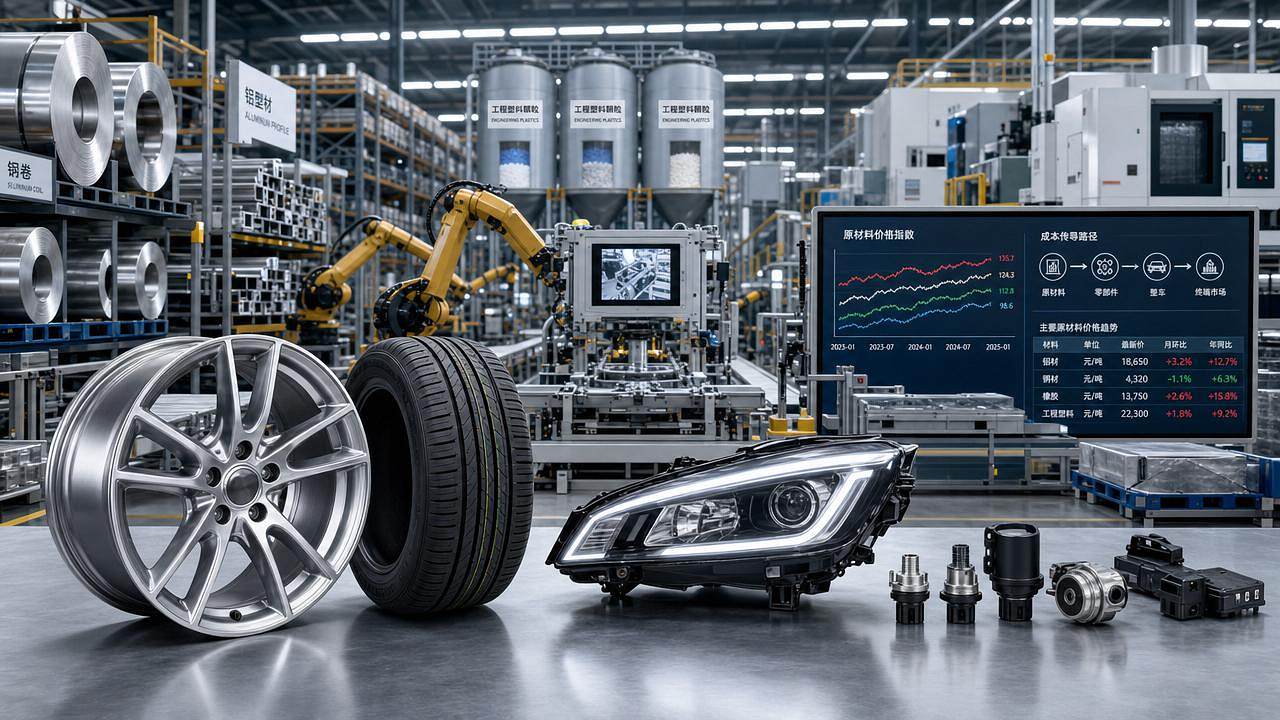
Raw material cost fluctuations are no longer a background issue in auto parts sourcing. They now shape approval speed, margin protection, supplier stability, and even long-term capital planning.
In automotive exterior and vision systems, the effect is even sharper. Aluminum alloy wheels, high-performance tires, LED headlight assemblies, electric sunroof systems, and auto sensor switches all sit close to volatile material markets.
That means one spike in aluminum, synthetic rubber, rare gases, engineering resin, or freight can quickly move total landed cost. What looks like a small commodity shift often becomes a major budget variance.
For AEVS-focused supply chains, the smarter question is not whether raw material cost fluctuations will happen. It is which signals matter first, and how to respond before pricing pressure reaches finished components.
Why raw material cost fluctuations hit auto parts so fast
Automotive parts combine metals, polymers, electronics, coatings, energy-intensive processing, and strict compliance rules. So cost movement rarely comes from one source alone.
In practice, raw material cost fluctuations often spread in layers. First comes commodity pricing, then energy, then supplier conversion cost, then transport, then certification or tooling adjustments.
- Track aluminum separately from finished wheel quotes. Smelting, billet conversion, scrap recovery, and forging energy all move at different speeds, so blended averages usually hide real exposure.
- Split rubber costs into natural, synthetic, and additives. Tire pricing reacts not only to latex markets, but also carbon black, silica, oil derivatives, and curing chemical volatility.
- Review electronics bills beyond chips alone. Headlight and sensor-switch costs also depend on resin housings, copper, adhesives, optics materials, and specialty gases used upstream.
- Check process sensitivity, not only material sensitivity. Low-pressure casting, precision forging, coating, vulcanization, and optical calibration can amplify raw material cost fluctuations through energy intensity.
- Compare spot-driven items with contract-driven items. Some suppliers pass through commodity shifts monthly, while others delay changes until quarter resets, creating misleading short-term stability.
- Ask for cost breakdown logic before approval. Without conversion, freight, compliance, and scrap ratios, a supplier price increase can look justified even when the commodity move was minor.
The biggest cost drivers worth watching first
Not every input deserves the same attention. The most useful approach is to rank drivers by volatility, spend share, and pass-through speed.
1. Aluminum and lightweighting pressure
Aluminum matters far beyond wheel programs. It also influences brackets, housings, structural reinforcements, and sunroof-related exterior components where lightweighting supports EV range.
At AEVS, this is especially relevant because exterior efficiency and aerodynamic performance depend on lightweight design choices. When aluminum prices jump, weight-saving strategies become more expensive to maintain.
2. Rubber and tire performance chemistry
High-performance tires are exposed to both commodity and formulation risk. EV torque, heavier curb weight, and demand for silence increase the use of premium compounds.
So raw material cost fluctuations in rubber markets do not stay isolated. They influence rolling resistance targets, wear life, and replacement pricing in both OE and aftermarket channels.
3. Energy-intensive conversion
A metal price chart alone never tells the full story. Smelting, forging, molding, coating, and thermal processing can add major cost volatility when electricity or gas markets tighten.
4. Logistics and compliance spillover
Freight, packaging, customs, and regulation updates can turn moderate material inflation into severe landed-cost pressure. This is common when ECE or DOT-related compliance changes require retesting or redesign.
Where approvals often go wrong
The biggest approval mistakes usually happen when teams review price requests too late or at the wrong level of detail.
A supplier may cite raw material cost fluctuations, but the real issue could be low yield, poor hedging, high regional power costs, or a sudden compliance burden.
- Do not approve based on benchmark headlines alone. LME or oil market movement helps, but component cost depends on grade, recovery rate, process route, and local sourcing reality.
- Challenge broad surcharge language in contracts. If escalation clauses lack timing, cap limits, or index references, raw material cost fluctuations become easy to overstate.
- Watch low-volume premium parts more closely. Matrix lighting modules and specialty exterior systems often have weaker scale leverage and faster cost pass-through than commodity parts.
- Separate temporary disruption from structural inflation. Port delays, regional energy shocks, or compliance updates may fade, but formulation shifts and decarbonization costs can persist.
- Check whether tooling assumptions changed quietly. A small material increase can be paired with revised tooling amortization, making total quote inflation look higher than expected.
- Review aftermarket pull-through risk. If replacement tire or forged wheel demand is surging, suppliers may prioritize higher-margin channels and tighten OE pricing flexibility.
Practical scenarios that change the decision
When aluminum rises but wheel pricing rises more
This often points to more than metal inflation. Energy-intensive forging, reject rates, machining wear, and export freight may be driving the extra spread.
A useful check is to compare the supplier’s metal index period with the quote period. Misaligned timing can exaggerate the impact of raw material cost fluctuations.
When tire costs stay high after rubber cools
That usually means the pressure moved downstream. Premium compounds, transport, mixing energy, or tighter performance standards may be offsetting softer raw material markets.
For EV-oriented tires, noise control and low rolling resistance targets can keep formulation costs elevated even when headline rubber prices settle.
When headlights and sensor switches become unexpectedly volatile
These parts are easy to underestimate because the bill of materials looks compact. In reality, optics, semiconductors, engineered plastics, coatings, and calibration create multiple exposure points.
AEVS intelligence is especially useful here because technical performance and compliance are tightly linked. A material substitution that lowers cost may also change heat behavior, glare control, or sensing reliability.
How to respond before margins get squeezed
The best response to raw material cost fluctuations is not one big policy. It is a set of small, repeatable controls built into sourcing, approval, and supplier review.
- Build a short exposure map by part family. Group sunroof systems, wheels, tires, headlights, and sensor switches by metal, polymer, energy, and compliance sensitivity.
- Use trigger bands for escalation reviews. Predefine what level of raw material cost fluctuations requires requoting, dual-source checks, or temporary volume reallocation.
- Request quarterly cost transparency from critical suppliers. A simple bridge showing material, conversion, freight, and compliance changes is often enough to improve approval quality.
- Align contract formulas with actual exposure. If resin or energy drives the part more than metal, avoid using a metal-heavy adjustment mechanism that distorts future pricing.
- Connect technical and commercial review earlier. AEVS-style intelligence works best when material trends, aerodynamic targets, optical performance, and regulatory updates are assessed together.
- Protect optionality in strategic categories. Even limited second-source readiness can reduce the pricing leverage created by sharp raw material cost fluctuations.
Why market intelligence matters more now
In the NEV era, exterior and vision systems are not simple trim items. They influence energy efficiency, safety perception, customer experience, and brand value.
That raises the cost of bad approvals. Cutting too hard can weaken performance. Approving too quickly can lock in avoidable inflation. Good decisions depend on current, technical, and commercially grounded intelligence.
This is where AEVS stands out. By tracking aluminum and rubber markets, ECE and DOT developments, thermal behavior in smart headlights, and airflow performance in low-drag wheels, it helps connect commodity shifts to real component outcomes.
What to review next
Start with the parts that combine high spend and fast pass-through. In most cases, that means wheels, tires, and selected lighting or sensor assemblies.
Then review whether current contracts explain raw material cost fluctuations clearly enough to support fast, evidence-based approvals. If they do not, the risk is already sitting inside future budgets.
A practical next step is simple: map the top cost drivers, test supplier assumptions, and use market intelligence to separate real inflation from weak pricing logic. That is usually where better margins begin.