
Industry Portal
Related News
- 00
0000-00
Which ISO Standards Govern Vehicle Lightweighting Materials and Validation Testing? - 00
0000-00
Wheel Lightweighting in Europe: How EV Regulations Are Reshaping Wheel Sourcing - 00
0000-00
How to Specify Low-Pressure Casting Parts for Leak-Tight Automotive Housings - 00
0000-00
How to Specify an Electric Sunroof for Passenger Cars: Key Design and Safety Factors - 00
0000-00
North American Vehicle Aesthetics: Trends Shaping Exterior Design and Materials
Tags
China’s NEV Penetration Hits 62.5%; Smart Lighting Exports Surge 142%
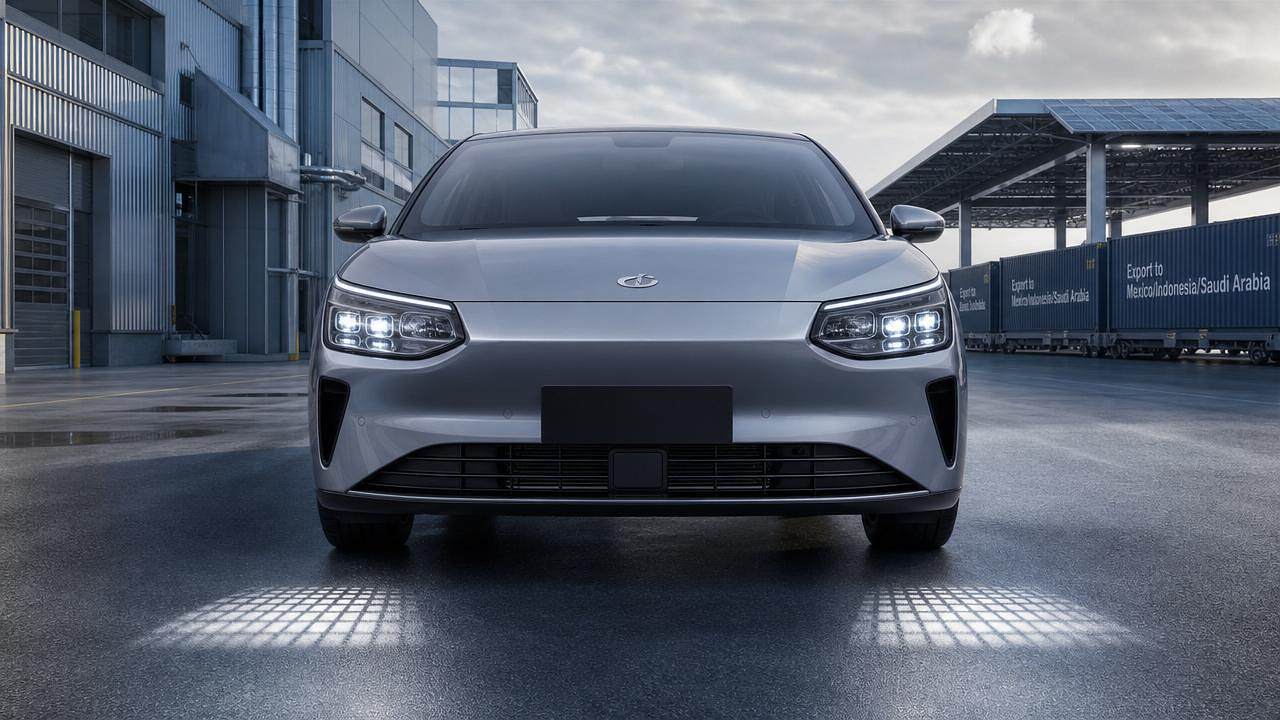
On May 29, 2026, the China Passenger Car Association (CPCA) released its latest monthly data showing that new energy vehicle (NEV) retail penetration in China reached 62.5% in May 2026 — a milestone reinforcing domestic electrification momentum and accelerating global demand for intelligent automotive lighting systems. This development directly impacts suppliers of matrix LED headlamps and adaptive driving beam (ADB) control modules, particularly those engaged in export-oriented manufacturing and international distribution.
Event Overview
According to official CPCA data published on May 29, 2026, the NEV retail penetration rate for passenger vehicles in China stood at 62.5% in May 2026. Concurrently, export orders for matrix LED systems featuring million-pixel projection capability and ADB control modules with over-the-air (OTA) upgrade support rose by 142% year-on-year. Primary destination markets include Mexico, Indonesia, and Saudi Arabia. Lead times for key suppliers have extended into Q4 2026.
Which Subsectors Are Affected?
Export-Oriented Automotive Component Manufacturers
These manufacturers face immediate capacity and scheduling pressure due to surging order volumes. The 142% YoY growth reflects not just volume expansion but also heightened technical requirements — including pixel-level beam shaping and OTA-compliant firmware architecture — which affect production planning, validation cycles, and certification readiness for target markets.
Automotive Electronics Supply Chain Integrators
Integrators responsible for sourcing, testing, and delivering complete ADB or matrix LED subsystems are impacted by extended lead times and intensified cross-border compliance coordination. The concentration of demand in three emerging markets implies divergent regulatory expectations (e.g., UN ECE R149 vs. GCC standards), requiring parallel adaptation efforts across logistics, documentation, and local homologation support.
Aftermarket & Distribution Networks Serving Emerging Markets
Distributors and regional service partners in Mexico, Indonesia, and Saudi Arabia are seeing accelerated uptake of high-spec lighting solutions — driven by both OEM fitment and retrofit demand. This affects inventory planning, technical training needs for local installers, and warranty claim workflows tied to software-defined functionality like OTA updates.
What Should Relevant Enterprises or Practitioners Monitor and Do Now?
Track regulatory alignment progress in priority markets
Current export growth is concentrated in jurisdictions where type-approval frameworks for software-upgradable lighting are still evolving. Enterprises should monitor official updates from national transport or standardization bodies in Mexico (SENER), Indonesia (Kemenperin), and Saudi Arabia (SASO) — especially regarding functional safety (ISO 26262) and cybersecurity (UNECE R155/R156) interpretations for ADB systems.
Assess capacity allocation for high-complexity variants
The 142% growth applies specifically to matrix LED systems with million-pixel projection and OTA-enabled ADB modules — not generic LED headlamps. Companies should differentiate production lines, test protocols, and firmware validation pipelines for these advanced variants versus baseline products, avoiding resource dilution across capability tiers.
Prepare for extended logistics and customs clearance timelines
With lead times already stretching to Q4, forward-looking procurement and shipping schedules must account for increased scrutiny at origin and destination ports — particularly for units containing embedded processors, wireless communication modules, or cryptographic firmware components. Pre-clearance documentation and dual-language technical files may reduce delays.
Validate interoperability and update management infrastructure
OTA-capable ADB modules require robust backend infrastructure for secure firmware delivery, version rollback, and diagnostic logging. Exporters should confirm compatibility with local telecom networks and cloud service providers in target markets — especially where national data residency or encryption regulations apply.
Editorial Perspective / Industry Observation
Observably, this data point signals a structural shift: NEV penetration is no longer solely a domestic policy metric but an export catalyst — one that amplifies demand for adjacent intelligent hardware with software-defined capabilities. Analysis shows the 142% export surge is less about broad-based market expansion and more about early adoption by OEMs and Tier 1s in specific growth corridors aligning with their own NEV rollout strategies. It is better understood as an early-stage signal — reflecting supply chain responsiveness to near-term OEM program launches — rather than evidence of mature, self-sustaining aftermarket demand. Continued monitoring is warranted, particularly around whether order growth sustains beyond Q3 or begins to diversify beyond the current three-market cluster.
Concluding, this development underscores how domestic electrification metrics increasingly serve as leading indicators for global component trade patterns — especially for intelligent subsystems where software integration elevates technical and regulatory complexity. It is more accurately interpreted as a near-term inflection in export order flow tied to specific product capabilities and regional OEM strategy, rather than a broad-based industry transformation already underway.
Source: China Passenger Car Association (CPCA), official May 2026 monthly report, published May 29, 2026.
Noted for ongoing observation: Sustained growth beyond Q3 2026 and geographic diversification beyond Mexico, Indonesia, and Saudi Arabia.