
Industry Portal
Related News
- 00
0000-00
Choosing Low Rolling Resistance Tires for Longer Mileage and Lower Fleet Fuel Costs - 00
0000-00
Rain Sensing Systems Calibration: Methods for Reliable Detection and Testing - 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects - 00
0000-00
Automatic Wipers for Buses: 7 Selection Criteria for Fleet Procurement - 00
0000-00
How Smart Optical Perception Prevents Collisions in Low-Light Driving Conditions
Rain Sensing Systems Europe: Key Market Shifts and OEM Demand Signals to Watch
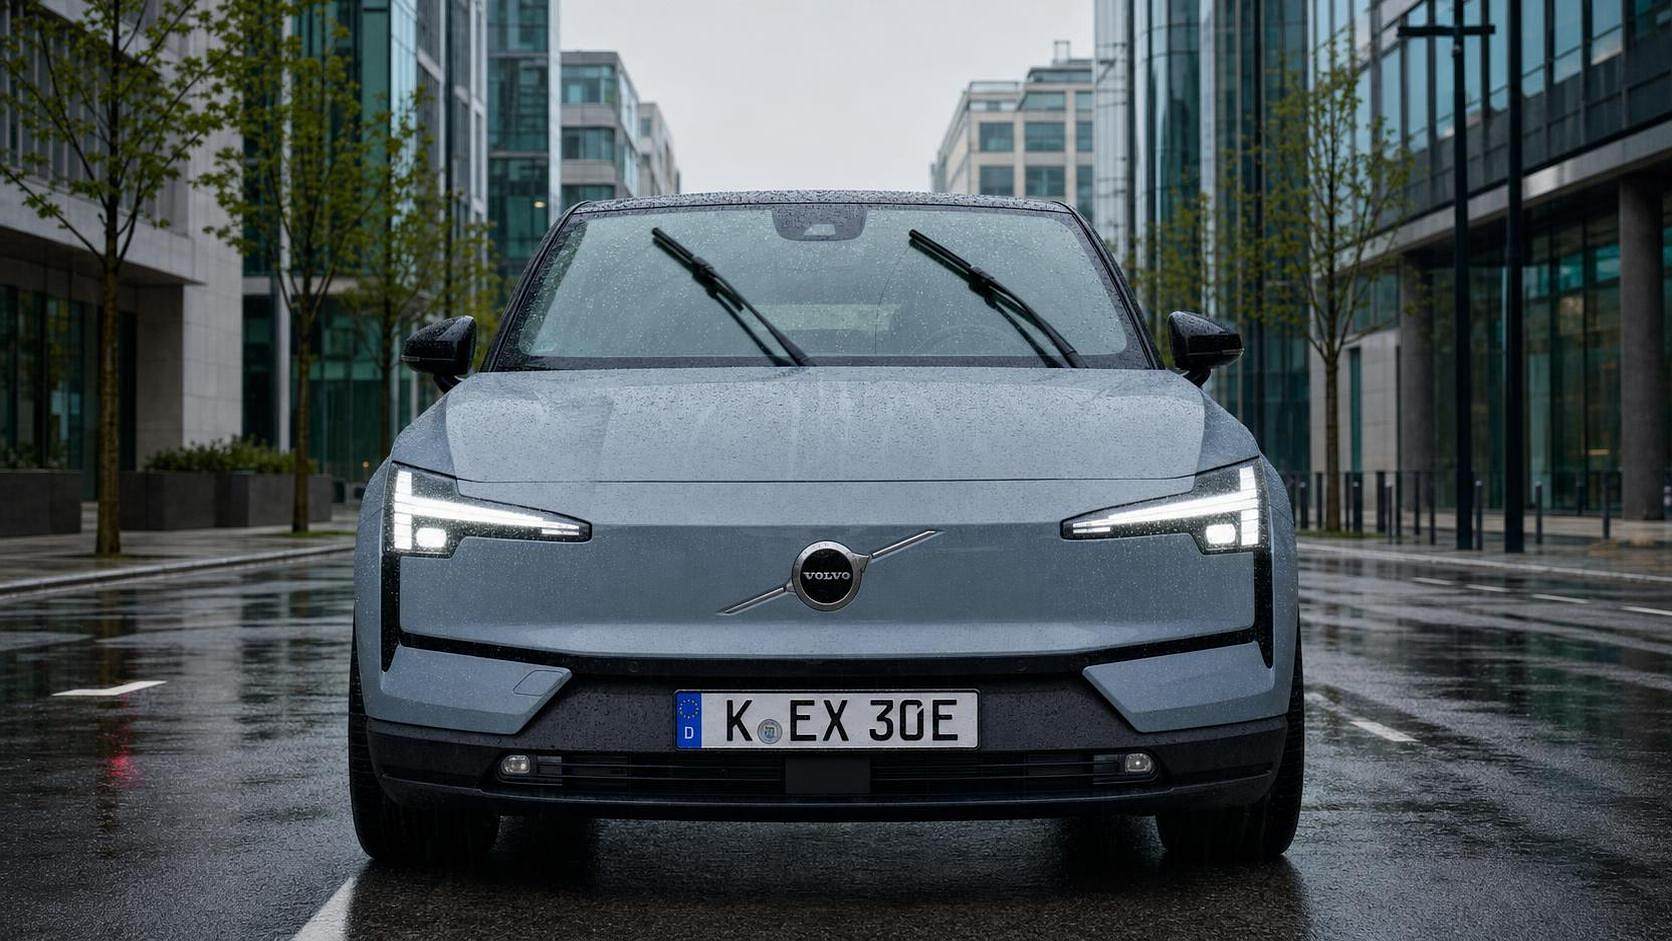
Rain sensing systems Europe has moved well beyond a convenience feature. It now sits at the intersection of safety compliance, windshield electronics, body control logic, and the premium perception that shapes modern vehicle programs.
That shift matters because European OEM planning is being reshaped by electrification, ADAS expansion, cost discipline, and tighter expectations around driver comfort. In this environment, rain sensing systems Europe offers useful demand signals for anyone tracking sourcing priorities, sensor integration pathways, and feature migration across vehicle segments.
For AEVS, this topic also fits a broader exterior and vision systems lens. Auto sensor switches, smart headlights, optical perception, and vehicle aesthetics increasingly work as one connected surface rather than isolated parts.
Why the category is gaining strategic weight
A rain sensor detects water on the windshield and triggers automatic wiper response. In older programs, that function was often treated as a small comfort upgrade. Today, it is tied to broader cockpit expectations and to the quality of human-machine interaction.
European buyers increasingly expect seamless automation in routine driving conditions. That includes auto wipers, automatic lighting, and sensor-driven exterior logic that reduces distraction without creating erratic behavior.
The category is also benefiting from architecture consolidation. OEMs are under pressure to reduce harness complexity, module count, and software fragmentation. That makes rain and light sensing more valuable when they can be integrated into shared optical or body electronics platforms.
In practice, rain sensing systems Europe is no longer just about detecting droplets. It is about calibration stability, clean signal processing, windshield compatibility, and smooth coordination with wiper motors, headlamp activation, and ADAS sensor visibility.
What is changing in the European market
Several market shifts are making the European landscape more decisive than it was a few years ago. The first is feature normalization. Automatic wipers are moving from upper trims toward wider fitment in compact and mid-range vehicles.
The second is platform pressure from battery electric vehicles. EV architectures push suppliers to deliver lower power consumption, lighter electronics packaging, and better software coordination across connected comfort and safety functions.
A third change comes from windshield complexity. Heated glass, acoustic layers, HUD requirements, camera zones, and advanced coatings can all affect sensor placement and optical reliability. That raises the technical threshold for suppliers.
The fourth shift is regional production strategy. European OEMs are balancing local sourcing resilience with cost competitiveness. As a result, supplier selection increasingly depends on manufacturing footprint, validation capability, and software support within Europe.
The demand signals worth watching
- Higher inclusion rates in B and C segment vehicles, especially in electrified platforms.
- Growth in combined rain-light-humidity sensing modules instead of single-function units.
- Greater OEM attention to false-trigger reduction in mixed weather conditions.
- More sourcing discussions tied to software tuning, not only hardware price.
- Closer alignment with windshield and mirror module suppliers during early development.
How rain sensing connects with exterior and vision systems
From an AEVS perspective, rain sensing systems Europe should be read as part of a larger exterior intelligence stack. The sensor may be small, but its commercial meaning expands when linked with adjacent systems.
Automatic wiper logic affects forward visibility. That directly supports the performance envelope of LED headlight systems, camera-based driver assistance, and the overall perception of vehicle refinement.
It also sits inside the wider family of auto sensor switches. These are the body network touchpoints that make exterior functions feel predictive rather than reactive. In competitive vehicle programs, that subtle difference matters.
This is why OEM evaluation is becoming more cross-functional. A rain sensor is assessed not only by component engineers, but also through software, optics, electronics, and user-experience criteria.
Where integration creates value
Where OEM sourcing priorities are shifting
The European sourcing conversation is becoming more selective. Price still matters, but the lowest-cost bid is less attractive when calibration drift, poor wet-weather behavior, or software instability creates warranty exposure.
OEMs are showing stronger interest in suppliers that can support multi-domain validation. That includes environmental testing, optical simulation, EMC performance, and compatibility with regional compliance frameworks.
Rain sensing systems Europe is also being influenced by trim strategy. Some brands want a scalable module family that can support entry, mainstream, and premium lines with minimal redesign.
Others are prioritizing common software layers across exterior electronics. In both cases, the preferred supplier is increasingly the one that offers stable tuning support and clear integration documentation.
Typical evaluation questions
- How consistent is sensor performance across windshield variants and climatic conditions?
- Can the module share architecture with light or humidity sensing functions?
- What software tuning support is available during vehicle integration?
- How mature is the supplier’s European production and aftersales support?
- Does the solution fit the OEM’s migration path toward centralized electronics?
Practical scenarios shaping demand
One clear scenario is the electric crossover segment. These vehicles often combine premium feature expectations with tight cost controls. That pushes rain sensing systems Europe toward modular designs that feel upscale without adding unnecessary hardware complexity.
A second scenario is premium sedans and SUVs with advanced windshield packaging. Here, sensing accuracy must coexist with acoustic glass, camera modules, and sophisticated lighting behavior. The component choice becomes part of the broader optics strategy.
A third scenario is fleet-oriented passenger vehicles. In these programs, durable operation and reduced maintenance events often matter more than marketing differentiation. Stable automatic wiping can still improve daily usability and perceived vehicle quality.
The aftermarket is less dominant than OEM fitment, but it still offers signals. Replacement demand, retrofit interest, and service failure patterns can reveal whether a technology is robust in real-world European weather cycles.
How to read the market more accurately
It helps to treat rain sensing systems Europe as a layered market rather than a single category. Hardware supply, software tuning, windshield interaction, and vehicle architecture all influence commercial outcomes.
A useful starting point is to separate visible demand from structural demand. Visible demand appears in feature lists and trim upgrades. Structural demand appears in sourcing platform decisions, electronics consolidation, and optical system roadmaps.
It is also worth comparing suppliers by integration burden, not just by quoted cost. A cheaper sensor can become expensive if it increases validation cycles or requires repeated calibration work.
This is where AEVS-style intelligence becomes relevant. When rain sensors are viewed alongside smart headlight evolution, auto sensor switch development, and NEV exterior architecture, the market picture becomes much clearer.
Key indicators to monitor next
- Feature penetration across new European EV launches.
- Adoption of combined sensing modules in body electronics platforms.
- Supplier wins linked to windshield electronics compatibility.
- Software-defined vehicle strategies affecting peripheral sensor design.
- Regional compliance and validation demands tied to visibility systems.
A grounded next step
The most useful next move is to build a comparison frame that connects sensing performance, integration effort, and platform relevance. That reveals far more than a basic component price review.
For current assessments, rain sensing systems Europe should be judged in relation to optical architecture, wiper control behavior, windshield design, and the broader exterior intelligence roadmap. That approach is more likely to surface durable supplier advantages and more realistic demand momentum.
As European vehicle programs continue to blend comfort automation with perception-driven safety, this category will stay a useful indicator of where OEM priorities are tightening and where integration-led value is beginning to outperform simple feature counting.