
Industry Portal
Related News
- 00
0000-00
ASPICE for Smart Optical Systems: Evidence Needed for Automotive Development - 00
0000-00
How to Select NVH Control Materials for Automotive Panels and Powertrain Systems - 00
0000-00
Choosing Low Rolling Resistance Tires for Longer Mileage and Lower Fleet Fuel Costs - 00
0000-00
Rain Sensing Systems Calibration: Methods for Reliable Detection and Testing - 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects
Scrap Aluminum Surge Pushes Wheel Export Quotes Higher
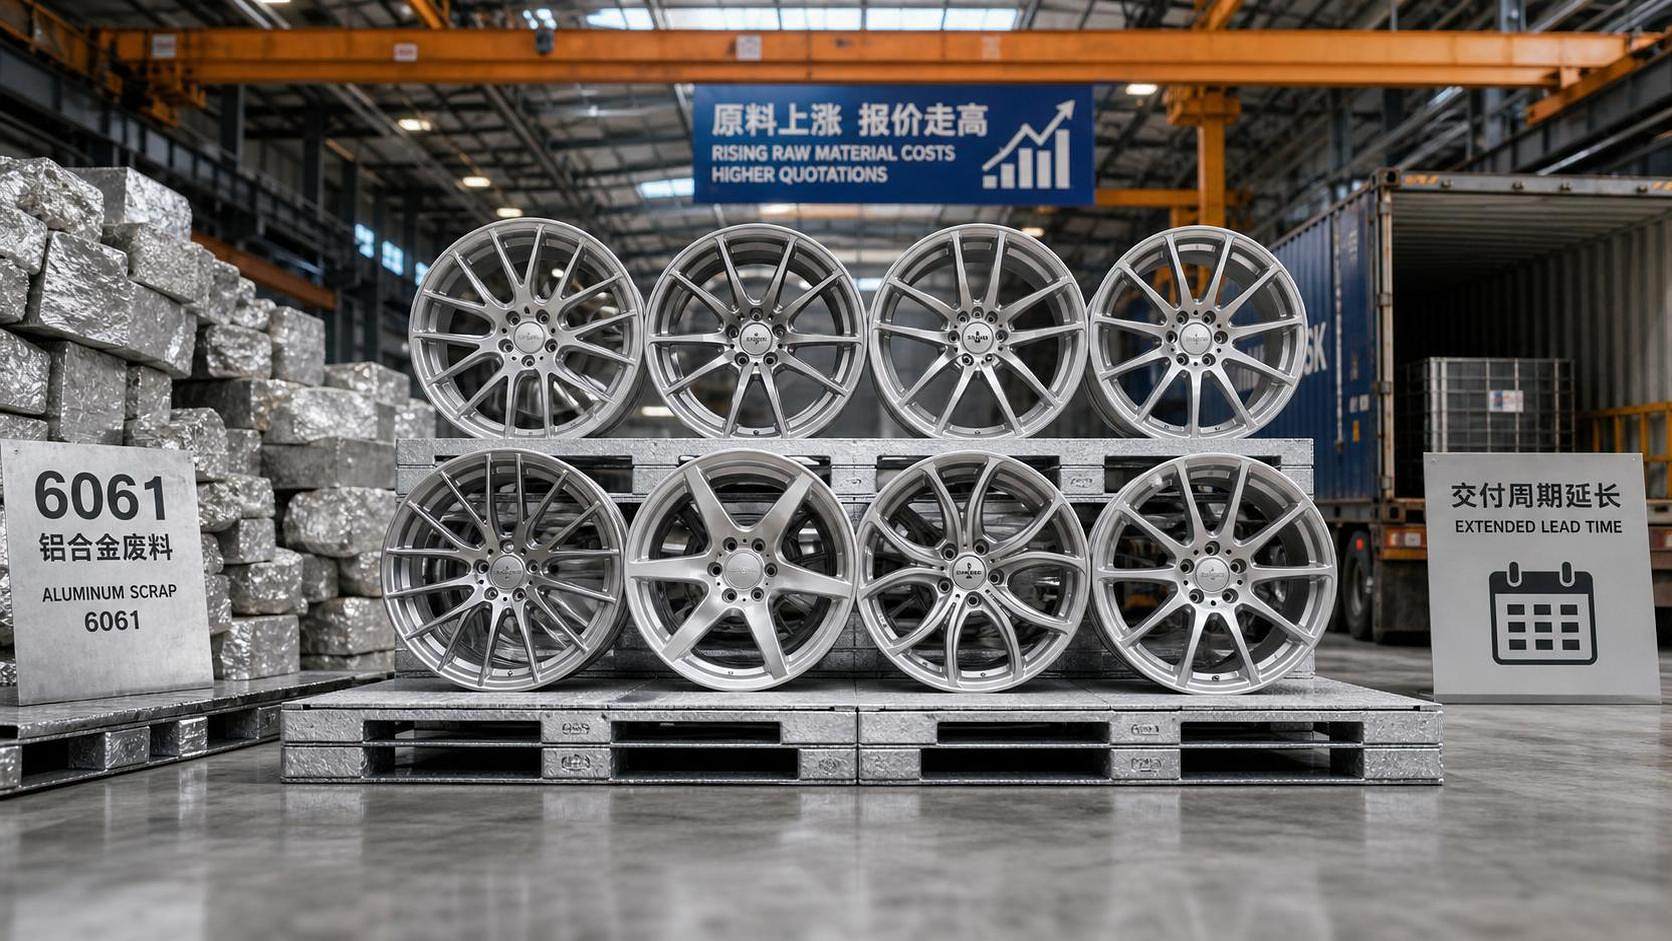
On July 10, 2026, a sharp increase in the spot price of 6061-series aluminum scrap became a direct market signal for forged lightweight wheels export trade. The latest pricing cited jointly by LME and Shanghai Metals Market shows a clear raw-material cost shift, and that shift is already being reflected in higher export quotations, longer delivery cycles, and renewed supplier comparison activity among some overseas buyers. For exporters, procurement teams, and supply-chain managers, the issue is no longer only price movement; it is also how quotation discipline, delivery commitments, and buyer-side sourcing rules may adjust in response.
What the confirmed market data shows
According to the information provided, the global spot average price for 6061-series aluminum scrap reached $2,840 per ton on July 10, 2026, up 18% month on month and marking the highest level since October 2025. Following that move, mainstream Chinese exporters of forged lightweight wheels raised export quotations by 12% to 15%. At the same time, lead times were extended to 14 to 18 weeks. The same information also indicates that some Tier 2 customers in Europe and the United States have started supplier comparison processes as they review alternatives.
Why this matters across trade and delivery decisions
Export quotations are becoming more rule-driven
From an industry perspective, exporters are likely to face tighter buyer scrutiny over how price adjustments are justified and documented. When raw-material costs move this quickly, quotation validity periods, revision clauses, and pricing assumptions become more important in export negotiations. The immediate impact is on contract discussions, offer management, and bid competitiveness rather than on marketing alone.
Procurement planning faces a shorter reaction window
For raw-material procurement and production planning teams, the confirmed rise in scrap prices and the extension of lead times point to pressure on ordering schedules. What deserves closer attention is whether existing procurement plans, delivery commitments, and production allocations still align with customer expectations. Even without a formal regulatory change stated in the input, buyer-side purchasing rules and internal approval requirements may become stricter when quotations move up and delivery becomes less predictable.
Buyers and supply-chain service providers may tighten review steps
For overseas buyers, distributors, and supply-chain service providers, the start of alternative supplier comparison by some Tier 2 customers suggests a shift in execution behavior. Observably, the pressure point is not limited to price. It can also affect supplier qualification review, quotation comparison methods, delivery-risk checks, and document consistency during sourcing. Where multiple suppliers are benchmarked, technical files, quality records, and shipment commitments may come under closer examination.
Where companies should focus now
Check how price revisions are supported in trade documents
Analysis shows that companies involved in export sales should pay close attention to quotation wording, validity terms, and any supporting cost explanations used in negotiations or tenders. The current information confirms higher quotations, but it does not establish a uniform market rule for how buyers will accept those increases. That means document control and internal approval logic matter more in the near term.
Reassess lead-time promises against current capacity
With lead times extending to 14 to 18 weeks, manufacturers and exporters should review whether promised shipment schedules, booking plans, and customer communication records remain realistic. This is particularly relevant where delivery timing is tied to tender conditions, supply agreements, or after-sales commitments. The prudent approach is to treat delivery representation as a compliance-sensitive issue rather than a routine scheduling matter.
Prepare for broader supplier comparison and qualification checks
Because some Tier 2 customers have already started comparing alternative suppliers, companies should be ready for more detailed review of supplier credentials, quality traceability materials, technical documentation, and response speed during RFQ or bid processes. The input does not confirm any new certification requirement, so this should be treated as a practical sourcing response to market pressure rather than a confirmed formal rule change.
Monitor whether buyer requirements begin to shift in execution
What deserves closer attention is whether pricing pressure leads to changes in tender language, sourcing thresholds, documentation requests, or delivery-risk allocation in actual transactions. At this stage, the information supports caution and monitoring, not a conclusion that a new uniform trade rule has already been imposed across the market.
How this signal should be understood
Analysis shows that this development is better understood as an execution signal emerging from raw-material cost pressure rather than as a standalone policy announcement. The most meaningful change visible now is behavioral: export prices are moving up, lead times are lengthening, and some buyers are widening their supplier review process. For the industry, that combination matters because it can influence how procurement rules, bid evaluations, and delivery assurances are applied in practice, even before any formal written requirement changes.
A practical reading of the current shift
At this stage, the event should be read as a live market adjustment with possible implications for trade discipline, sourcing review, and delivery management. It does not by itself confirm a new regulation, standard, or certification rule. More appropriately, it signals that companies dealing in forged lightweight wheels should prepare for stricter commercial review, more cautious procurement behavior, and closer attention to documentation and lead-time commitments while the market response continues to develop.
Source scope and points that still need verification
This article is generated based on the user-provided news title, event date, and event summary. For developments of this type, commonly relevant source categories may include official announcements, releases from regulatory bodies, customs or trade authorities, industry association updates, standard-setting documents, and reporting by authoritative market media. No specific official source link was provided in the input, so the underlying official references still require ongoing verification. It remains necessary to monitor whether later changes appear in buyer requirements, certification practices, tender documents, trade execution standards, industry feedback, or company-level implementation.