
Industry Portal
Related News
- 00
0000-00
Which ISO Standards Govern Vehicle Lightweighting Materials and Validation Testing? - 00
0000-00
Wheel Lightweighting in Europe: How EV Regulations Are Reshaping Wheel Sourcing - 00
0000-00
How to Specify Low-Pressure Casting Parts for Leak-Tight Automotive Housings - 00
0000-00
How to Specify an Electric Sunroof for Passenger Cars: Key Design and Safety Factors - 00
0000-00
North American Vehicle Aesthetics: Trends Shaping Exterior Design and Materials
Tags
Saudi Export Surge Eases Wheel Export Shipping Costs
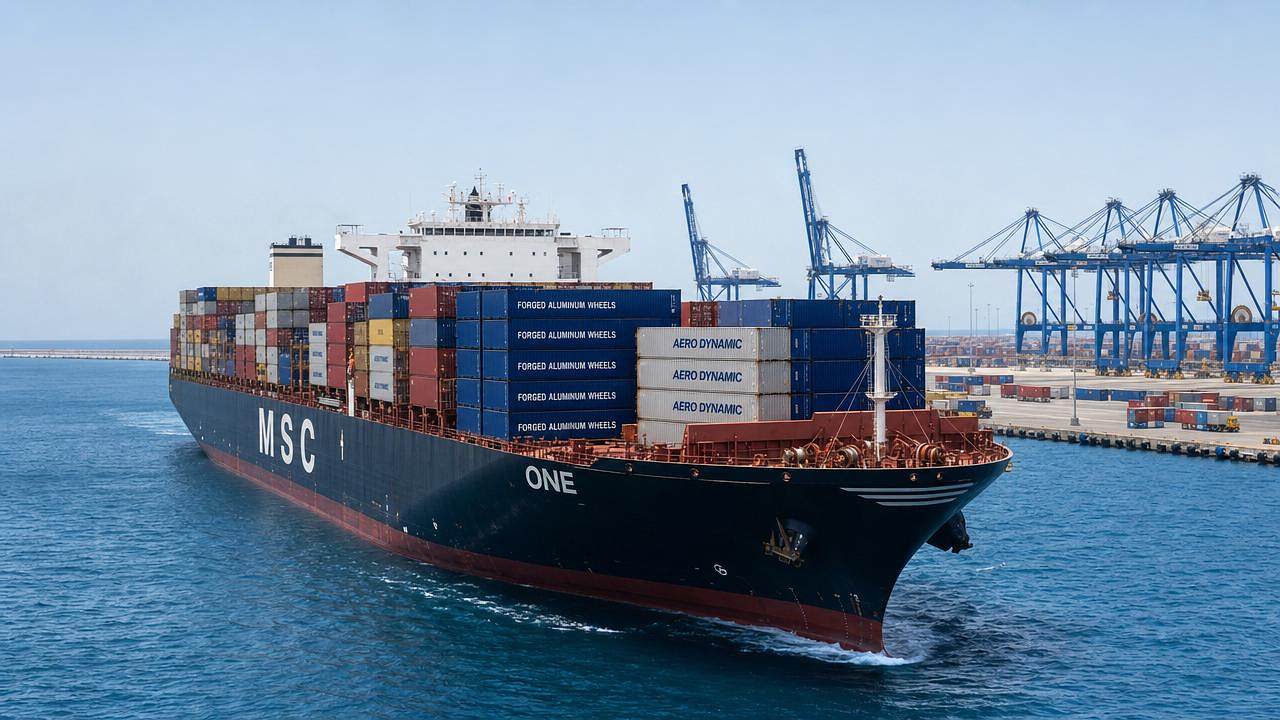
RIYADH, March 31, 2026 — Saudi Arabia’s March 2026 merchandise export growth—up 21.5% year-on-year, with petroleum exports surging 37.4%—has temporarily alleviated ocean freight cost pressure for forged and aerodynamic aluminum wheel exporters serving Middle Eastern, African, and South American markets. This development stems from strengthened port operational stability in the Red Sea region and prioritized container slot allocation on China–Saudi shipping lanes by the Saudi Ports Authority.
Event Overview
Saudi government data shows that total merchandise exports in March 2026 rose 21.5% year-on-year. Petroleum exports alone increased 37.4% in value. The resulting fiscal strength has supported sustained operations at Red Sea ports. Concurrently, the Saudi Ports Authority implemented preferential slot allocation for vessel capacity on direct China–Saudi maritime routes. As a result, several container shipping lines have reduced the 40HQ surcharge by 15% for shipments of forged lightweight wheels and aerodynamic/low-drag wheels destined for the Middle East, Africa, and South America.
Industries Affected
Direct Exporting Enterprises
Manufacturers and trading firms exporting forged aluminum wheels (e.g., forged lightweight wheels) and aerodynamic/low-drag wheels directly to emerging markets are experiencing measurable short-term relief in landed cost structure. The 15% reduction in 40HQ surcharges lowers per-unit logistics expenses, improving margin visibility for Q2 2026 shipments—particularly for orders booked under fixed-price contracts signed before March.
Raw Material Procurement Enterprises
Enterprises sourcing aluminum billets, high-grade alloys, or surface-treatment chemicals from Gulf-based suppliers may see improved lead time reliability and modest downward pressure on inland transport premiums. However, no change has been reported in raw material pricing or contract terms; the impact remains confined to logistical execution efficiency rather than input cost reduction.
Contract Manufacturing Enterprises
OEM and ODM wheel producers operating under consignment or toll-manufacturing arrangements benefit indirectly: stable Red Sea port throughput reduces demurrage risk and scheduling uncertainty for inbound raw material vessels and outbound finished goods. This enhances production planning accuracy but does not alter labor, energy, or overhead cost structures.
Supply Chain Service Providers
Freight forwarders and NVOCCs handling wheel-related cargo on China–Saudi–Africa corridors report higher booking conversion rates and reduced customer negotiation friction on surcharge clauses. Their service differentiation is shifting toward documentation agility and customs pre-clearance support—not rate arbitrage—as carrier-imposed 40HQ fee adjustments are now standardized across major alliances on this lane.
Key Considerations and Recommended Actions
Leverage Current Rate Stability for Contract Renewals
Exporters renewing Q3–Q4 2026 shipping contracts should lock in current 40HQ surcharge levels while they remain adjusted downward. Historical volatility suggests such reductions are unlikely to persist beyond mid-2026 without further fiscal or infrastructural reinforcement.
Reassess Port Pairing Strategy for Secondary Markets
Shippers targeting South America via transshipment should evaluate whether routing through Jeddah or Dammam (rather than Dubai or Jebel Ali) improves end-to-end transit time consistency—even if base ocean freight differs slightly—given Saudi ports’ newly prioritized slot access.
Monitor Red Sea Security Metrics Alongside Fiscal Indicators
While petroleum revenue supports port stability today, continued security incidents or prolonged insurance premium hikes in the Red Sea could offset gains. Stakeholders should track both Saudi fiscal balance updates and Lloyd’s Joint War Committee war risk zone designations concurrently.
Editorial Perspective / Industry Observation
This episode illustrates how macro-fiscal resilience in a key energy-exporting nation can create localized, time-bound supply chain tailwinds—even amid broader global freight uncertainty. Analysis shows the effect is neither structural nor scalable: it hinges on two temporary conditions—exceptional oil export performance and targeted infrastructure policy—not systemic maritime capacity expansion. Observably, similar relief has not emerged on other high-volume routes (e.g., China–Europe or China–US), underscoring the exceptional nature of this development. From an industry perspective, it is better understood as a tactical window than a strategic inflection point.
Conclusion
The March 2026 Saudi export surge offers tangible, near-term cost mitigation for aluminum wheel exporters reliant on Red Sea corridors—but its duration and replicability remain uncertain. A rational interpretation treats this as a favorable anomaly requiring active management, not a signal of broad-based freight market normalization. Long-term competitiveness still depends more on product differentiation, regional after-sales infrastructure, and tariff classification optimization than on transient shipping cost fluctuations.
Source Attribution
Data sourced from the Saudi General Authority for Statistics (GASTAT) and the Saudi Ports Authority (Mawani) public release dated March 31, 2026. Carrier-specific surcharge adjustments confirmed via statements issued by Hapag-Lloyd, MSC, and ONE between April 1–5, 2026. Continued monitoring is advised for: (1) Saudi monthly export data through May 2026; (2) updates to Mawani’s slot allocation framework; and (3) revisions to the UK P&I Club’s Red Sea risk advisories.