
Industry Portal
Related News
- 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects - 00
0000-00
Automatic Wipers for Buses: 7 Selection Criteria for Fleet Procurement - 00
0000-00
How Smart Optical Perception Prevents Collisions in Low-Light Driving Conditions - 00
0000-00
Private Label Tire Export: Evaluating Suppliers, Compliance, and Landed Cost - 00
0000-00
DOT-Compliant Truck Lighting: A Practical Guide to FMVSS 108 Requirements
Tags
Port Delays in Europe Pressure Forged Lightweight Wheel Supply
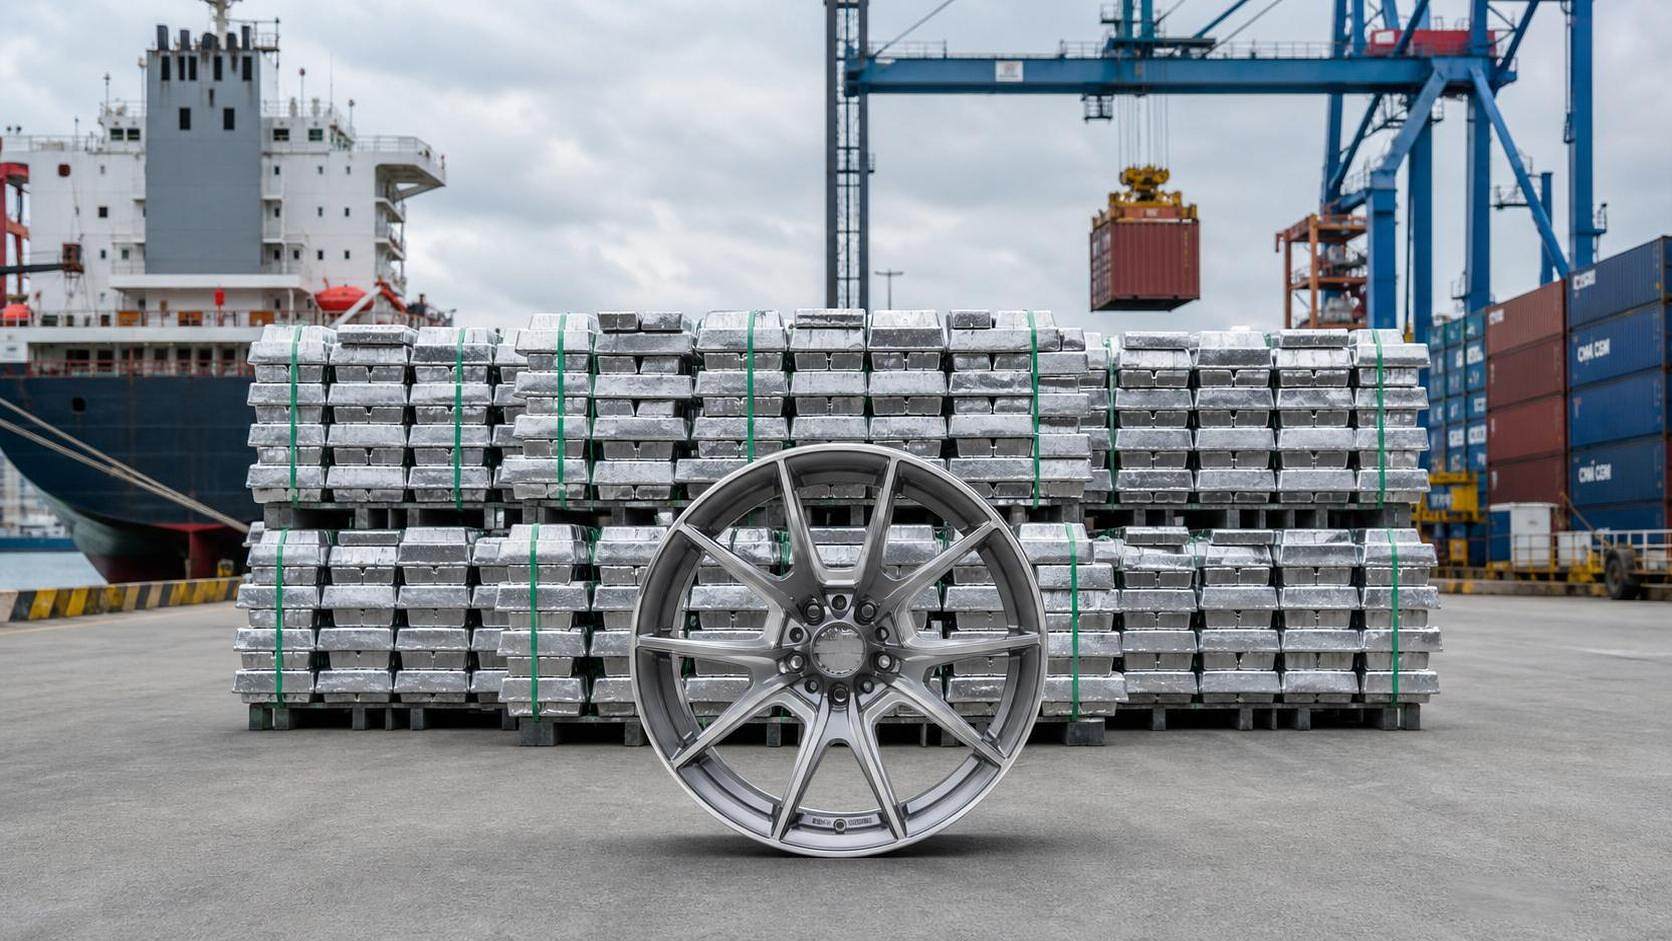
On June 22, 2026, aluminum ingot unloading delays at key European ports began to draw attention in the lightweight forged wheel supply chain. For suppliers and buyers linked to Aero/Low-drag Wheels and Forged Lightweight Wheels, the main issue is not only slower inbound material flow, but also longer delivery cycles and tighter export pricing pressure.
What is confirmed at the port and order level
According to the provided information, strike activity at Nordic ports and abnormal weather along the Baltic Sea route affected unloading schedules between June 22 and 24, 2026. Average unloading delays for aluminum ingots reached 9 to 14 days at Gothenburg in Sweden, Helsinki in Finland, and Hamburg in Germany. In parallel, domestic manufacturers of Aero/Low-drag Wheels and Forged Lightweight Wheels reported that June order lead times had generally extended to more than 12 weeks, while some premium forged wheel export quotations had been raised by 3.2%.
Where the pressure is likely to show up first
Inbound raw material flow
From an industry perspective, the first point of pressure is the arrival and unloading rhythm of aluminum ingots. For procurement teams, a 9–14 day delay at ports can quickly translate into disrupted inbound scheduling, especially when production depends on fixed material windows.
Forging and processing schedules
For manufacturing operations, longer raw material transit and unloading times can affect batch planning, furnace allocation, and downstream forging slots. What deserves closer attention is whether the 12-week-plus delivery cycle becomes a temporary adjustment or starts to reshape customer expectations for lead times.
Export quotations and customer commitments
For exporters, the reported 3.2% increase in some high-end forged wheel quotations suggests that pricing is beginning to reflect supply-side friction. That may affect quote validity, contract negotiation, and the timing of customer confirmations, especially where delivery dates are already tight.
What companies should watch now
Track port and logistics updates closely
Observably, the immediate variable is whether port disruption and weather-related delays continue beyond the reported period. Procurement and logistics teams should keep close watch on unloading progress, vessel timing, and any official updates that could change the current schedule.
Separate confirmed disruption from broader assumptions
It is more appropriate to treat this as a near-term supply disturbance rather than a finalized long-term shift. Companies should avoid assuming a permanent change in material availability unless further evidence confirms that the delays are persisting.
Review contracts and communication timing
For businesses handling forged lightweight wheel orders, the key operational focus is now on customer communication, delivery clauses, and internal handoff timing. When lead times are already above 12 weeks, even modest upstream delays can create contract and fulfillment pressure.
A short-term disruption, but one worth monitoring
Analysis shows that this development is best understood as a short-term but meaningful supply-chain signal for the forged lightweight wheel segment. It does not, by itself, prove a lasting structural change, but it does show how quickly port disruptions can flow through raw material logistics, production scheduling, and export pricing. For now, the more practical reading is to treat it as a condition requiring continued monitoring rather than a settled market outcome.
Source note and follow-up points
This article is based on the user-provided headline, event date, and event summary. Typical source types for verification in this kind of report would include official port notices, company announcements, industry association updates, authoritative media coverage, and standard-setting organization documents. No specific official source link was provided in the input, so the details should continue to be verified against later updates. The main follow-up point is whether the unloading delays and extended delivery cycles persist after the reported June 22–24 window.