
Industry Portal
Related News
- 00
0000-00
Which ISO Standards Govern Vehicle Lightweighting Materials and Validation Testing? - 00
0000-00
Wheel Lightweighting in Europe: How EV Regulations Are Reshaping Wheel Sourcing - 00
0000-00
How to Specify Low-Pressure Casting Parts for Leak-Tight Automotive Housings - 00
0000-00
How to Specify an Electric Sunroof for Passenger Cars: Key Design and Safety Factors - 00
0000-00
North American Vehicle Aesthetics: Trends Shaping Exterior Design and Materials
Tags
Low-Pressure Casting Still Wins in These Volume Wheel Programs
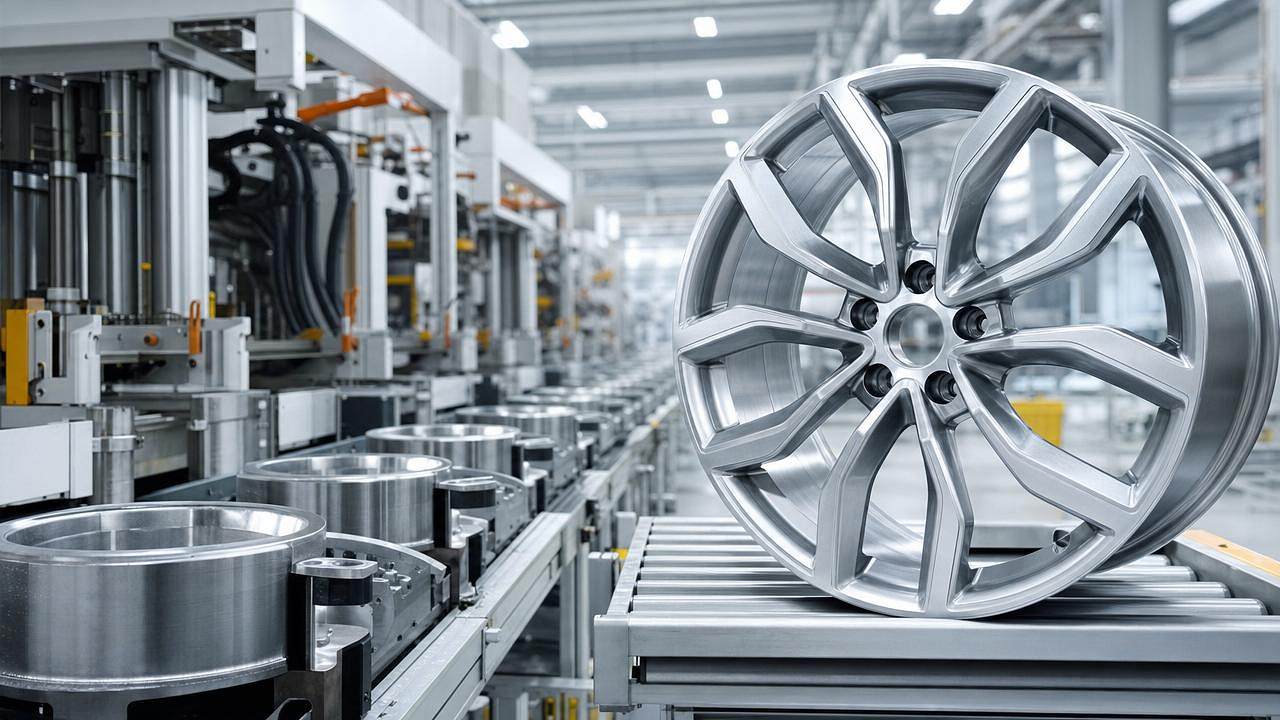
For business evaluators comparing wheel manufacturing routes, low-pressure casting remains a competitive choice in selected volume programs where cost stability, dimensional consistency, and proven performance matter most. As OEMs and suppliers balance lightweight targets, EV efficiency demands, and supply-chain risk, understanding why low-pressure casting still secures long-running wheel contracts is essential to making smarter sourcing and investment decisions.
Why the market signal is changing, not disappearing
In recent years, wheel sourcing conversations have shifted from a simple “lighter is always better” narrative to a broader evaluation of manufacturing resilience, program economics, compliance, and vehicle positioning. That change matters because it has reopened the case for low-pressure casting in a segment of wheel programs once expected to migrate rapidly to forged or more specialized flow-formed solutions.
The strongest signal is not that premium technologies are losing relevance. Rather, the market is separating into clearer use cases. On one side, high-performance EVs, luxury trims, and image-led variants continue to reward aggressive lightweighting and stronger differentiation. On the other, mainstream passenger vehicles, regional SUV lines, fleet-oriented programs, and long-cycle replacement demand still prioritize production consistency, manageable tooling economics, and dependable mechanical performance. In these cases, low-pressure casting keeps winning because it fits the total business equation, not just the engineering ideal.
For commercial evaluators, this is an important trend shift. Wheel manufacturing is no longer judged only by grams saved per wheel. It is increasingly judged by how well a process supports volume predictability, quality yield, logistics simplicity, launch timing, and multi-market homologation. Low-pressure casting aligns well with that expanded decision framework.
The forces keeping low-pressure casting relevant in volume wheel programs
Several industry forces explain why low-pressure casting remains durable in the current sourcing environment. None of them works in isolation; together, they create a practical advantage for selected wheel platforms.
The first driver is cost normalization. Aluminum prices, energy costs, transport volatility, and labor pressures have made procurement teams more skeptical of technologies that only deliver value under ideal market conditions. Low-pressure casting is attractive because it often provides a more balanced return in high-volume programs, especially when performance targets can be met without moving to a premium route.
The second driver is manufacturing confidence. In uncertain demand cycles, buyers prefer processes with established quality windows, known defect modes, and mature audit criteria. Low-pressure casting offers an advantage here because many OEMs, Tier 1 suppliers, and aftermarket participants already understand its operational behavior, making qualification and scaling less disruptive.
The third driver is platform diversity. Vehicle lineups are fragmenting into more trim levels, wheel diameters, and styling identities. That does not automatically favor the most advanced process. In many cases, it favors the process that can support multiple design families with reasonable investment, repeatable cycle times, and acceptable mechanical properties across regions.
Where low-pressure casting is still especially strong
The current market does not reward low-pressure casting equally in every wheel category. Its strength is concentrated in programs where business logic favors consistency over extremity. That includes mid-volume to high-volume passenger platforms, crossover and SUV lines needing robust impact performance, and wheel programs where design complexity is important but weight reduction targets remain commercially realistic.
This is particularly relevant in global NEV portfolios. While premium EV brands often highlight forged wheels or other lightweight solutions, a large share of electrified vehicles still competes on total ownership cost, range credibility, service durability, and broad market affordability. In that environment, low-pressure casting can support aerodynamic styling, brake package fitment, and durability needs without pushing wheel costs beyond acceptable thresholds.
Another strong application area is the long-life platform. Some vehicle programs remain in production, or in closely related facelifts, for several years. In such cases, low-pressure casting benefits from process familiarity, service parts continuity, and lower surprise risk in later production phases. Business evaluators tend to value this stability because wheel sourcing mistakes are expensive to correct once a platform is fully industrialized.
Why lightweighting alone no longer decides the winner
One of the biggest sourcing changes is the move away from single-metric thinking. Lightweighting still matters, especially for EV efficiency, unsprung mass, and handling. But the buying decision increasingly includes trade-offs among wheel mass, cost per kilogram saved, scrap sensitivity, finish quality, supply redundancy, and the likelihood of launch disruption.
In practical terms, business teams are asking better questions. Does a lower-mass wheel produce meaningful range or performance gains on this exact vehicle architecture? Will those gains be visible enough to justify a higher process cost? Can the supplier base support global production without bottlenecks? How does the manufacturing route perform under changing aluminum costs or regional freight shifts?
Low-pressure casting often performs well when judged through this broader lens. The process may not produce the absolute lightest wheel, but it can deliver a commercially efficient middle ground: better structural quality and dimensional control than simpler routes, with less cost and supply friction than more premium alternatives in many mainstream applications.
How the shift affects different decision-makers
The resurgence of interest in low-pressure casting does not affect all stakeholders in the same way. The business impact depends on each participant’s role in product planning, sourcing, engineering, and channel strategy.
For OEM buyers, the core impact is strategic flexibility. Low-pressure casting can broaden the shortlist of qualified suppliers and reduce dependence on narrower manufacturing ecosystems. For manufacturers, the impact is more operational: the process remains viable if they invest in quality control, mold management, simulation capability, and finishing consistency rather than assuming price alone will secure contracts.
For engineering teams, the signal is nuanced. They need to collaborate earlier with sourcing and finance so that wheel mass targets match the actual market intent of the vehicle. An over-specified wheel can erode program economics. An under-specified one can create warranty or brand perception issues. Low-pressure casting works best when those trade-offs are aligned upfront.
What business evaluators should examine before assuming a process shift
A common mistake in wheel program reviews is to assume that a more advanced process automatically improves commercial competitiveness. In reality, evaluators should test whether the full business case supports that move. Low-pressure casting should remain on the table when the vehicle’s value proposition is built around balanced efficiency, durable everyday performance, and manufacturing reliability.
The first checkpoint is target alignment. Is the wheel intended to maximize halo appeal, or to support a cost-sensitive global volume platform? The second is regional complexity. Will the part need cross-market compliance, multiple logistics hubs, or service support over a long lifecycle? The third is operational maturity. Does the supplier have evidence of stable yield, low field issue rates, and process repeatability at the required scale?
A fourth checkpoint is hidden cost exposure. A lower quoted price means little if the process creates more finishing variability, greater scrap sensitivity, slower ramp-up, or more engineering changes. Conversely, a premium process premium may be justified if the wheel materially strengthens vehicle efficiency, brand positioning, or launch differentiation. The evaluation should compare total program value, not only piece price.
The next signals worth watching
Looking ahead, the future of low-pressure casting will depend less on whether it is “old” or “new” technology and more on how effectively it adapts to changing wheel requirements. Business evaluators should watch five signals closely.
First, monitor EV wheel design evolution. If more mainstream EVs continue prioritizing aero-efficient wheel faces, larger diameters, and curb-impact durability, low-pressure casting may remain well placed in the core volume segment. Second, watch aluminum and energy cost volatility. Processes with predictable economics usually gain favor when input costs remain unstable.
Third, track quality digitalization. Suppliers that combine low-pressure casting with stronger simulation, defect monitoring, and data-driven process control will be better positioned to defend margins and quality claims. Fourth, observe regulatory and safety expectations. As OEMs face more scrutiny around durability, traceability, and lifecycle performance, mature processes with clear validation histories can become more attractive.
Fifth, keep an eye on aftermarket premiumization. Even as custom forged wheels grow in enthusiast and luxury niches, a large replacement market still values OE-like durability and broad fitment. That creates ongoing commercial space for low-pressure casting, especially when styling, finish quality, and supply availability are improved.
A practical judgment framework for the next sourcing cycle
For the next sourcing review, a practical framework is to sort wheel programs into three buckets: performance-critical, image-critical, and balance-critical. Performance-critical programs may justify moving beyond low-pressure casting if mass reduction delivers visible product value. Image-critical programs may choose premium routes when exclusivity and design storytelling matter most. Balance-critical programs are where low-pressure casting still has the strongest case, especially when annual volume, regional spread, and durability expectations are high.
That framework helps businesses avoid overgeneralization. The most effective decision is rarely to standardize one process across all wheel lines. It is to match the manufacturing route to the commercial mission of each vehicle and trim strategy. In many cases, low-pressure casting remains the most disciplined answer precisely because it supports the middle of the market so well.
Conclusion: why low-pressure casting still deserves a serious seat at the table
The current industry direction is not eliminating low-pressure casting. It is clarifying where it creates the most value. In volume wheel programs shaped by cost control, dependable quality, broad manufacturability, and realistic lightweighting targets, low-pressure casting continues to win because it solves multiple business constraints at once.
For business evaluators, the key takeaway is simple: do not judge low-pressure casting only against the most advanced technical benchmark. Judge it against program goals, lifecycle economics, supply-chain resilience, and the real commercial needs of the vehicle. If companies want to understand how this trend affects their own wheel sourcing strategy, they should confirm five questions now: Which vehicle lines truly benefit from premium lightweighting, where process risk is most costly, how much design flexibility is required, what regional supply options are available, and whether long-term profitability improves through process sophistication or through manufacturing stability.
Those answers will determine whether low-pressure casting is simply still relevant—or still the smartest choice.