
Industry Portal
Related News
- 00
0000-00
How to Specify Low-Pressure Casting Parts for Leak-Tight Automotive Housings - 00
0000-00
How to Specify an Electric Sunroof for Passenger Cars: Key Design and Safety Factors - 00
0000-00
North American Vehicle Aesthetics: Trends Shaping Exterior Design and Materials - 00
0000-00
ASPICE for Smart Optical Systems: Evidence Needed for Automotive Development - 00
0000-00
How to Select NVH Control Materials for Automotive Panels and Powertrain Systems
Tags
Global Aluminum Price Jumps 3.2%; Forged Wheel Lead Times Extend to 14 Weeks
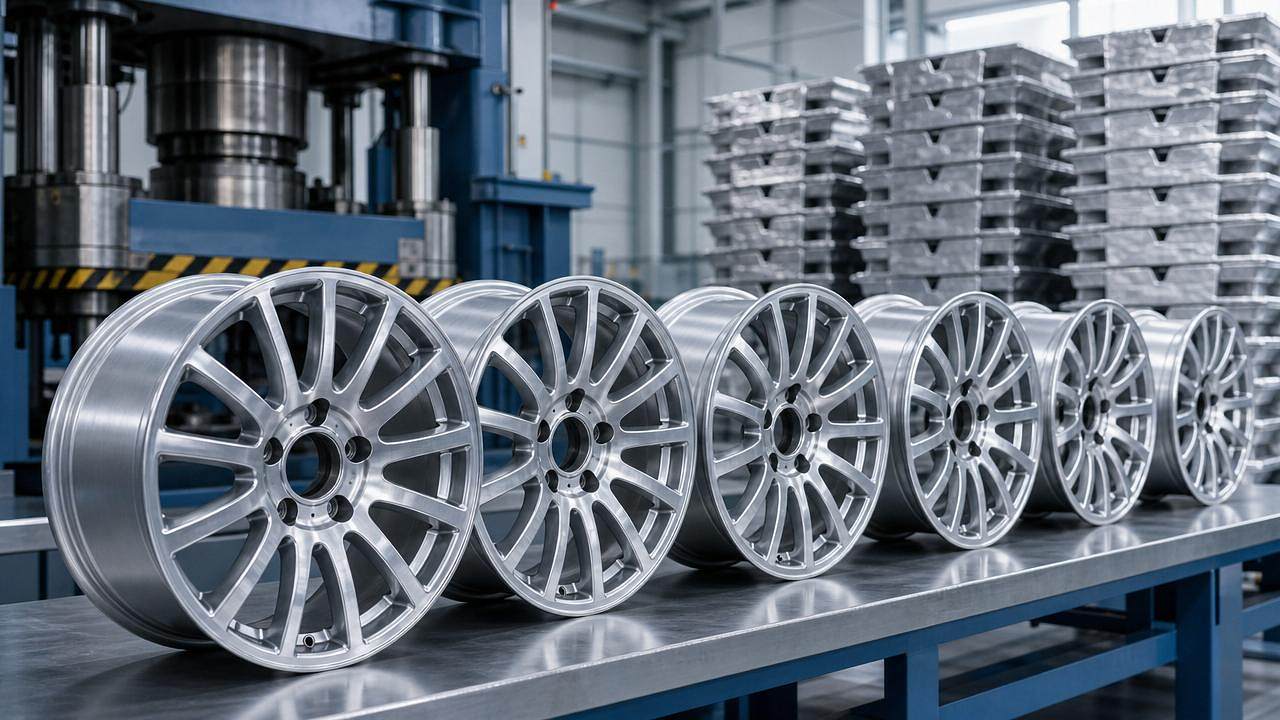
On May 22, 2026, LME aluminum surged 3.2% to USD 3,656 per ton, driven by spillover from LME copper’s breakout above USD 13,600/ton. This sharp move—combined with domestic power rationing and maintenance outages in China—is extending lead times for forged lightweight wheels, a critical component in high-performance automotive and EV applications. Suppliers have notified overseas customers that standard-specification forged wheel orders now face 14-week delivery windows (up from 10 weeks), with some custom configurations scheduled for delivery only by end-Q3 2026. Automotive OEMs, Tier 1 suppliers, and aftermarket distributors should monitor cost pass-through, capacity constraints, and procurement timing closely.
Event Overview
On May 22, 2026, the London Metal Exchange (LME) aluminum price rose 3.2% to USD 3,656 per ton. This followed LME copper exceeding USD 13,600 per ton, triggering broad-based metal price联动 (inter-metal correlation). As electrolytic aluminum is the primary raw material for forged lightweight wheels, rising input costs—compounded by electricity curtailments and scheduled maintenance at Chinese smelters—have prompted major suppliers to revise delivery commitments. Standard forged lightweight wheel orders are now quoted at 14-week lead times (previously 10 weeks); select custom models are booked through end-Q3 2026.
Industries Affected
Automotive OEMs and Tier 1 Suppliers
Forged lightweight wheels are increasingly specified in premium ICE vehicles and battery electric vehicles (BEVs) to reduce unsprung mass and improve energy efficiency. Extended lead times directly constrain new model launch schedules and production ramp-ups—especially for platforms targeting Q3–Q4 2026 deliveries. Cost inflation also pressures margin management amid ongoing platform-level cost negotiations.
Aftermarket Wheel Distributors and Retailers
Standard-spec forged wheels constitute a growing share of high-margin aftermarket offerings. A four-week lead-time extension compresses seasonal inventory planning cycles (e.g., spring launch windows) and increases working capital requirements for pre-positioned stock. Custom-order backlogs may also delay fulfillment for performance-oriented consumers, affecting brand reputation and repeat purchase rates.
Aluminum-Intensive Component Manufacturers
Firms producing other forged or extruded aluminum parts—including suspension knuckles, control arms, and EV battery housings—face parallel cost and capacity pressure. Though not explicitly cited in the notice, shared upstream constraints (e.g., billet availability, press capacity, energy supply) suggest potential spillover effects across non-wheel aluminum forging segments.
Global Procurement and Sourcing Teams
Procurement units managing multi-region supplier networks must reconcile divergent regional impacts: while Chinese smelter outages drive near-term tightness, LME price signals reflect global sentiment. This creates complexity in hedging strategy alignment, landed-cost modeling, and dual-sourcing feasibility assessments—particularly where alternative non-Chinese forged wheel capacity remains limited or unqualified.
Key Considerations and Practical Responses
Monitor official updates on Chinese industrial electricity policy
Current lead-time extensions cite domestic “power rationing and maintenance” as a contributing factor. Procurement and supply chain teams should track provincial-level energy dispatch notices and State Grid announcements—especially in Shandong, Inner Mongolia, and Yunnan—to assess duration and geographic scope of operational constraints.
Validate actual billet allocation—not just published lead times
Extended quoted lead times may reflect either genuine capacity exhaustion or strategic order queue management. Buyers should request written confirmation of billet booking status and press-line scheduling for specific SKUs, rather than relying solely on published delivery windows.
Reassess safety-stock thresholds for standard-spec wheels
With baseline lead time increased by 40%, safety-stock calculations for core SKUs warrant revision. Teams should simulate impact on minimum order quantities (MOQs), container load efficiency, and port storage fees—particularly for ocean freight lanes with extended transit durations.
Engage early on Q3 2026 custom specifications
Given confirmed bookings into late Q3 2026, engineering and purchasing teams developing custom finishes, offsets, or structural variants should initiate formal RFQs and technical sign-offs no later than mid-June 2026 to secure priority slotting.
Editorial Perspective / Industry Observation
Observably, this event functions less as an isolated price spike and more as a stress-test signal for aluminum-intensive advanced mobility supply chains. The linkage between LME copper momentum and aluminum pricing underscores how intermetal correlations can amplify volatility beyond fundamental supply-demand balances. Analysis shows the 14-week lead time reflects both real physical constraints (energy-driven smelter downtime) and anticipatory behavior among suppliers managing finite press capacity. From an industry standpoint, this is not yet a systemic shortage—but it is a clear indicator that marginal capacity in high-precision aluminum forging is nearing utilization limits under current energy and cost conditions. Continuous monitoring is warranted, particularly as Q3 typically brings seasonal demand upticks in both OEM and aftermarket channels.
Global aluminum price movements and associated lead-time adjustments remain highly sensitive to three variables: LME copper trajectory, Chinese provincial power dispatch decisions, and OEM order book revisions for 2026–2027 vehicle programs. These will determine whether current conditions consolidate into sustained tightness or ease in coming months.
The broader significance lies in the narrowing buffer between raw material cost volatility and finished-component delivery reliability—especially for technically demanding, low-volume, high-value components like forged wheels. This dynamic elevates the strategic importance of billet sourcing visibility, press-capacity pre-booking, and cross-supplier qualification protocols.
This development is best understood not as a short-term disruption, but as an inflection point highlighting structural dependencies in lightweighting supply chains. Current conditions favor proactive scenario planning over reactive firefighting—particularly for programs with Q4 2026 or Q1 2027 launch targets.
Source: Publicly reported LME price data (May 22, 2026); supplier notifications to international customers (dated May 22, 2026); referenced industry terminology and process definitions align with standard ISO/SAE classifications for forged aluminum wheels and related manufacturing practices. Note: Ongoing observation is recommended for updates on Chinese regional power policies and LME copper-aluminum spread behavior.