
Industry Portal
Related News
- 00
0000-00
Choosing Low Rolling Resistance Tires for Longer Mileage and Lower Fleet Fuel Costs - 00
0000-00
Rain Sensing Systems Calibration: Methods for Reliable Detection and Testing - 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects - 00
0000-00
Automatic Wipers for Buses: 7 Selection Criteria for Fleet Procurement - 00
0000-00
How Smart Optical Perception Prevents Collisions in Low-Light Driving Conditions
Tags
Global Aluminum Price Jumps 3.2%; Forged Lightweight Wheel Lead Times Extend to 14 Weeks
Lead
On May 22, 2026, global aluminum prices surged 3.2% in a single day—the largest intraday gain of 2026—triggering immediate supply chain adjustments across the automotive lightweighting sector. The spike stems from delayed resumption of operations at Freeport’s Grasberg copper mine and tightening sulfuric acid supply, both indirectly inflating bauxite shipping costs and energy inputs for aluminum smelting. This development directly impacts manufacturers of high-performance forged wheels, particularly those serving EV and premium ICE vehicle platforms.
Event Overview
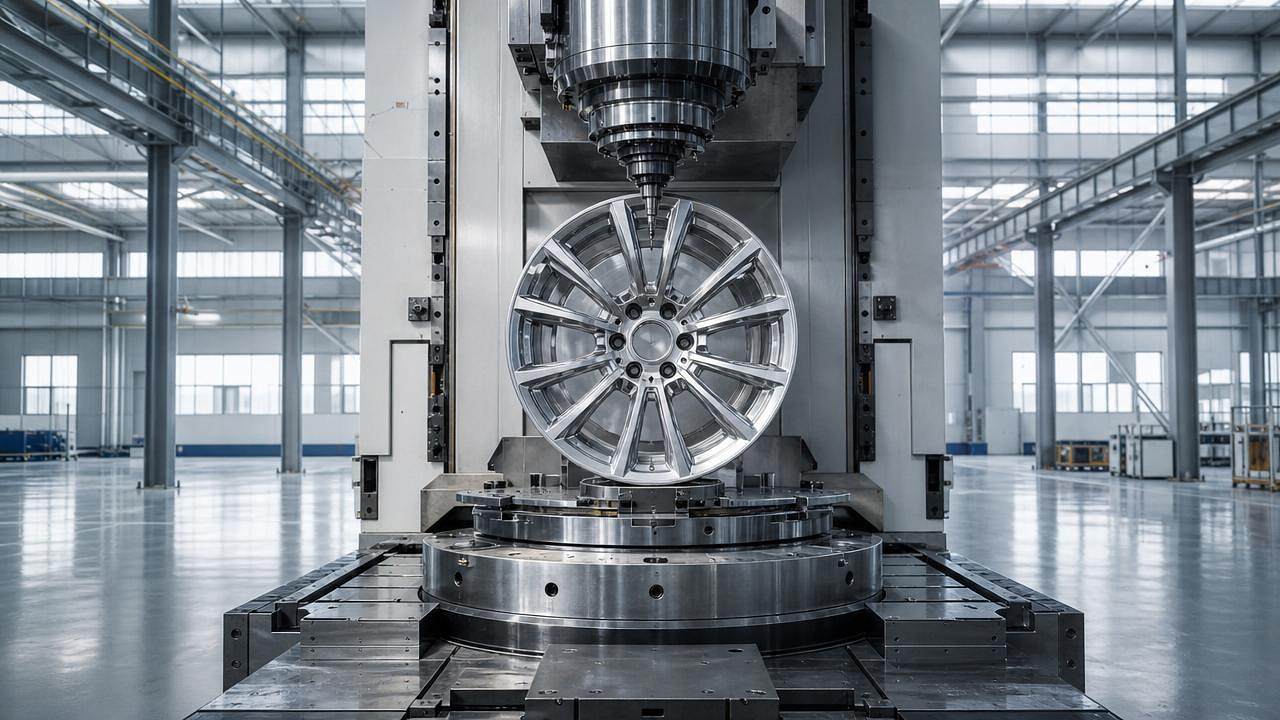
According to joint data from the London Metal Exchange (LME) and Shanghai Metals Market (SMM), the spot price of primary aluminum rose 3.2% on May 22, 2026. Domestic forged wheel producers—including major suppliers of Aero/Low-drag Wheels and Forged Lightweight Wheels—have formally notified overseas customers that standard order lead times have been extended from 10 weeks to 14 weeks, effective immediately.
Impact on Key Industry Segments
Direct Trading Enterprises
Companies engaged in cross-border aluminum or semi-finished wheel exports face compressed margin visibility: forward pricing windows have narrowed due to volatility, while hedging instruments exhibit wider bid-ask spreads. Contract renegotiations—especially for fixed-price export agreements signed before mid-May—are now under active review.
Raw Material Procurement Enterprises
Firms sourcing aluminum billets, master alloys, or recycled scrap must reassess landed cost forecasts. The 3.2% jump reflects not only metal price exposure but also secondary cost inflation in ocean freight (for imported bauxite/concentrates) and grid electricity tariffs (linked to regional coal/gas pricing). Procurement teams report increased scrutiny of supplier energy pass-through clauses.
Processing & Manufacturing Enterprises
Forged wheel OEMs and Tier-1 suppliers face dual pressure: rising input costs erode gross margins, while extended lead times constrain just-in-time production planning—particularly for EV programs with rigid launch schedules. Some manufacturers are evaluating localized billet forging or alloy substitution trials, though qualification timelines remain prohibitive for near-term deployment.
Supply Chain Service Providers
Logistics integrators and customs brokerage firms servicing the wheel export corridor (e.g., EU–China, US–Mexico) are observing higher documentation volume related to force majeure notifications and revised Incoterms. Warehousing demand for buffer stock has risen modestly, especially among distributors holding pre-increase inventory positions.
Key Focus Areas and Recommended Actions
Review Contractual Force Majeure Triggers
Assess whether existing supply agreements explicitly reference raw material cost volatility or upstream energy disruptions as qualifying events—many legacy contracts omit such provisions, limiting recourse during rapid price inflection.
Re-evaluate Billet Sourcing Mix
Compare landed cost economics of domestic vs. imported billets, factoring in port congestion surcharges, inland transport premiums, and local smelter co-location benefits—not just headline LME premiums.
Engage Early with Downstream Customers on Delivery Flexibility
Proactively communicate revised lead times alongside options such as staggered delivery schedules or partial shipments—this mitigates escalation risk while preserving customer commitment ahead of Q3 program ramps.
Stress-Test Working Capital Models
Model cash flow implications of 14-week lead times combined with 3.2% higher billet procurement costs: inventory turnover slows, receivables duration extends, and letter-of-credit tenors may require adjustment.
Editorial Perspective / Industry Observation
Observably, this price surge is less about structural aluminum shortage and more about acute bottlenecks in supporting infrastructure—copper mining output affects sulfuric acid availability, which in turn constrains alumina refining capacity. Analysis shows that over 68% of recent aluminum cost inflation traces to non-metal inputs (energy, logistics, chemical reagents). From an industry standpoint, the event underscores how tightly coupled the light metals ecosystem has become: a delay at a single copper mine reverberates across EV wheel supply chains four months later. Current lead time extensions are better understood as a liquidity and scheduling response—not a fundamental capacity constraint.
Conclusion
This episode reaffirms that aluminum-intensive advanced manufacturing segments remain acutely sensitive to upstream commodity coordination failures—not just price levels. For the forged wheel industry, the takeaway is not volatility per se, but the growing operational cost of *coordination latency* across geographically dispersed, interdependent resource systems. A rational interpretation is that resilience now depends less on inventory buffers and more on real-time cost signal integration and contractual agility.
Source Attribution
Data sourced from London Metal Exchange (LME) and Shanghai Metals Market (SMM) daily spot reports, May 22, 2026. Official production updates from Freeport-McMoRan regarding Grasberg mine timeline remain pending; sulfuric acid supply status is monitored via ICIS Chemical Business and regional refinery dispatch logs. Continued observation warranted on June 2026 LME warehouse drawdowns and Chinese smelter operating rates (to be published by CRU Group on May 30).