
Industry Portal
Related News
- 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects - 00
0000-00
Automatic Wipers for Buses: 7 Selection Criteria for Fleet Procurement - 00
0000-00
How Smart Optical Perception Prevents Collisions in Low-Light Driving Conditions - 00
0000-00
Private Label Tire Export: Evaluating Suppliers, Compliance, and Landed Cost - 00
0000-00
DOT-Compliant Truck Lighting: A Practical Guide to FMVSS 108 Requirements
Forged Wheel Shortage Deepens on Billet Price Spike
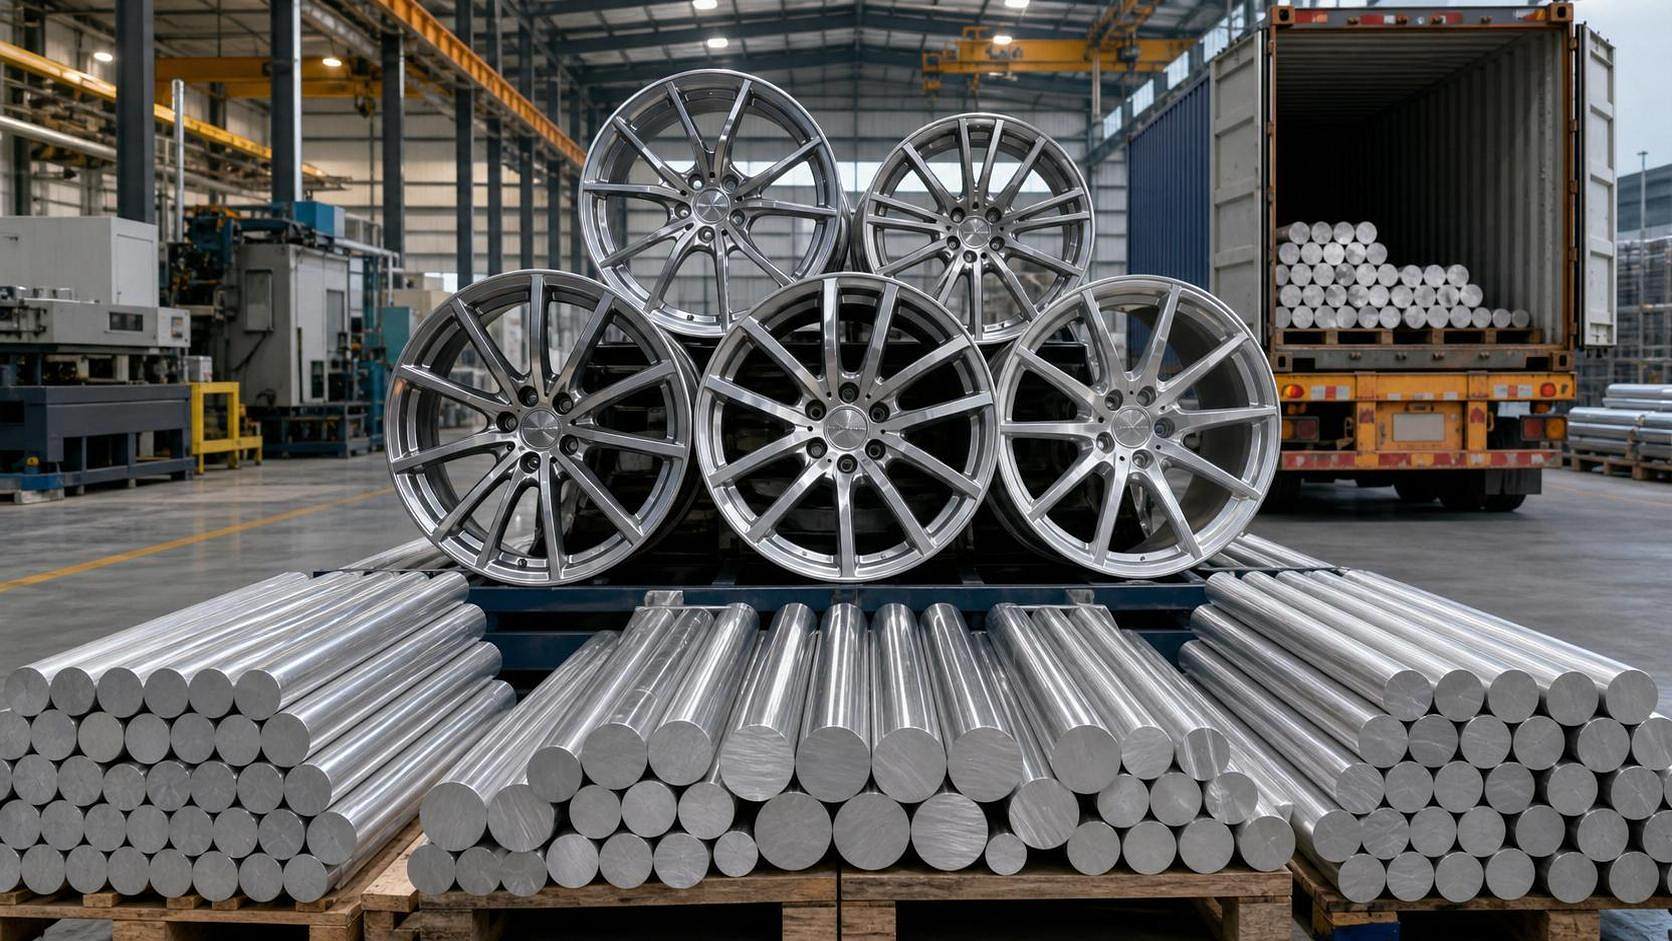
The timing of the underlying market shift is not clearly specified in the available input, but the latest referenced update points to a sharper squeeze in forged lightweight wheels as 6061-T6 aluminum billet prices rose strongly month on month and delivery cycles moved beyond 10 weeks. For importers, wheel buyers, manufacturers, and supply chain planners, this matters because the signal is not limited to raw material inflation alone; it also reflects tighter upstream processing capacity and rising competition for output linked to EV export demand.
What the latest market update confirms
According to CRU Group's 5 July 2026 metals report, global 6061-T6 aluminum billet prices increased 22% month on month to $3,890 per ton. The reported drivers were record EV export volumes from China, which were up 41% year on year in the first half of 2026, together with constrained billet refining capacity in Shandong and Jiangsu.
The same update indicates that lead times for forged lightweight wheels now exceed 10 weeks. It also states that premium-grade 22-inch wheel products are facing allocation. Importers were advised to secure Q4 allocations by mid-July.
Why different parts of the chain may feel this first
Pressure is building at the raw material buying stage
From an industry perspective, companies that buy billet or depend on billet-linked pricing may face the most immediate impact because the reported 22% month-on-month move changes purchasing cost assumptions quickly. The business effect is likely to appear first in quotation validity, procurement timing, and supplier negotiation windows.
Wheel producers are dealing with both cost and scheduling constraints
Analysis shows that forged lightweight wheel manufacturers may be affected on two fronts at the same time: higher billet input costs and longer fulfillment cycles. Where premium-grade 22-inch products are already under allocation, production planning and order prioritization may become more sensitive than in standard supply conditions.
Importers and distributors may face tighter allocation risk
Observably, the advisory to lock Q4 allocations by mid-July points to a near-term supply management issue rather than a purely theoretical price concern. For importers and channel operators, the main exposure may lie in whether supply can be reserved in time, on what terms, and for which specifications.
Downstream buyers may need to watch specification-level availability
For downstream application-side buyers, the shortage signal appears especially relevant where premium forged lightweight wheels are part of committed sourcing plans. What deserves closer attention is not only headline lead time, but whether specific sizes such as 22-inch variants become harder to obtain within required delivery windows.
Operational points that now deserve closer attention
Allocation timing is becoming a practical issue
Based on the provided update, importers should pay close attention to allocation timing for Q4 supply. The immediate issue is whether current discussions with suppliers are still within the advised booking window referenced in the market report.
Lead times need to be checked at the product level
Companies should not treat forged lightweight wheels as one uniform category in communication or planning. The reported allocation pressure on premium-grade 22-inch products suggests that product mix, grade, and size may matter materially in delivery expectations.
Supplier communication should focus on fulfillment conditions
Analysis shows that current supplier conversations should center on confirmed lead times, allocation status, and delivery commitments rather than price alone. Where procurement decisions are still open, the operational question is whether the supplier can actually secure tonnage or wheel capacity against the requested quarter.
Customer-facing teams may need earlier schedule alignment
For sales, account, and delivery teams, the longer lead-time environment may require earlier communication with customers around timing and availability. This is especially relevant where orders involve premium forged wheel specifications that could be affected by allocation.
How this should be read at this stage
Observably, this update is best read as a combined supply-and-demand stress signal rather than a standalone commodity price story. Analysis shows that the reported move in billet prices, the refining bottleneck in Shandong and Jiangsu, and the extension of wheel lead times are all pointing in the same direction: the market is under immediate strain.
At the same time, it is more appropriate to understand this as an active industry development that still requires continued observation, not as a final long-term conclusion. The current input confirms tightening conditions and allocation pressure, but it does not by itself establish how long those conditions will persist or how broadly they will spread across specifications and regions.
What this means for the market now
The clearest industry takeaway is that forged lightweight wheel supply is being affected by upstream aluminum billet pricing and capacity constraints at the same time that EV export demand is pulling harder on the system. In practical terms, this is more appropriately understood as a near-term supply chain warning with wider relevance for procurement, delivery planning, and customer commitments.
A neutral reading is that the shortage signal is already concrete enough to affect commercial decisions, especially for importers and buyers with Q4 requirements, while the broader duration and depth of the disruption still need to be monitored.
Source basis and verification note
This article is based on the user-provided news title, the note that the event timing was not clearly specified, and the supplied event summary referencing CRU Group's 5 July 2026 metals report. For this type of industry development, source categories that are usually relevant include official company statements, industry association updates, authoritative media coverage, and market or standards-related publications.
No specific official source link was provided in the input, so the underlying details should continue to be verified against subsequent primary or authoritative market updates. Areas that warrant ongoing attention include whether billet refining constraints ease, whether lead times remain above 10 weeks, and whether allocation pressure expands beyond premium-grade 22-inch forged wheel products.