
Industry Portal
Related News
- 00
0000-00
ASPICE for Smart Optical Systems: Evidence Needed for Automotive Development - 00
0000-00
How to Select NVH Control Materials for Automotive Panels and Powertrain Systems - 00
0000-00
Choosing Low Rolling Resistance Tires for Longer Mileage and Lower Fleet Fuel Costs - 00
0000-00
Rain Sensing Systems Calibration: Methods for Reliable Detection and Testing - 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects
Forged Wheel Prices Rise on 7075 Billet Shortage
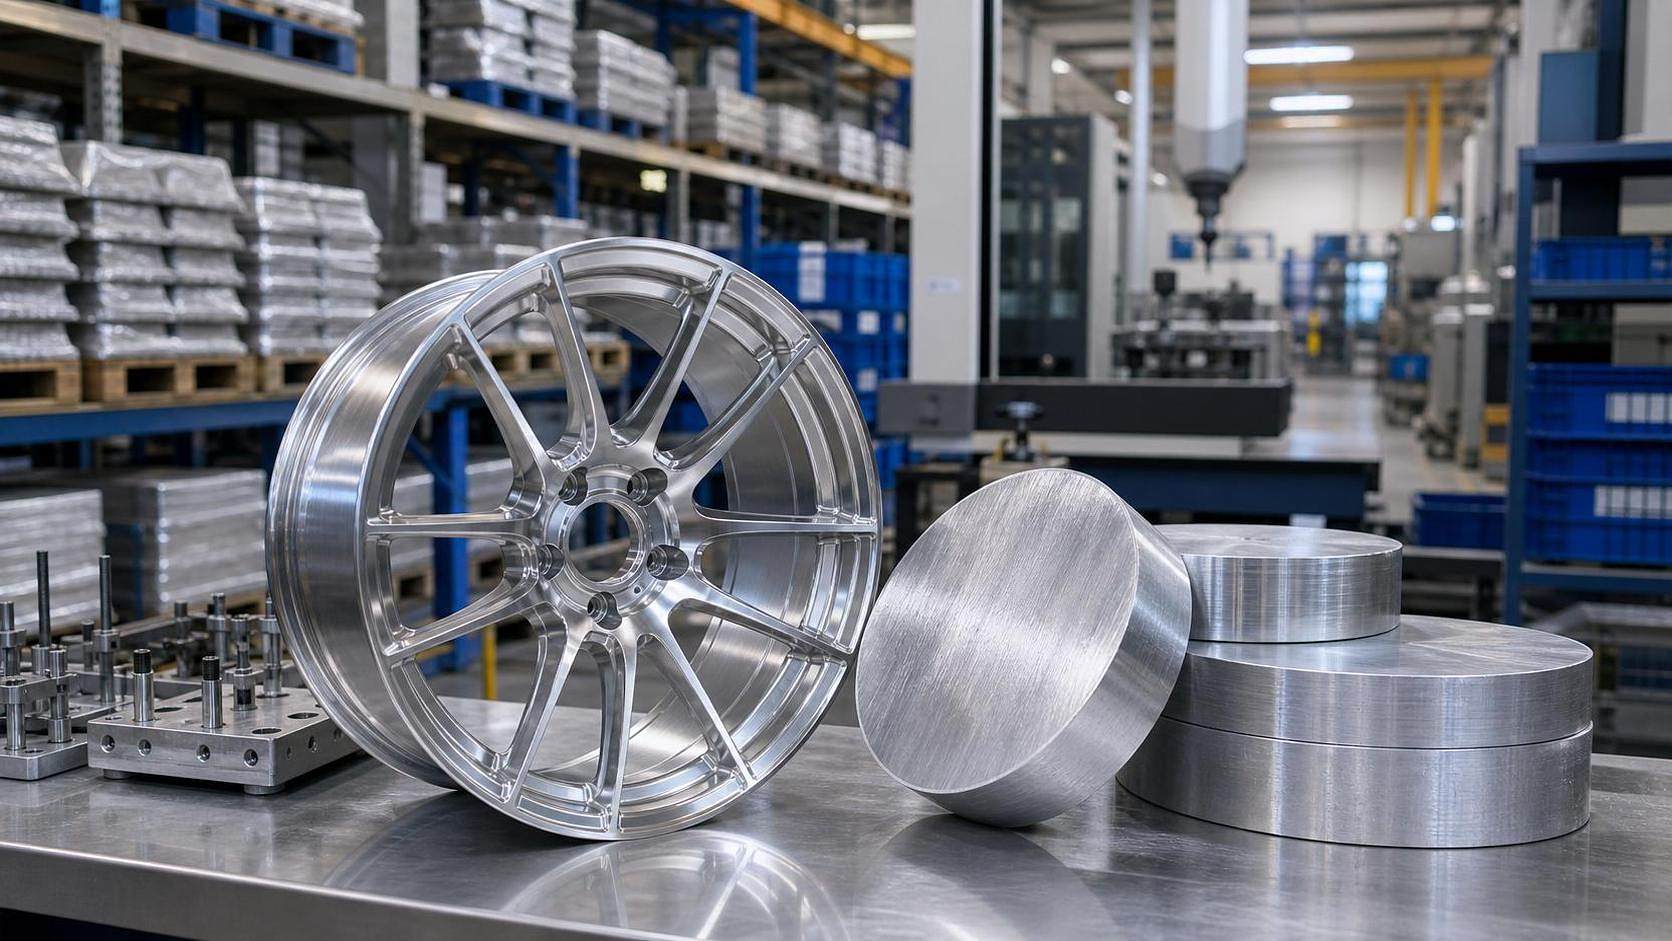
On July 12, 2026, newly released Aluminum Association data pointed to a sharp change in the supply conditions governing 7075-grade forged billet, with spot prices rising 22% month on month to $4,820 per ton. For the forged lightweight wheel segment, this is not only a raw-material cost issue but also a practical signal for procurement terms, specification control, delivery commitments, and contract execution, particularly where EV applications require wheels meeting at least 600 MPa UTS and custom orders are already moving into longer lead-time windows.
What the confirmed market update shows
The confirmed information is limited but clear. Aluminum Association data released on 2026-07-12 shows that global 7075-grade forged billet spot prices increased 22% month on month to $4,820 per ton. The stated causes were constrained supply from EU smelters and a delayed restart of Norwegian hydro-power plants. The same update indicates that forged lightweight wheels are seeing immediate price increases, with the effect described as especially relevant for EV applications requiring at least 600 MPa UTS. For custom specifications, lead times have stretched to 16 to 20 weeks.
Where the pressure is likely to appear across business flows
Procurement and direct trading are moving first
From an industry perspective, traders and procurement teams are the first to feel the impact because the reported change is tied directly to billet availability and spot pricing. The immediate business effect is likely to appear in quotation validity, raw-material cost pass-through, and supplier confirmation timing. What deserves closer attention is whether existing purchase terms, technical attachments, and delivery clauses are still workable under a market where custom forged inputs are taking significantly longer to secure.
Manufacturers of forged lightweight wheels face tighter specification risk
Analysis shows that wheel manufacturers, especially those serving EV programs requiring at least 600 MPa UTS, may face a narrower operating margin between material availability and specification compliance. The issue is not only higher input cost. It also touches production scheduling, custom-spec order acceptance, and the ability to maintain agreed technical performance without disruption. Companies in this position should pay close attention to how material grade references, mechanical-property requirements, and delivery commitments are written into contracts, technical files, and bid documents.
Buyers and project owners may need to revisit delivery assumptions
Observably, downstream buyers are exposed through longer lead times rather than through billet procurement itself. Where custom wheels are involved, a 16 to 20 week lead-time range can affect sourcing calendars, approval timelines, and acceptance planning. In practice, buyers should review whether tender schedules, model launch timing, or replenishment assumptions still match actual supply conditions, particularly for orders tied to custom specifications.
Certification, testing, and traceability functions may see more scrutiny
Although the update does not announce a new certification rule, the market change has compliance implications. Where products are sold against defined strength thresholds or customer-specific technical requirements, certification-related teams, testing bodies, and quality functions may need to confirm that any sourcing adjustment or delivery change does not create gaps in material records, test documentation, or traceability. This is especially relevant when custom specifications and high-performance requirements are part of the commercial commitment.
What companies should examine now
Review how technical requirements are tied to sourcing reality
Analysis shows that companies should closely check whether internal and customer-facing documents clearly connect material selection, performance requirements, and achievable lead times. For products linked to the at least 600 MPa UTS threshold, this is a practical point of control rather than a paperwork exercise.
Watch for changes in quotation, contract, and delivery language
What deserves closer attention is the wording used in quotations, supply agreements, and order confirmations. Immediate wheel price increases and longer lead times can affect price validity periods, delivery promises, and change-notification practices. The current update does not provide formal execution rules, so this should be treated as an area to monitor rather than a settled compliance outcome.
Keep material documents and test records aligned
From an industry perspective, any period of constrained billet supply raises the importance of document consistency. Companies should pay attention to material certificates, test reports, technical data sheets, and customer specification files to ensure that commercial adjustments do not create inconsistencies in compliance evidence or quality traceability.
Prepare for export and after-sales questions linked to delay or substitution
Observably, longer custom lead times can spill into export scheduling, customer communication, and after-sales handling if delivery dates or technical assumptions change. The provided information does not confirm any specific trade restriction or regulatory action, but companies would be prudent to monitor whether customers begin tightening documentation requests or qualification checks in response to the current supply situation.
Why this matters beyond a raw-material price move
Analysis shows that this development is more important as an execution signal than as a standalone commodity headline. The confirmed facts point to a supply-side constraint affecting a performance-sensitive input material, and that combination tends to surface first in procurement discipline, specification control, and delivery negotiations. It is more appropriate to understand this as an active market signal with compliance and contract implications, rather than as proof that a fully defined new rule framework has already been imposed.
How the market should read this stage
At this stage, the update is best understood as a concrete change in operating conditions for forged lightweight wheels, especially in custom and high-strength EV applications. The confirmed facts support closer attention to sourcing, document control, and delivery planning, but they do not by themselves establish a new formal policy regime or a final market outcome. A neutral reading is that businesses should treat the development as actionable in current execution while continuing to verify how customers, suppliers, and market documents respond.
Basis of this article and what still needs verification
This article is based on the user-provided news title, event date, and event summary. For developments of this kind, relevant source categories would usually include official notices, regulatory releases, trade authority information, industry association updates, standards body documents, and reporting from established business media. A specific official source link was not provided in the input, so the underlying publication path still requires further verification. Observably, the next points to watch are any clearer execution language in procurement documents, certification or testing expectations, changes in tender wording, industry feedback on delivery performance, and how companies implement sourcing and contract adjustments in response to the reported billet shortage.