
Industry Portal
Related News
- 00
0000-00
How to Specify Low-Pressure Casting Parts for Leak-Tight Automotive Housings - 00
0000-00
How to Specify an Electric Sunroof for Passenger Cars: Key Design and Safety Factors - 00
0000-00
North American Vehicle Aesthetics: Trends Shaping Exterior Design and Materials - 00
0000-00
ASPICE for Smart Optical Systems: Evidence Needed for Automotive Development - 00
0000-00
How to Select NVH Control Materials for Automotive Panels and Powertrain Systems
Forged Wheel Lead Times Stretch to 18 Weeks
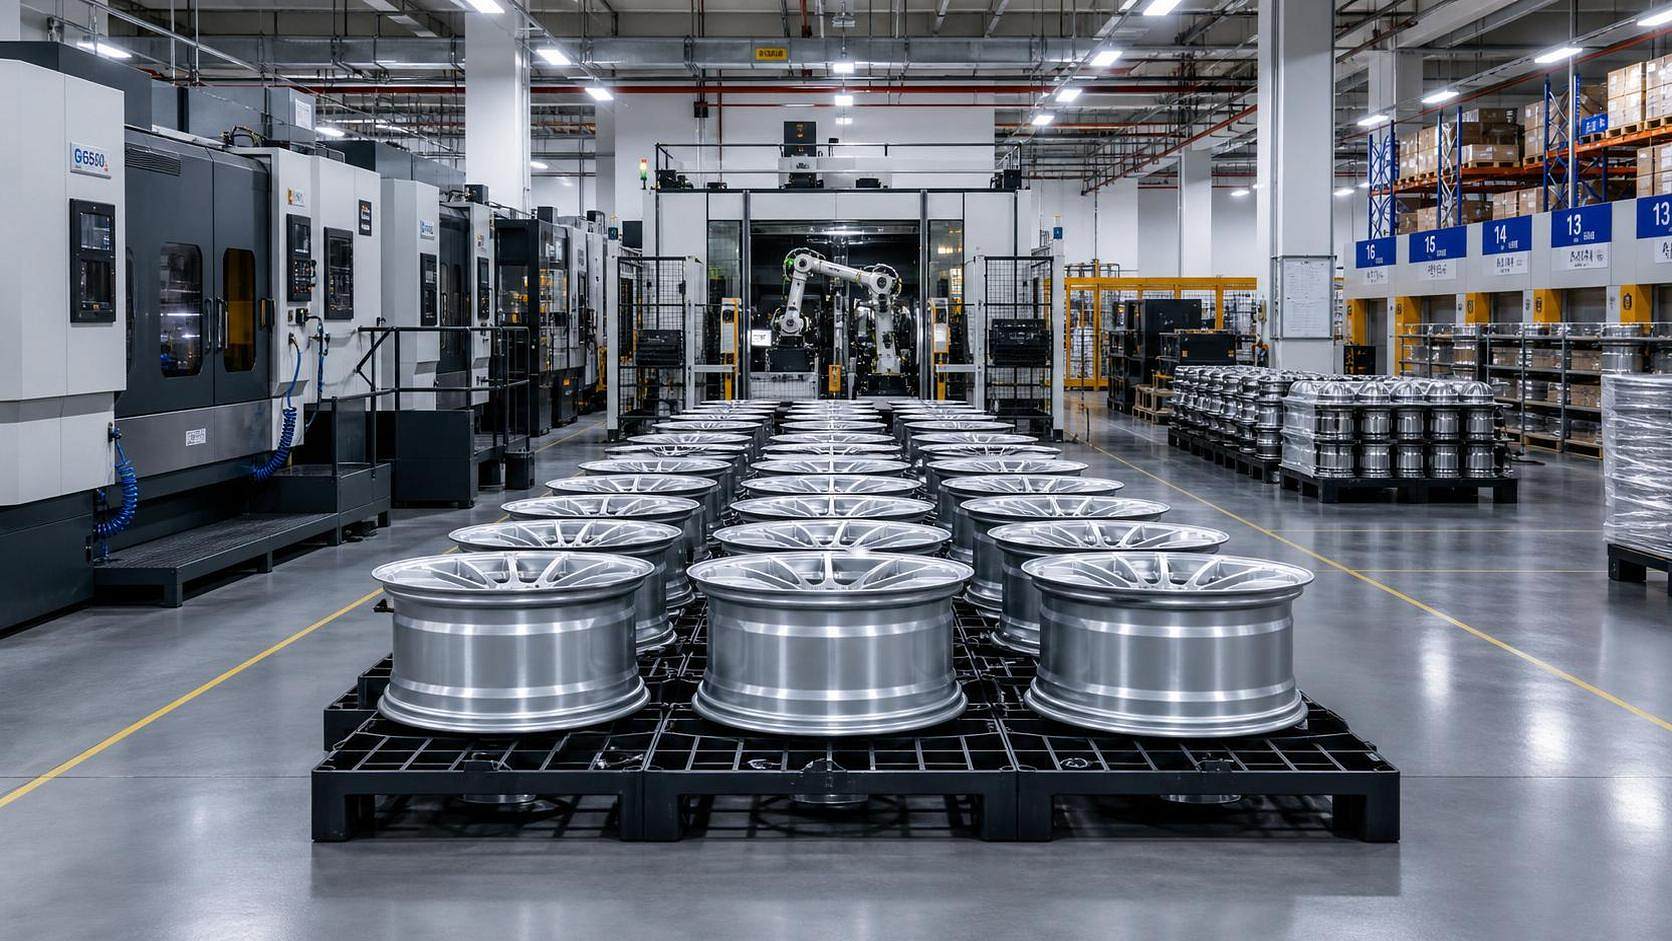
The timing of the underlying production shift was not specified in the source material, but AutosupplyIQ data dated July 11, 2026 indicates that export lead times for standard forged lightweight wheels have broadly extended to 14-18 weeks. The change is being linked to capacity upgrades at leading Chinese forged lightweight wheel manufacturers toward 800MPa+ ultra-high-strength aerospace-grade aluminum alloy lines. This is worth close attention for buyers, wheel brands, manufacturing planners, and supply chain teams because the reported delay is already affecting sourcing behavior and payment arrangements in the European aftermarket.
What Has Been Confirmed So Far
According to the information provided, the average export lead time for standard forged lightweight wheels has increased by 3.2 weeks compared with the June average, reaching a general range of 14-18 weeks. The stated reason is that capacity at leading Chinese forged lightweight wheel producers is being shifted toward upgraded production lines for 800MPa+ ultra-high-strength aerospace-grade aluminum alloy. The same update notes that European modification brands have already activated emergency dual-source procurement plans and raised the prepayment ratio for Q3 orders to 40%.
Where the Pressure May Appear First
Procurement teams are likely to feel the timing impact immediately
From an industry perspective, buyers that depend on standard forged lightweight wheel exports may be affected first because longer lead times directly alter ordering windows, inventory timing, and contract execution. What deserves closer attention is whether current purchase schedules, deposit terms, and delivery commitments still match the new 14-18 week cycle.
Aftermarket brands may face a narrower planning window
Observably, European modification brands are already reacting through emergency dual-source procurement plans. That suggests the pressure is not limited to factory scheduling; it also reaches product availability, seasonal sales planning, and supplier allocation decisions. For brands operating across multiple suppliers, the immediate issue is less about price speculation and more about whether continuity of supply can be maintained under a longer and less flexible delivery cycle.
Supply chain service providers may need to adjust coordination rhythms
Analysis shows that longer export lead times can also affect the work of supply chain coordinators, traders, and delivery management teams. Even without additional verified data on freight or customs, the reported extension alone means that production booking, order confirmation, and customer communication may need to be synchronized earlier than before.
What Companies Should Track Now
Watch for further wording around capacity allocation
What deserves closer attention is whether subsequent statements continue to describe the issue as a temporary capacity adjustment or as a more sustained production reallocation toward higher-specification alloy lines. That distinction matters because it affects how companies interpret the current delay: as a short scheduling disruption or as a structural change in available standard forged wheel capacity.
Recheck order structures for Q3 execution
The reported increase in Q3 prepayment ratios to 40% is a practical signal for commercial teams. Companies involved in sourcing or resale should review whether existing payment terms, approval processes, and customer commitments can absorb higher upfront funding requirements without creating internal bottlenecks.
Prepare for supplier diversification without assuming immediate replacement
Observably, emergency dual-source procurement has already been triggered by some European modification brands. Analysis shows this makes supplier qualification, documentation review, and delivery coordination more important, especially for businesses that previously relied on a concentrated supplier base. At the same time, the source material does not confirm how much substitute capacity is available, so diversification plans should be treated as a response pathway rather than a guaranteed solution.
Strengthen customer-facing delivery communication
For sales and account teams, the practical issue is expectation management. A lead-time extension of 3.2 weeks versus the June average is material enough to affect quotation validity, promised ship dates, and order confirmation language. Clear communication around timelines and payment changes may become as important as the sourcing decision itself.
Why This Looks More Like a Signal Than a Final Outcome
Analysis shows this development is best understood as a meaningful supply chain signal rather than a complete market conclusion. The confirmed facts point to a production-capacity shift and a visible response from European modification brands, but they do not yet establish how long the extended lead-time range will persist or whether the impact will spread uniformly across suppliers and markets. For that reason, the update merits continued monitoring rather than overstatement.
How to Read This Update Rationally
At this stage, it is more appropriate to understand the news as a near-term operational change with possible longer-term implications. The immediate significance lies in extended delivery cycles, dual-source activation, and higher prepayment requirements. The broader significance depends on whether the capacity shift toward 800MPa+ ultra-high-strength aerospace-grade aluminum alloy production remains limited or becomes a lasting allocation trend.
Basis of This Article
This article is based on the user-provided news title, the note that the event timing was not specified, and the supplied summary citing AutosupplyIQ data dated July 11, 2026. For this type of industry update, relevant source categories usually include official announcements, company statements, industry association releases, authoritative media reports, and standards-related documents. No specific official source link was provided in the input, so the underlying details still require ongoing verification. The main points to watch next are whether lead times remain in the 14-18 week range, whether capacity allocation language changes, and whether procurement and prepayment adjustments broaden beyond the currently referenced European modification brands.