
Industry Portal
Related News
- 00
0000-00
ASPICE for Smart Optical Systems: Evidence Needed for Automotive Development - 00
0000-00
How to Select NVH Control Materials for Automotive Panels and Powertrain Systems - 00
0000-00
Choosing Low Rolling Resistance Tires for Longer Mileage and Lower Fleet Fuel Costs - 00
0000-00
Rain Sensing Systems Calibration: Methods for Reliable Detection and Testing - 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects
Chinese Forged Wheel Lead Times Extend to 6-8 Weeks
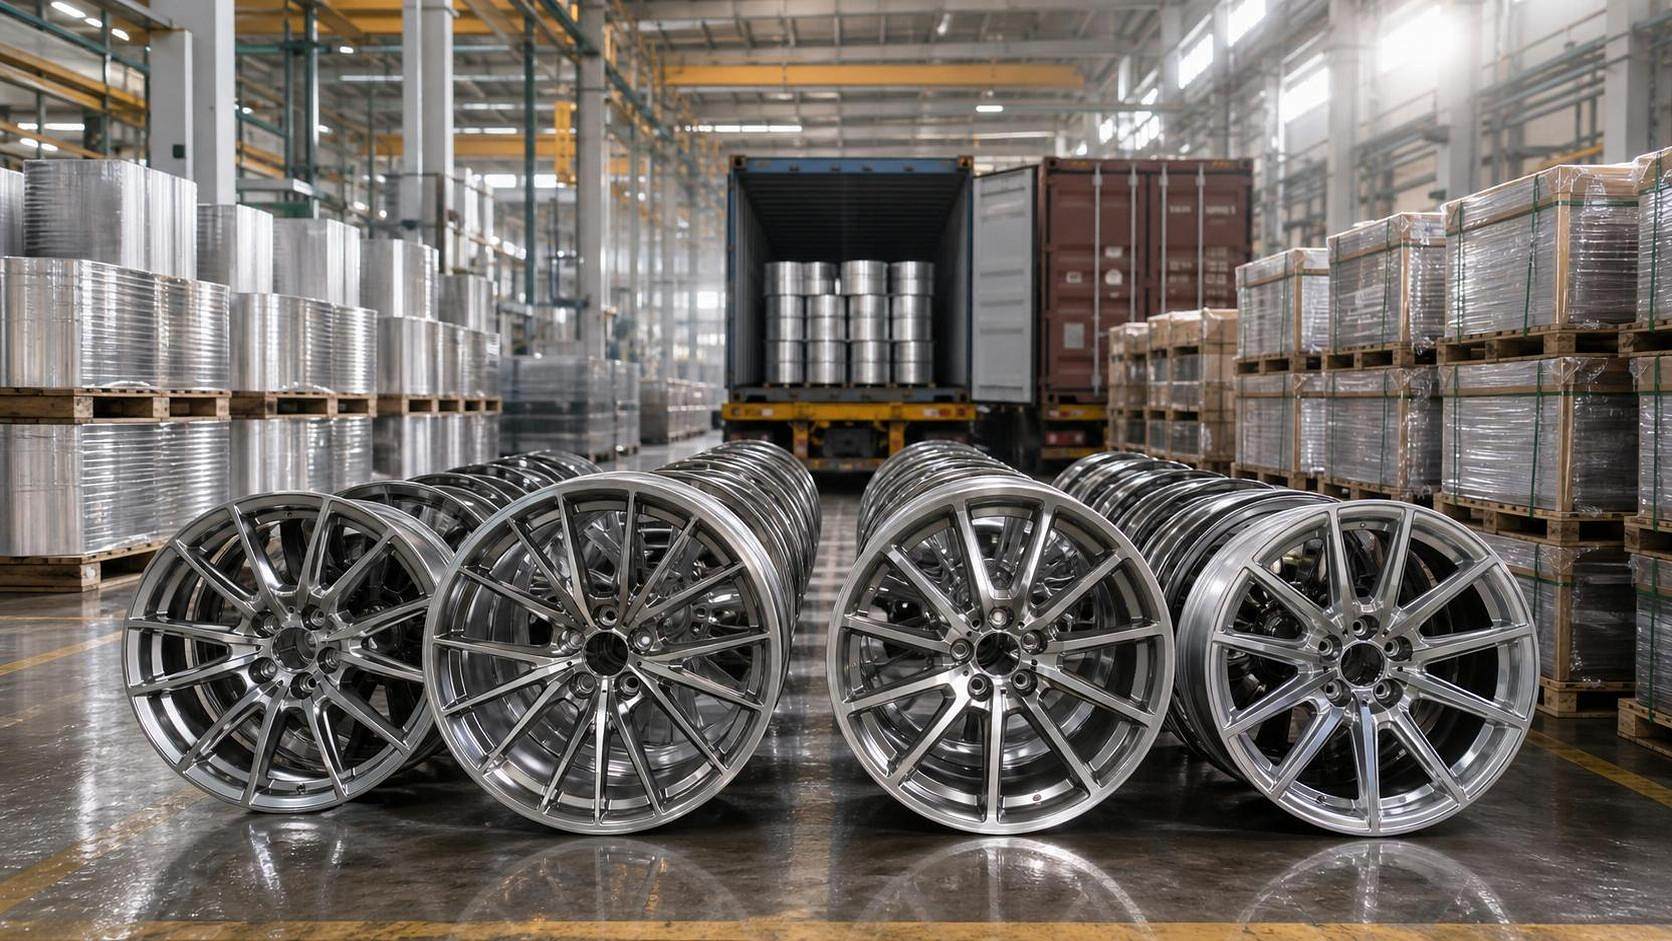
The timing of the event has not been clearly specified in the source input, but as of July 4, multiple Tier 1 Chinese forged wheel manufacturers were reported to be quoting longer lead times of 6-8 weeks for 20-22 inch forged lightweight wheels. The development is drawing attention across wheel sourcing, raw material procurement, export distribution, and delivery planning because it combines two pressures at once: stronger NEV export-driven demand into Europe and Southeast Asia, and rising billet costs tied to tighter domestic aluminum supply conditions.
What Has Been Confirmed So Far
According to the provided information, several Tier 1 Chinese forged wheel manufacturers reported that lead times for 20-22 inch forged lightweight wheels had extended to 6-8 weeks as of July 4.
The reported driver on the demand side was a surge in NEV export orders to Europe and Southeast Asia.
On the raw material side, spot prices for A6061 and A7075 billet rose 12% month on month. The stated reasons were constrained domestic smelting output and the drawdown of inventories directed toward export business.
The same input also indicates that overseas distributors should adjust Q3 procurement schedules and secure allocations earlier.
Where the Pressure May Be Felt Across the Chain
Export distributors may face a narrower ordering window
From an industry perspective, overseas distributors are likely to be among the first to feel the impact because extended wheel lead times directly affect replenishment timing and shipment planning. The main business pressure may appear in Q3 order scheduling, allocation confirmation, and customer delivery commitments. What deserves closer attention is whether current purchase timing still matches prior planning cycles.
Raw material buyers will need to watch cost pass-through risk
Analysis shows that procurement teams linked to forged wheel production may need to pay closer attention to billet pricing, especially for A6061 and A7075. The reported 12% month-on-month increase does not by itself confirm a lasting trend, but it does point to a cost environment that may affect quotation validity, margin management, and timing of raw material purchases.
Manufacturing operations may see tighter coordination needs
For processing and manufacturing businesses, the combination of longer lead times and higher billet prices may create pressure in production scheduling, order prioritization, and supplier coordination. Observably, even without evidence of wider disruption, this kind of supply-demand imbalance can make delivery promises harder to manage if order intake remains concentrated in the same wheel sizes and product category.
Downstream buyers may need earlier communication on delivery expectations
For procurement-side customers and service partners, the immediate issue is not only product availability but also timing certainty. The key exposure may lie in project planning, sales commitments, and cross-border logistics preparation. A lead time extension at the manufacturing end can quickly translate into tighter room for schedule changes further downstream.
What Companies Should Track Right Now
Rework Q3 purchasing calendars
The clearest practical takeaway from the reported situation is that Q3 procurement schedules may need adjustment. Companies buying 20-22 inch forged lightweight wheels should review whether current order timing still provides enough buffer for production and shipment.
Secure allocation before demand peaks further
Based on the provided information, early allocation becomes a concrete commercial issue rather than a routine planning preference. Businesses relying on Chinese forged wheel supply should pay attention to reservation timing, confirmed production slots, and whether suppliers are signaling longer quotation or confirmation cycles.
Separate material inflation from delivery risk in supplier talks
Analysis shows that billet price increases and extended wheel lead times are related but not identical issues. In supplier communication, companies should distinguish between cost changes tied to A6061/A7075 billet and schedule changes tied to order congestion, because each affects contracts and customer communication differently.
Check how export-oriented inventory changes affect fulfillment
What deserves closer attention is the reference to export-oriented inventory drawdown. For firms managing overseas orders, this raises a practical question about whether available stock is being absorbed faster than expected, which can affect fulfillment confidence even before broader capacity conditions become clearer.
How This Signal Should Be Read
Observably, this update should not yet be treated as proof of a broad, long-term structural shortage across the entire forged wheel market, because the confirmed information is limited to multiple Tier 1 Chinese manufacturers, specific wheel sizes, and the conditions reported as of July 4. At the same time, it is more appropriate to understand this as a meaningful short-term market signal: demand linked to NEV exports is strong enough to extend lead times, while raw material pricing is moving in a way that can tighten operating flexibility.
Analysis shows that the importance of this development lies less in any single number than in the combination of lead-time extension and billet cost inflation. That pairing matters because it affects both availability and purchasing economics at the same time.
Why the Update Matters Beyond a Single Order Cycle
For now, this development is best understood as a near-term operating signal with broader watch value rather than a settled long-term conclusion. It points to tighter conditions in the supply of 20-22 inch forged lightweight wheels from Chinese manufacturers serving export demand, and it suggests that procurement, allocation, and delivery planning deserve more attention in the current quarter. The industry significance is real, but the full duration and breadth of the pressure still require continued observation.
Basis of This Article and What Still Needs Verification
This article is based on the user-provided news title, the note that the event timing was not clearly specified, and the supplied event summary. No additional company names, policy details, institutional data, or external figures have been added beyond that input.
For this type of industry update, source categories that are typically relevant include official company statements, manufacturer announcements, industry association releases, authoritative media reporting, and standard-related documentation. However, a specific official source link was not provided in the input, so the details should continue to be verified against future primary-source disclosures.
Further observation should focus on whether the reported 6-8 week lead times persist, whether billet pricing for A6061 and A7075 remains elevated, and whether export-driven demand into Europe and Southeast Asia continues to shape allocation and delivery conditions.