
Industry Portal
Related News
- 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects - 00
0000-00
Automatic Wipers for Buses: 7 Selection Criteria for Fleet Procurement - 00
0000-00
How Smart Optical Perception Prevents Collisions in Low-Light Driving Conditions - 00
0000-00
Private Label Tire Export: Evaluating Suppliers, Compliance, and Landed Cost - 00
0000-00
DOT-Compliant Truck Lighting: A Practical Guide to FMVSS 108 Requirements
China Wheel Forging Lead Times Stretch to 18 Weeks
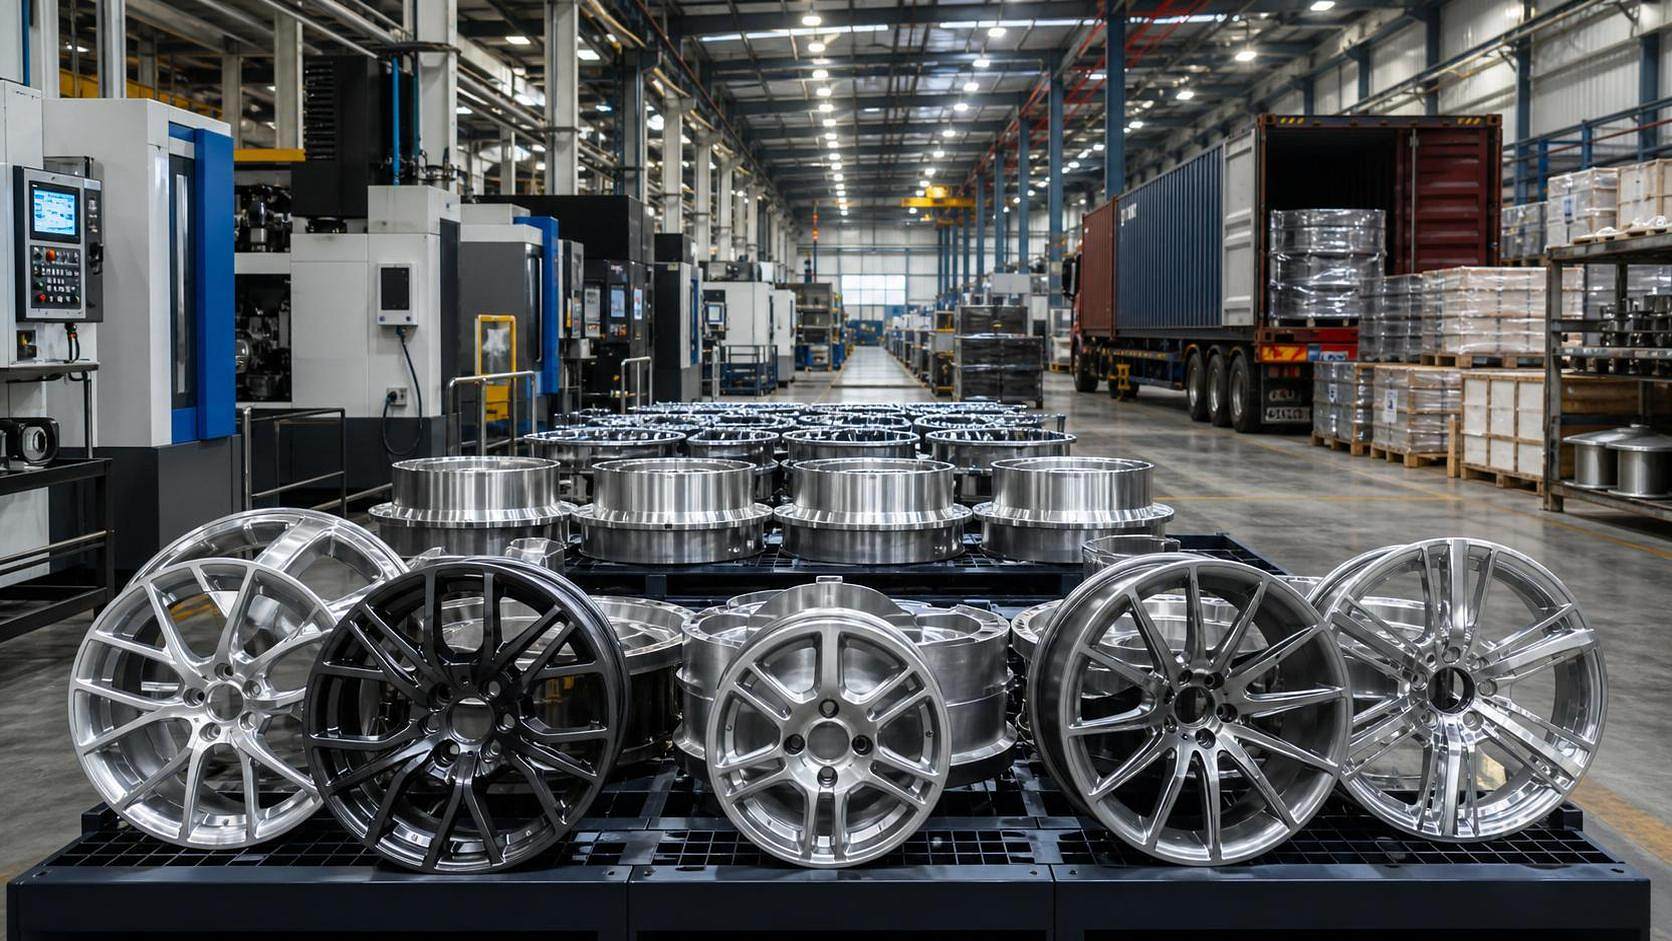
On June 28, 2026, the market signal around export-grade Forged Lightweight Wheels shifted from a production issue to a supply-rule and delivery-risk issue. Following Q2 2026 power curtailments in Guangdong and Shandong, two key precision forging hubs, China’s export lead time for these wheels moved from about 8 weeks to 14-18 weeks. For OEM programs, premium aftermarket distribution, export scheduling, and supplier qualification, this matters because delivery timing is now more closely tied to access to certified low-carbon forging capacity rather than routine ordering cycles.
What Has Been Confirmed So Far
The confirmed facts are narrow but commercially important. After Q2 2026 power curtailments in Guangdong and Shandong, lead times for export-grade Forged Lightweight Wheels from China increased from 8 weeks to 14-18 weeks. Major OEMs and premium aftermarket distributors have reported allocation delays. The development is already affecting global EV platform launches, including Stellantis EV3 and BYD Seagull II exports. The event summary also indicates that early Q3 2026 order placement with certified low-carbon forging facilities has become more important under current conditions.
Where the Pressure Is Likely to Appear First
OEM launch and sourcing windows
From an industry perspective, OEMs are likely to feel the impact through program timing, sourcing coordination, and supplier allocation. When export-grade forged wheel lead times nearly double, purchasing teams and launch planners need to pay closer attention to order timing, confirmed production slots, and whether nominated suppliers can still meet export delivery commitments under constrained capacity.
Premium aftermarket distribution channels
Premium aftermarket distributors may face pressure in allocation, replenishment, and customer delivery promises. What deserves closer attention is that allocation delays can shift the commercial risk from simple inventory management to contract execution, shipment scheduling, and customer expectation management, especially where product positioning depends on forged lightweight specifications rather than interchangeable standard wheel supply.
Export delivery and supply-chain coordination
Export-oriented trading companies and supply-chain service providers are likely to be affected at the handoff points between purchase order confirmation, production scheduling, shipment planning, and final delivery commitments. In practical terms, businesses should watch for changes in lead-time language, production reservation terms, and supporting supplier documents tied to certified low-carbon forging capacity.
Certification-sensitive procurement decisions
The reference to certified low-carbon forging facilities suggests that procurement is not only about finding available capacity, but also about whether that capacity matches the buyer’s certification and supplier qualification requirements. For buyers and compliance-facing teams, the immediate issue is not a new published rule in itself, but the operational effect of certification-linked capacity becoming tighter under current production constraints.
What Companies Should Review Now
Recheck supplier qualification against actual capacity
Analysis shows that supplier approval lists may not be enough if approved facilities cannot provide timely export production slots. Companies should verify whether existing qualified suppliers still have usable capacity within required delivery windows, especially where forged wheel supply is tied to launch milestones or export commitments.
Bring lead-time assumptions back into contract review
Observably, older planning assumptions built around an 8-week cycle may no longer be reliable. Procurement, sales, and logistics teams should review how lead times are described in quotations, purchase orders, shipment commitments, and customer-facing schedules, so commercial documents reflect current delivery conditions rather than outdated planning norms.
Check certification and supporting documentation early
Because the event summary highlights certified low-carbon forging facilities, companies should pay closer attention to the timing and completeness of supplier certification materials, technical documents, and any qualification records used in sourcing or bidding. This is especially relevant where buyer approval depends on documented production attributes rather than price and availability alone.
Track whether allocation delays begin to affect after-sales planning
Where forged lightweight wheels are linked to premium product positioning or export vehicle programs, delayed allocation can also affect replacement planning, service commitments, and traceability expectations. At this stage, it would be premature to treat this as a confirmed after-sales disruption, but it is a practical area for continued monitoring.
How This Signal Should Be Read
Analysis shows that this development is better understood as an execution signal than as a standalone market headline. The immediate change is not merely that production is slower; it is that power-related constraints in key forging regions are now affecting export delivery discipline, allocation order, and the value of certified low-carbon production access. It is also more appropriate to understand this as a live operational shift rather than a settled long-term rule change, because the available information confirms tighter lead times and allocation delays, but does not yet define a broader formal policy framework beyond the curtailment context described.
What the Event Means at This Stage
At this stage, the event points to a more restrictive supply environment for export-grade Forged Lightweight Wheels from China, with consequences for procurement timing, supplier selection, and delivery planning across OEM and premium aftermarket channels. A measured reading is that the change has already landed in execution terms, while its longer-range implications for sourcing rules, certification practice, and customer delivery commitments still require close observation rather than firm conclusions.
Basis of This Article
This article is based on the user-provided news title, event date, and event summary. For developments of this type, commonly relevant source categories may include official notices, regulatory releases, customs or trade authority information, industry association updates, standards-related documents, and reporting by established industry media. No specific official source link was provided in the input, so the precise official documentation still needs to be verified on an ongoing basis. What remains worth tracking includes any further policy detail, certification interpretation, tender document changes, market feedback, and how companies are implementing delivery and sourcing adjustments in practice.