
Industry Portal
Related News
- 00
0000-00
Choosing Low Rolling Resistance Tires for Longer Mileage and Lower Fleet Fuel Costs - 00
0000-00
Rain Sensing Systems Calibration: Methods for Reliable Detection and Testing - 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects - 00
0000-00
Automatic Wipers for Buses: 7 Selection Criteria for Fleet Procurement - 00
0000-00
How Smart Optical Perception Prevents Collisions in Low-Light Driving Conditions
Aluminum Surge Extends Forged Wheel Export Lead Times
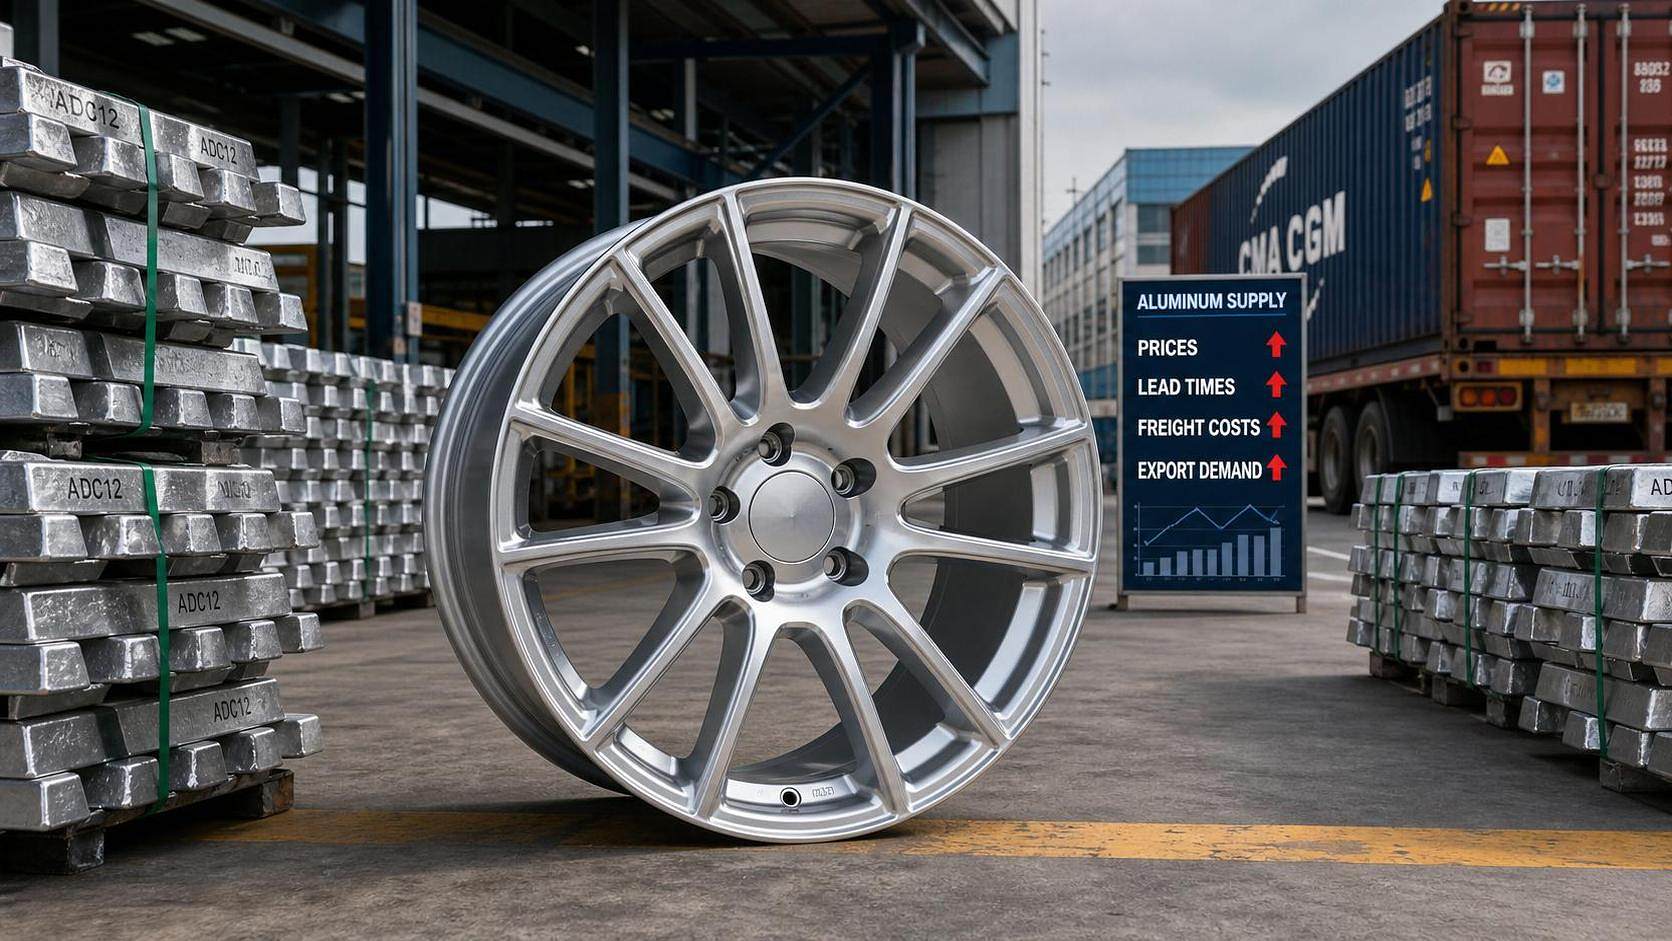
On July 8, 2026, the forged lightweight wheel market drew attention not only because aluminum prices rose sharply, but because that move coincided with a rule-related change in the trading environment: CBAM Phase II implementation in the EU was cited alongside curtailed Chinese smelter output as a driver behind the July price jump. For exporters, buyers, and supply-chain teams, the immediate issue is no longer limited to raw material cost. Longer export lead times, now reported at 14–18 weeks, and the shift in allocation toward EV OEM contracts point to a practical change in how supply, order priority, and delivery commitments may now be managed.
What the market has confirmed so far
The confirmed event date is July 8, 2026. According to the provided information, LME aluminum prices increased 22% month on month to $2,840 per ton in July 2026. The stated drivers were curtailed Chinese smelter output and the implementation of EU CBAM Phase II.
The same information shows that major exporters of forged lightweight wheels are reporting longer delivery cycles. Average export lead times have extended to 14–18 weeks. It also states that supply allocation is moving toward EV OEM contracts, while aftermarket orders are receiving lower priority.
Where the pressure is likely to appear across business flows
Export order management is becoming more sensitive to allocation rules
From an industry perspective, forged wheel exporters may be affected first at the order acceptance and delivery-commitment stage. When lead times extend to 14–18 weeks and priority shifts toward EV OEM contracts, exporters handling aftermarket business may need to pay closer attention to contract timing, shipment commitments, and customer communication. What deserves closer attention is whether existing quotations, delivery promises, and scheduling assumptions still match current supply conditions.
Procurement teams face a tighter link between compliance-driven cost changes and supply timing
For raw material and component procurement functions, the reported connection between aluminum prices and CBAM Phase II implementation matters because it suggests that regulatory developments are interacting with physical supply conditions. Analysis shows that procurement teams may need to monitor not only price exposure but also whether upstream sourcing, replenishment timing, and supplier confirmations remain reliable under a more constrained environment. In practice, this can affect purchase scheduling, material reservation, and internal approval timing for export orders.
Aftermarket channels may see greater delivery uncertainty than OEM-linked programs
Distributors, trading companies, and aftermarket buyers are likely to feel the impact through fulfillment predictability rather than through price alone. The confirmed shift in priority toward EV OEM contracts indicates that aftermarket orders could face longer waits or weaker scheduling certainty. Observably, this makes delivery planning, inventory positioning, and customer service commitments more exposed to supply allocation decisions made upstream.
Supply-chain service providers may need closer document and milestone coordination
For logistics coordinators and other supply-chain service providers, the main issue is not a newly confirmed transport rule in the provided information, but a change in execution rhythm. Longer production and export lead times can increase the importance of milestone tracking, booking coordination, and document readiness. Companies involved in shipment support should therefore watch for revised dispatch windows, changed handover timing, and possible knock-on effects in export documentation flow.
What companies should watch in the near term
Review whether delivery terms still reflect current supply conditions
Analysis shows that firms engaged in forged wheel export or sourcing should recheck whether lead-time clauses, order confirmation language, and delivery expectations still align with the reported 14–18 week range. This is particularly relevant for businesses serving aftermarket demand, where allocation priority appears weaker than for EV OEM-linked contracts.
Track how CBAM-related pressure is translating into commercial execution
The provided information does not give detailed enforcement mechanics, but it does connect CBAM Phase II implementation with current aluminum price movement. It is more appropriate to understand this as a signal to watch for downstream effects in quotations, sourcing decisions, and customer requirements rather than as proof of a fully defined execution outcome in every transaction.
Strengthen supplier confirmation and order sequencing
From an operating perspective, companies should pay closer attention to supplier commitment windows, order sequencing, and production-slot visibility. Where business depends on specific export timing, closer verification of supplier capacity and scheduling status may become more important than relying on historical lead-time assumptions.
Prepare for tighter after-sales and traceability expectations if delays continue
Observably, longer lead times can create pressure beyond the factory gate. Exporters and channel partners may need to organize order status records, technical documentation, and customer communication more carefully so that delayed delivery does not turn into a broader dispute over fulfillment or product traceability. The provided information does not confirm new quality or certification rules, but it does justify closer attention to execution records around delayed orders.
Why this reads as an execution signal, not just a price headline
Analysis shows that this development is more meaningful than a standalone metals price movement. The combination of a regulatory factor cited in the market narrative, a sharp aluminum price increase, and an observable extension in forged wheel export lead times suggests that rule-related cost pressure is already intersecting with day-to-day allocation decisions. At the same time, it would be premature to treat this as a fully settled long-term pattern. What deserves closer attention is whether similar signals begin appearing in customer specifications, procurement documents, supplier terms, and order-priority practices across related export business.
How this development is best understood for now
At this stage, the event is best understood as a live execution signal affecting supply availability and delivery planning in forged lightweight wheel exports, rather than as a complete and final rule outcome. The confirmed facts point to a market where regulatory change, raw material pricing, and contract prioritization are interacting more directly. For industry participants, the practical significance lies in lead-time discipline, sourcing visibility, and order-priority awareness rather than in broad conclusions about long-term market direction.
Basis of this article and points that still require verification
This article is based on the user-provided news title, event date, and event summary. For developments of this kind, source categories typically relevant to later verification may include official announcements, regulatory releases, customs or trade authority information, industry association updates, standards-related documents, and reporting from authoritative business media.
No specific official source link was provided in the input, so the underlying official references still need to be verified on an ongoing basis. Follow-up attention should remain on later policy detail, certification or compliance interpretation, changes in procurement and tender documents, market feedback, and how exporting companies ultimately implement scheduling and allocation decisions in practice.