
Industry Portal
Related News
- 00
0000-00
How to Specify Low-Pressure Casting Parts for Leak-Tight Automotive Housings - 00
0000-00
How to Specify an Electric Sunroof for Passenger Cars: Key Design and Safety Factors - 00
0000-00
North American Vehicle Aesthetics: Trends Shaping Exterior Design and Materials - 00
0000-00
ASPICE for Smart Optical Systems: Evidence Needed for Automotive Development - 00
0000-00
How to Select NVH Control Materials for Automotive Panels and Powertrain Systems
Tags
Aluminum Spike Extends Lead Times for Forged Wheels
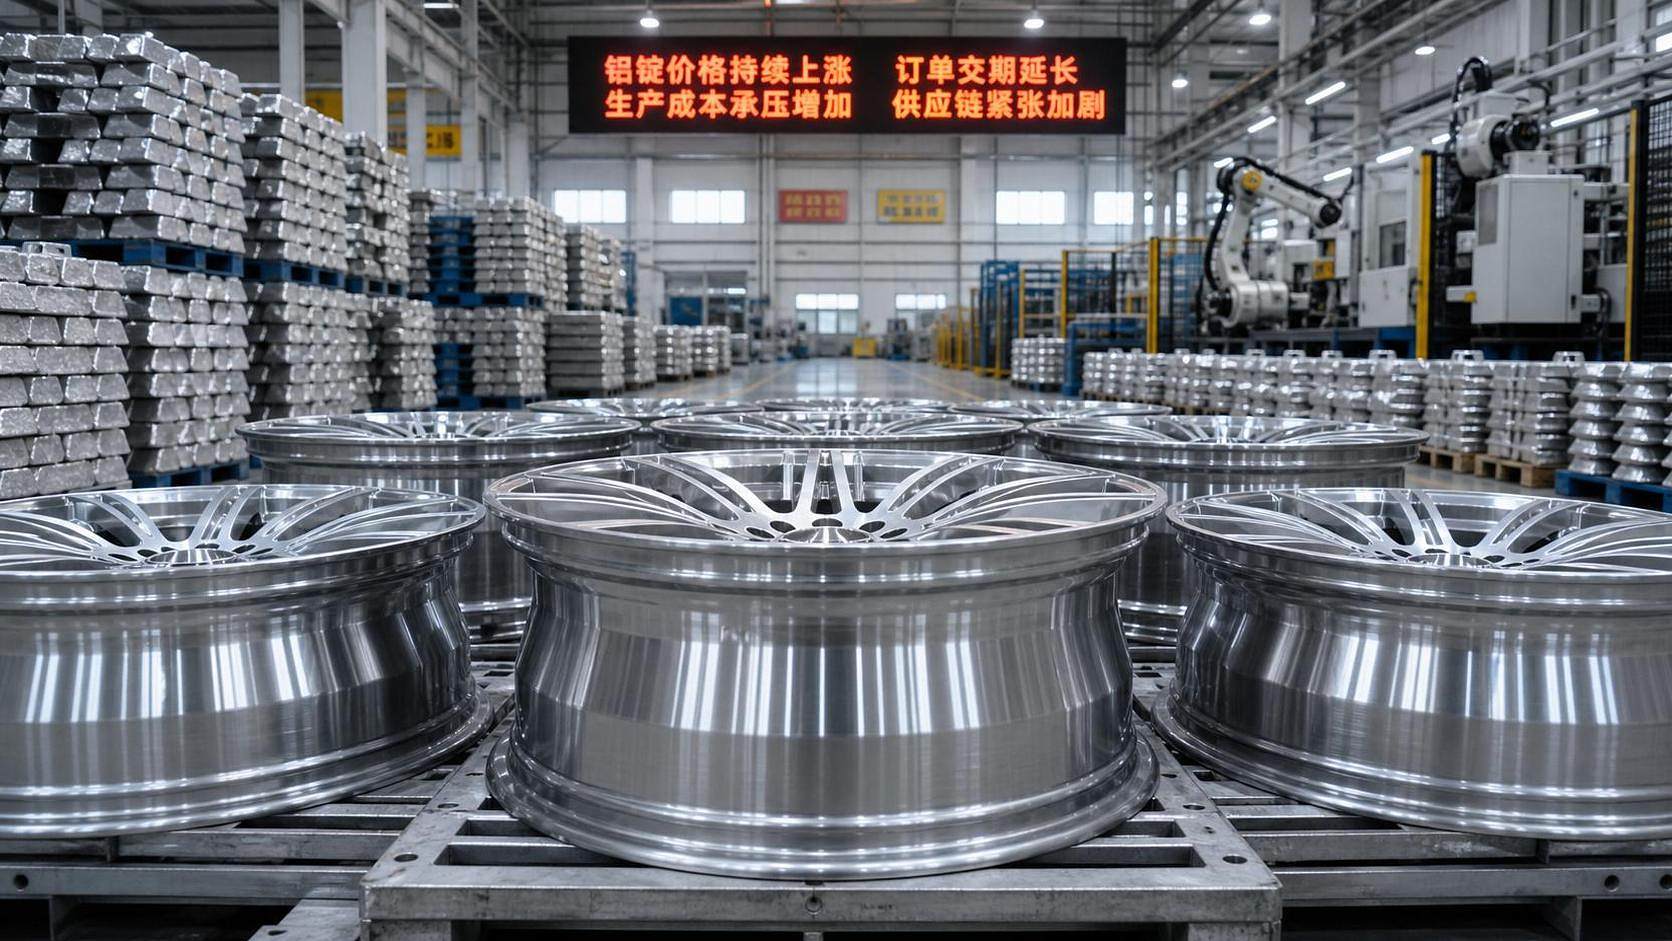
On June 17, 2026, a sharp weekly rise in aluminum prices coincided with a new compliance signal from the EU’s CBAM third-phase pre-declaration process, creating immediate pressure on export pricing and delivery schedules for Forged Lightweight Wheels. For manufacturers, exporters, overseas buyers, and supply-chain teams, the issue is no longer only raw-material volatility; it is also whether procurement, quotation, and shipment arrangements can still align with changing trade and reporting expectations.
What has changed in the market and compliance backdrop
Confirmed information shows that the LME spot aluminum price reached $2,842 per ton on June 17, up 6.3% week on week and the highest level since October 2025. The stated drivers were tighter alumina supply linked to political instability in Guinea and the start of the EU CBAM third-phase pre-declaration process.
At the same time, leading domestic forged wheel manufacturers informed overseas customers that delivery times for standard Forged Lightweight Wheels orders had been extended from eight weeks to 12–16 weeks. Some customized specifications were also put on hold for new orders.
Where the pressure is likely to appear first
Export quotations are becoming harder to hold steady
From an industry perspective, exporters of Forged Lightweight Wheels are likely to feel the first impact in pricing validity, contract timing, and customer communication. When aluminum prices move quickly while a new CBAM reporting phase begins, the practical issue is not only cost absorption but also whether quoted terms, supporting documents, and shipment schedules remain workable through the order cycle.
Procurement teams face tighter coordination between cost and lead time
For raw-material buyers and production planners, the confirmed extension from eight weeks to 12–16 weeks suggests that procurement and scheduling assumptions used earlier may no longer hold. What deserves closer attention is whether material sourcing, production slots, and order confirmation processes need to be reviewed more frequently while supply conditions and trade-related reporting expectations are shifting at the same time.
Overseas buyers and channel partners may need earlier order decisions
Importers, distributors, and downstream buyers are likely to face pressure in project timing, replenishment planning, and specification selection. The pause on some customized orders indicates that non-standard configurations may become harder to secure in the short term, which can affect purchase timing, technical alignment, and delivery commitments already under discussion.
Supply-chain service providers may see more documentation and scheduling checks
For logistics, trade operations, and related service providers, the combination of cost volatility and CBAM phase advancement increases the need to track shipping windows, commercial documents, and communication records more closely. Analysis shows that even without confirmed new enforcement outcomes in the input, the reporting-related signal itself can already affect how cross-border orders are prepared and reviewed.
What companies should review now
Recheck quotation terms and delivery commitments
Observably, companies involved in wheel exports should review whether current quotations, validity periods, and promised lead times still match supplier notices and actual production capacity. Where standard products have already moved to 12–16 weeks, sales and operations teams should avoid treating earlier eight-week assumptions as routine.
Track CBAM-related reporting language in customer requests
Because the input specifically links the market move with the start of the EU CBAM third-phase pre-declaration process, exporters and buyers should pay close attention to whether customers begin requesting additional emissions-related, origin-related, or product-related support materials. The available information does not confirm a specific document list, so this is better treated as a near-term compliance watchpoint rather than a settled filing outcome.
Review customized-order exposure
Companies selling non-standard Forged Lightweight Wheels should examine which pending or planned orders depend on customized specifications. Since some customized configurations have reportedly stopped taking new orders, contract sequencing, specification confirmation, and technical document preparation may need to be adjusted before further commitments are made.
Keep after-sales and traceability records aligned with shipment changes
Where delivery windows are extending, firms should also check whether order records, product traceability files, and customer communication logs remain consistent across revised schedules. Analysis shows that this is particularly relevant for export business where delayed delivery can affect not only production timing but also later quality, warranty, or claim discussions.
Why this looks like an execution signal, not just a price story
Analysis shows that this development is more significant than a simple commodity rebound. The confirmed facts combine three elements at once: a visible aluminum price jump, a stated supply-side constraint in alumina, and the launch of a new CBAM pre-declaration stage. It is more appropriate to understand this as an execution signal affecting trade behavior and delivery planning, even though the full downstream compliance response still requires further observation.
What deserves closer attention is whether customers, suppliers, and service providers begin to change their documentation requests, lead-time buffers, and order-approval procedures in response to this combination of market and regulatory pressure. At this stage, the input supports caution and monitoring, not a definitive conclusion about long-term supply or demand outcomes.
How the market should read the latest shift
The immediate industry meaning of this event is that forged wheel exports are facing a dual test of cost and execution. Confirmed lead-time extensions and pauses in some customized orders indicate that the change is already affecting commercial operations, while the CBAM-related development adds a compliance layer that companies cannot ignore in cross-border business.
From an industry perspective, this is better understood as a real operational adjustment already showing up in quotations and delivery, alongside a regulatory signal whose detailed market impact still needs continued verification through customer requirements, execution practice, and further industry feedback.
Basis of this article and points that still require verification
This article is based on the user-provided news title, event date, and event summary. For developments of this type, relevant source categories usually include official announcements, regulator releases, customs or trade-authority information, industry association updates, standards-body documents, and reporting from established media. No specific official source link was provided in the input, so the underlying policy and execution details still need ongoing verification.
Items that remain worth monitoring include any further clarification of CBAM-related reporting expectations, changes in customer documentation requests, adjustments in tender or technical file requirements, additional feedback from the forged wheel supply chain, and how companies implement revised lead-time and order-acceptance practices in actual export operations.