
Industry Portal
Related News
- 00
0000-00
ASPICE for Smart Optical Systems: Evidence Needed for Automotive Development - 00
0000-00
How to Select NVH Control Materials for Automotive Panels and Powertrain Systems - 00
0000-00
Choosing Low Rolling Resistance Tires for Longer Mileage and Lower Fleet Fuel Costs - 00
0000-00
Rain Sensing Systems Calibration: Methods for Reliable Detection and Testing - 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects
Tags
Aluminum Spike Extends Forged Wheel Lead Times
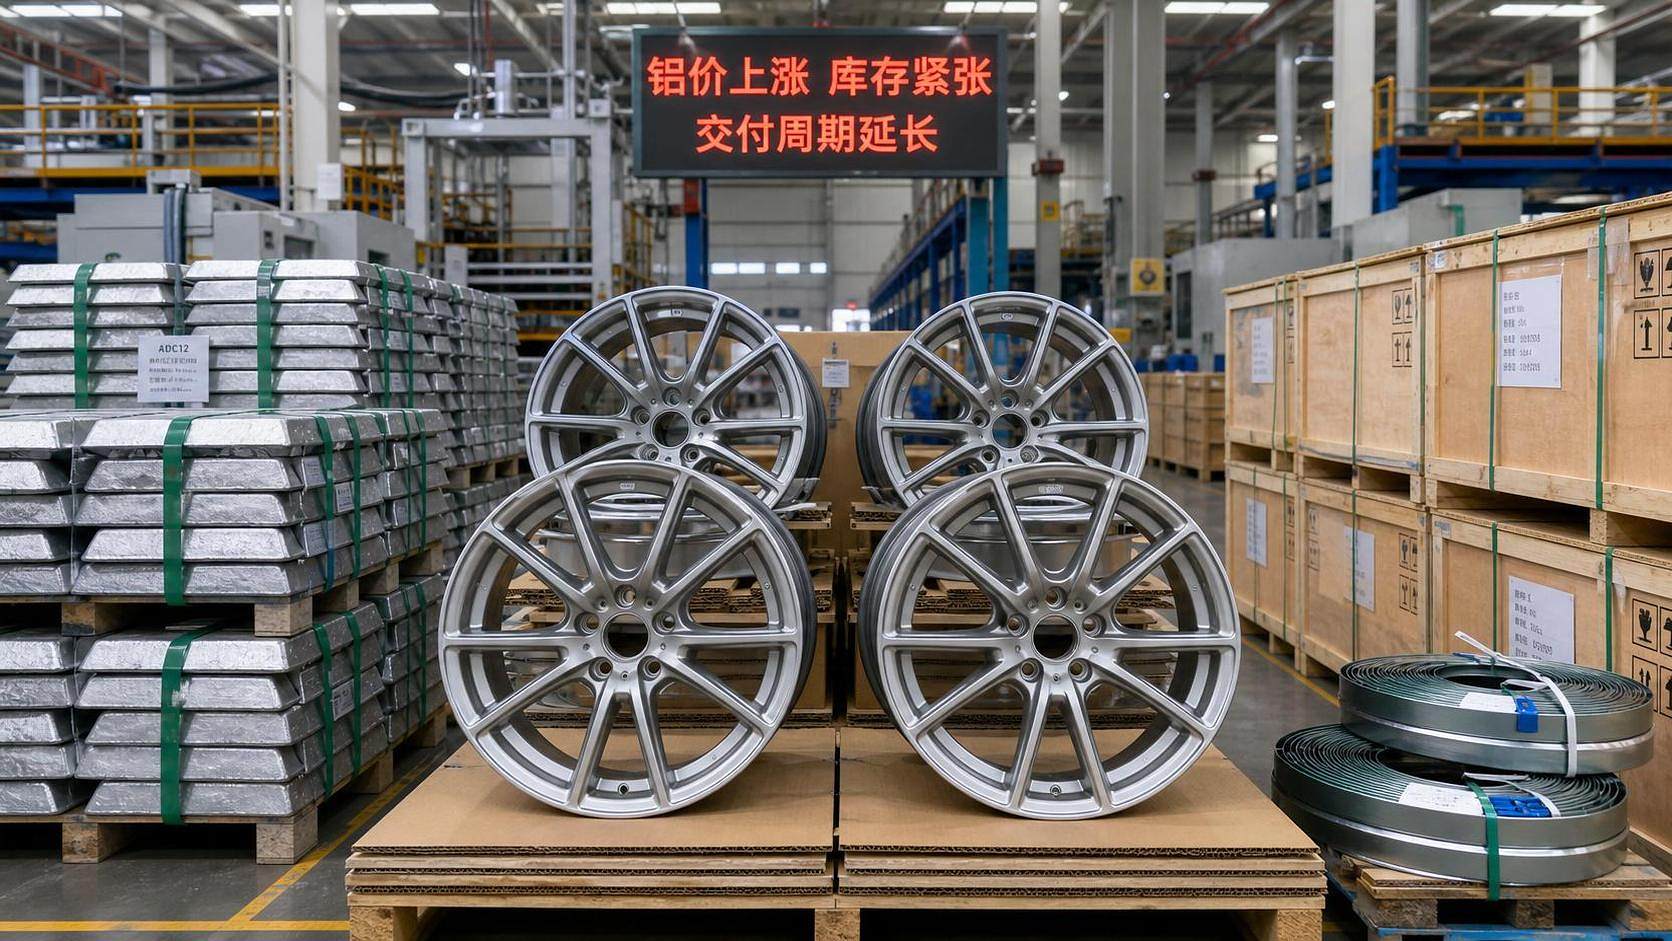
The timing of the underlying event is not specified in the provided information, but the latest price move and supplier notices point to a rules-and-supply signal that matters beyond commodity trading. A sharp weekly rise in aluminum prices, linked to export restrictions on bauxite and seasonal smelter maintenance, is now showing up in longer delivery cycles and higher quotations for forged lightweight Aero/Low-drag Wheels. For buyers, exporters, manufacturers, and supply-chain teams, the issue is no longer only raw material volatility; it also affects procurement timing, contract execution, delivery commitments, and compliance documentation tied to product specifications and order changes.
What the market has already confirmed
LME aluminum futures closed at USD 2,842 per tonne on June 20, up 6.3% from June 13 and marking the highest level since October 2025. The summary attributes the move to two stated factors: restrictions on bauxite exports from Indonesia and a summer maintenance cycle at European primary aluminum plants.
At the downstream level, major domestic producers of forged lightweight wheels have already informed overseas customers that delivery times for Aero/Low-drag Wheels have generally been extended from eight weeks to 12–16 weeks. For some high-end customized products, quoted prices have also increased by 4.5% to 7.2%.
Where the pressure moves along the chain
Procurement terms are becoming more sensitive
From an industry perspective, raw-material buyers and sourcing teams are likely to feel the impact first because aluminum price changes now coincide with a visible extension of wheel lead times. The main business pressure is likely to appear in purchase scheduling, price-validity periods, and the need to recheck whether earlier sourcing assumptions still match current delivery windows.
What deserves closer attention is the practical handling of contract documents, quotation validity, specification confirmation, and any order amendments triggered by longer lead times or revised pricing. Where technical files or bid documents specify fixed delivery expectations, companies may need to review whether those commitments still align with current supplier notices.
Manufacturing and export execution face tighter coordination
Analysis shows that processors, exporters, and order-management teams may be affected not only by cost movement but also by execution risk. If forged lightweight wheel orders shift from an eight-week cycle to 12–16 weeks, production planning, shipment booking, and customer delivery promises may all require adjustment.
For export-facing businesses, the immediate concern is less about a newly published compliance rule and more about the operational effect of a trade-related restriction upstream. That can influence how companies manage order confirmations, delivery clauses, change notices, and supporting records used to explain revised timelines or pricing to overseas buyers.
After-sales and quality traceability may need clearer paperwork
Observably, when customized products are repriced and delayed, after-sales teams and quality-traceability functions may also need stronger documentation discipline. If customers accept revised lead times or product variants, companies should pay close attention to whether technical specifications, approval records, and shipment-related documents remain consistent across the full order file.
This matters especially where product performance claims, fitment requirements, or customer-specific specifications form part of the transaction. Any mismatch between confirmed specifications and actual delivery arrangements can become a commercial or compliance issue later, even if the initial trigger was a raw-material and supply constraint.
What companies should watch next
Recheck specification-linked commitments
Analysis shows that companies handling Aero/Low-drag Wheels should closely review whether quoted delivery schedules, product configurations, and customer-approved specifications still match current supplier capacity. If technical commitments were built around an earlier eight-week cycle, any extension should be reflected consistently in order records and customer communication.
Track quotation changes with supporting records
What deserves closer attention is the documentation behind repricing. Where some high-end customized products have already seen quote increases of 4.5% to 7.2%, businesses should ensure that internal approval records, commercial correspondence, and revised order terms are aligned, especially if customers later question the basis for the adjustment.
Watch for shifts in execution language and market practice
It is more appropriate to understand this as an execution signal rather than a fully settled new rule set. Companies should therefore monitor how suppliers, buyers, and channel partners describe delivery changes, cost pass-through, and acceptance conditions in actual transactions. Any repeated change in wording across notices, tenders, or procurement files may indicate a broader shift in market practice.
Keep compliance files ready for delayed deliveries
Observably, longer lead times can affect more than production calendars. Firms should pay attention to whether inspection records, technical documents, shipment papers, and customer confirmations remain current if delivery dates move materially. This is not evidence of a new certification regime, but it does raise the importance of file consistency and traceability during contract execution.
How this signal should be read for now
Analysis shows that this development is best read as a live market-and-trade execution signal. The confirmed facts show a direct connection between upstream supply constraints and downstream delivery extensions, which is often where commercial risk becomes more visible to buyers than the original commodity move itself.
At the same time, it would be premature to treat the situation as a completed or uniform industry-wide rules reset. The more cautious interpretation is that companies are seeing the early operational effects of trade-related restrictions and production interruptions, while the full market response still needs to be observed through supplier behavior, customer acceptance, and ongoing delivery performance.
A practical reading of the latest shift
From an industry perspective, the key takeaway is not only that aluminum has become more expensive within a short period, but that procurement and delivery assumptions for forged lightweight wheels are already changing in practice. That makes this update relevant to sourcing, export execution, document control, and customer communication at the same time.
It is more appropriate to understand the development as a confirmed short-term execution change with broader implications still under observation. Businesses do not yet have enough verified information here to draw wider conclusions, but they do have enough to reassess lead-time risk, pricing discipline, and order-file consistency now.
Basis of this article
This article is generated from the user-provided news title, event timing, and event summary. The specific timing of the underlying event is not stated in the input, and no official source link is provided in the input, so further verification remains necessary.
For developments of this kind, relevant source types typically include official announcements, regulator releases, customs or trade authority information, industry association updates, standards organization documents, and reporting by authoritative media. Further observation is still needed on any detailed policy interpretation, certification practice, tender document changes, market feedback, and how companies ultimately implement revised delivery and pricing arrangements.