
Industry Portal
Related News
- 00
0000-00
Choosing Low Rolling Resistance Tires for Longer Mileage and Lower Fleet Fuel Costs - 00
0000-00
Rain Sensing Systems Calibration: Methods for Reliable Detection and Testing - 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects - 00
0000-00
Automatic Wipers for Buses: 7 Selection Criteria for Fleet Procurement - 00
0000-00
How Smart Optical Perception Prevents Collisions in Low-Light Driving Conditions
Aluminum Billet Shortage Extends Forged Wheel Lead Times
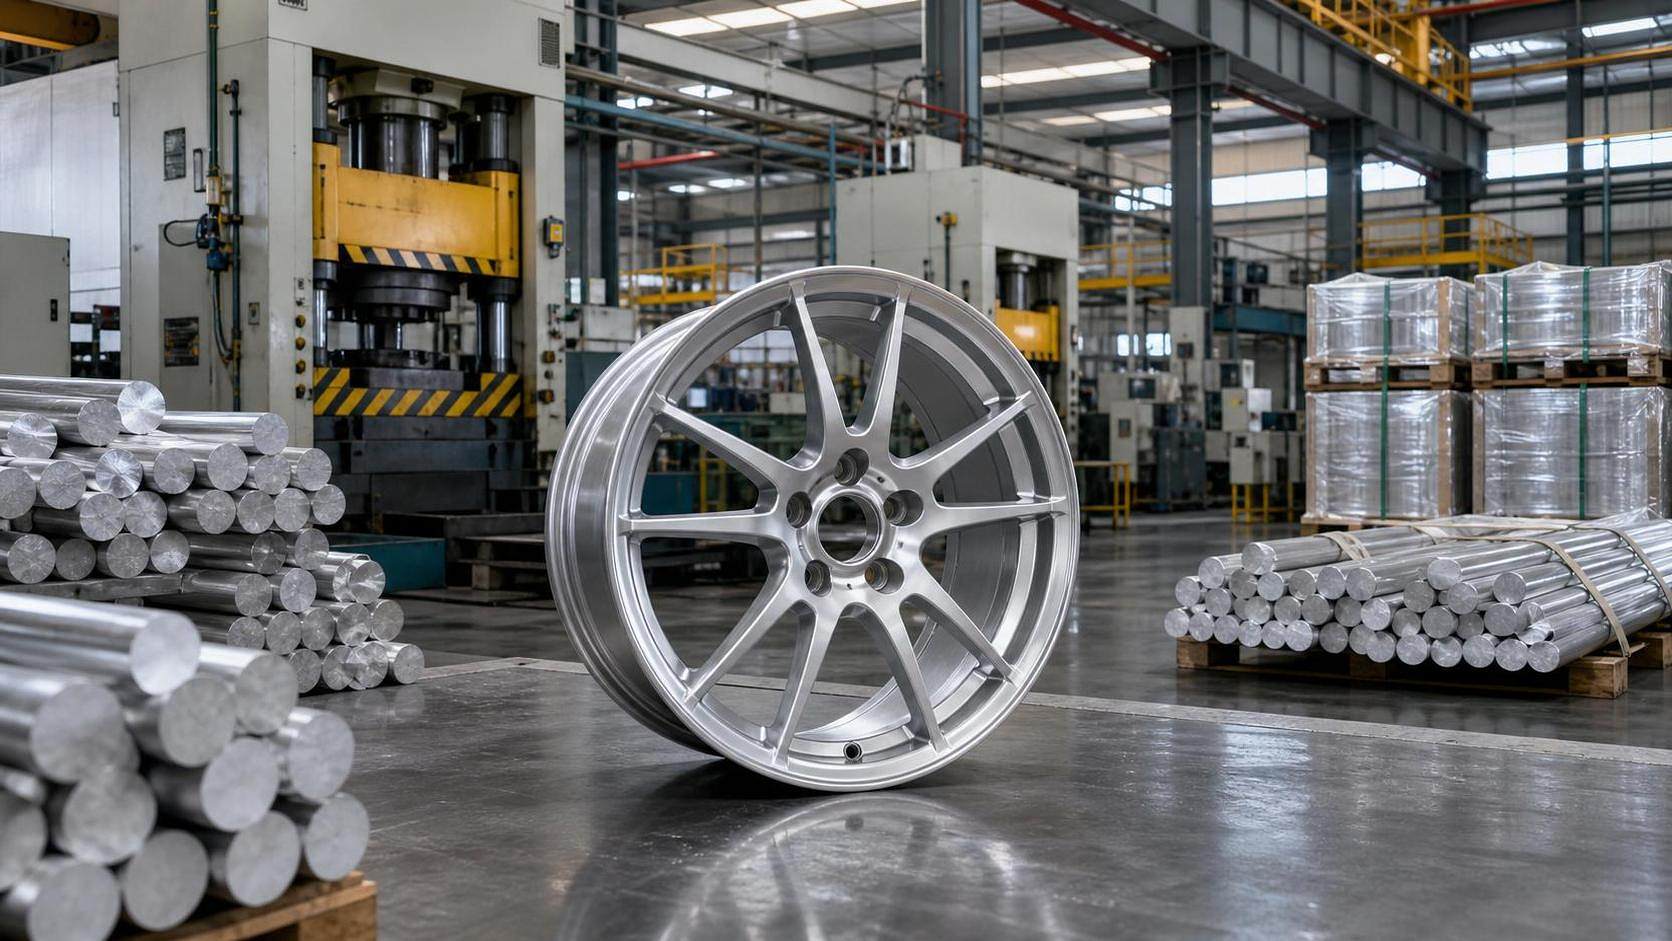
The timing of this development was not specified in the source input, but the market signal is clear: supply constraints in aluminum billet are extending average lead times for forged lightweight wheels from around eight weeks to roughly 14-18 weeks. The issue deserves attention from wheel manufacturers, OEM-linked supply chains, aftermarket distributors, and procurement teams because it points to pressure not only on raw material availability, but also on allocation priorities and delivery planning.
What Has Been Confirmed So Far
Based on the provided information, global aluminum billet supply has tightened due to two stated factors: curtailed Chinese smelting output and CBAM-related surcharges in the EU. As a result, average lead times for forged lightweight wheels have increased from eight weeks to 14-18 weeks.
The same information also indicates that major OEMs in Germany and South Korea are being prioritized in allocation decisions. This is narrowing the order window available to aftermarket distributors.
Where the Pressure Is Likely to Be Felt First
Manufacturing schedules are becoming less predictable
From an industry perspective, forged lightweight wheel producers are likely to feel the impact first through material planning and production scheduling. When billet supply tightens and lead times stretch, manufacturers may face more difficulty aligning raw material arrivals with committed production slots.
Aftermarket channels face reduced ordering flexibility
Aftermarket distributors appear to be in a more constrained position because the provided information shows that major OEMs are receiving priority allocations. Analysis shows this can affect ordering windows, replenishment timing, and the ability to secure product availability in line with customer demand.
Procurement teams may need to revise delivery expectations
For buyers sourcing forged lightweight wheels, the main impact is likely to show up in purchasing lead times and delivery coordination. What deserves closer attention is whether previously standard ordering assumptions based on an eight-week cycle remain workable under current supply conditions.
Supply-chain service providers may see more timing-related friction
Observably, logistics and supply-chain coordination functions may also be affected, not necessarily because of a confirmed transport disruption, but because longer production lead times usually place more pressure on scheduling, communication, and order sequencing across the chain.
What Companies Should Watch Now
Separate allocation signals from broad market assumptions
Companies should pay close attention to how allocation priority is being applied in practice. The confirmed information points specifically to major OEMs in Germany and South Korea receiving preference, so businesses serving other channels should avoid assuming equal access to supply.
Recheck lead-time commitments in active orders
Where forged lightweight wheels are already in procurement or production planning, current delivery commitments may need review against the reported 14-18 week range. This is especially relevant for firms managing customer promises, inventory timing, or downstream installation schedules.
Focus on communication with suppliers and customers
Analysis shows that the current issue is not only about physical supply, but also about expectation management. Suppliers, distributors, and procurement teams should watch for changes in order windows, allocation responses, and delivery confirmations, and reflect those changes early in customer-facing communication.
Track policy-linked cost and supply signals carefully
Because the provided information links the situation partly to EU CBAM surcharges, companies should distinguish between a policy-related cost signal and actual material access at the transaction level. What deserves closer attention is whether further rule interpretation or implementation changes alter commercial behavior beyond the current lead-time extension.
How This Development Should Be Read
Analysis shows this is more than an isolated delivery delay, because the pressure is tied to both upstream supply constraints and allocation behavior among major buyers. At the same time, the available facts are still limited. It is more appropriate to understand this as a meaningful industry signal rather than a fully defined long-term shift.
Observably, the combination of reduced smelting output, CBAM-related cost pressure, and OEM prioritization suggests a market in which access matters as much as price. However, without a clearly stated event date or additional confirmed follow-up data, the situation still requires continued observation rather than definitive conclusions.
A Short-Term Disruption or a Longer Signal?
At this stage, the most balanced reading is that the forged lightweight wheel market is facing a tangible near-term supply and lead-time constraint, with possible wider implications if allocation tightness persists. For industry participants, the immediate significance lies in planning discipline, supplier communication, and realistic delivery assumptions.
It is more appropriate to understand this update as a developing industry dynamic that already affects order timing, while still requiring further verification before being treated as a settled long-term structural outcome.
Basis of This Article and What Still Needs Verification
This article is based on the user-provided news title, the note that the event timing was not specified, and the supplied event summary. No specific official source link was included in the input, so the exact underlying documentation still needs ongoing verification.
For this type of industry development, source types commonly worth checking include official notices, company statements, industry association updates, authoritative media reporting, and related policy or standards documentation. Further observation should focus on whether billet supply conditions, CBAM-related commercial effects, and allocation priorities continue to affect forged lightweight wheel lead times.