
Industry Portal
Related News
- 00
0000-00
ASPICE for Smart Optical Systems: Evidence Needed for Automotive Development - 00
0000-00
How to Select NVH Control Materials for Automotive Panels and Powertrain Systems - 00
0000-00
Choosing Low Rolling Resistance Tires for Longer Mileage and Lower Fleet Fuel Costs - 00
0000-00
Rain Sensing Systems Calibration: Methods for Reliable Detection and Testing - 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects
China's Shipbuilding New Orders Up 195% in Q1, Boosting Aero Wheel Aluminum Exports
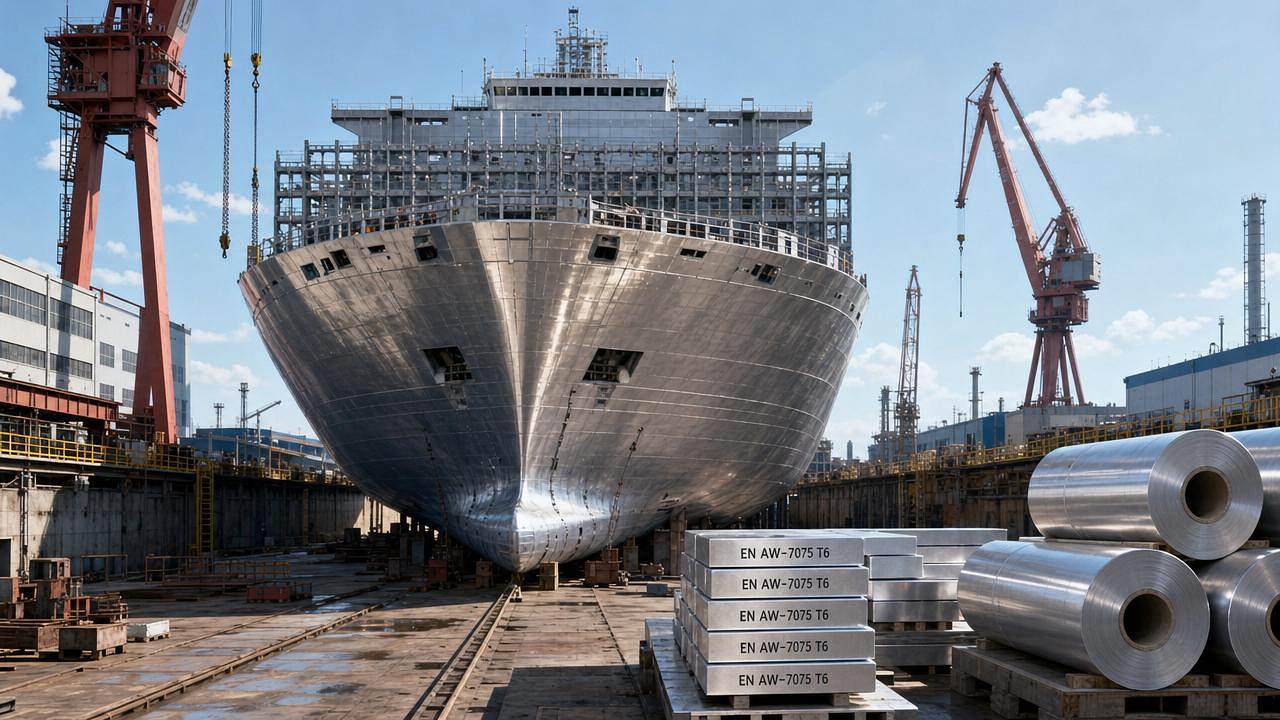
On May 12, 2026, data released by the China Association of the National Shipbuilding Industry showed that China’s new shipbuilding orders in Q1 2026 reached 59.53 million deadweight tons — a 195.2% year-on-year increase. This surge is driving heightened demand for lightweight marine aluminum alloys, particularly 7xxx-series high-strength, high-toughness aluminum used in Aero and low-drag wheel manufacturing, with export volumes rising 41% quarter-on-quarter — primarily to wheel hub processors in Turkey, Mexico, and Southeast Asia. Companies involved in aluminum alloy trade, wheel component manufacturing, and maritime supply chain logistics should monitor downstream demand shifts, regional procurement patterns, and material specification alignment closely.
Event Overview
On May 12, 2026, the China Association of the National Shipbuilding Industry published official statistics indicating that China’s new shipbuilding orders for Q1 2026 totaled 59.53 million deadweight tons, representing a 195.2% increase compared to the same period in 2025. The data further noted that this growth has stimulated increased demand for lightweight shipboard aluminum alloys, resulting in a 41% quarter-on-quarter rise in exports of 7xxx-series aluminum alloys designated for Aero and low-drag wheel production. Primary destination markets cited were Turkey, Mexico, and Southeast Asia — specifically for use at wheel hub processing facilities.
Industries Affected
Direct Exporters of 7xxx-Series Aluminum Alloys
These enterprises are directly exposed to the observed 41% quarter-on-quarter export volume increase. The impact manifests in higher order frequency, tighter delivery windows, and intensified scrutiny on material certifications (e.g., aerospace-grade strength/toughness compliance, surface finish tolerances) required by downstream wheel manufacturers.
Aluminum Ingot and Alloy Producers (Upstream Raw Material Suppliers)
Producers supplying billets or master alloys for 7xxx-series extrusion and forging face upward pressure on output planning and inventory turnover. The surge reflects not just volume growth but also a shift toward higher-specification batches — notably those meeting EN AW-7075 or AMS 4027 equivalents — which may require adjusted melt practice and quality control protocols.
Wheel Hub Fabricators (Downstream Processors)
Facilities in Turkey, Mexico, and Southeast Asia receiving these aluminum shipments are experiencing accelerated throughput demands. Their exposure lies in raw material availability consistency, lead time variability, and potential bottlenecks in heat treatment or CNC machining capacity — especially where alloy-specific aging schedules (e.g., T6/T73 tempering) are critical to final wheel performance.
Maritime Component Logistics & Certification Service Providers
Third-party inspection agencies, freight forwarders specializing in aluminum coil/billet handling, and documentation specialists supporting export compliance (e.g., origin certification, REACH/ROHS declarations) are seeing increased transaction volume and complexity — particularly around traceability requirements for aerospace-adjacent applications.
What Relevant Enterprises or Practitioners Should Monitor and Act On
Track Official Updates on Shipbuilding Order Composition and Delivery Timelines
The 195.2% YoY growth reflects aggregate tonnage — not vessel type or delivery schedule. Enterprises should monitor upcoming quarterly breakdowns (e.g., LNG carrier vs. container vessel share, average contract lead time) to assess whether demand for lightweight aluminum is concentrated in near-term deliveries or spans multi-year build programs.
Monitor Destination-Market-Specific Technical Requirements and Import Regulations
Turkey, Mexico, and Southeast Asian hub processors operate under differing regulatory frameworks for automotive/marine component imports. Exporters should verify whether recent customs notifications — e.g., Turkish Ministry of Trade’s updated alloy classification codes or ASEAN harmonized system (HS) updates for semi-finished aluminum — affect documentation or duty treatment.
Validate Alignment Between Exported Alloy Grades and Downstream Wheel Manufacturing Specifications
Not all 7xxx-series aluminum meets Aero/low-drag wheel requirements. Enterprises should confirm whether current export batches align with common industry benchmarks such as tensile strength ≥570 MPa, elongation ≥8%, and fatigue resistance per SAE J2982. Discrepancies may trigger rework or rejection at destination.
Prepare for Potential Supply Chain Adjustments in Billet Sourcing and Heat Treatment Capacity
A sustained export uptick may strain domestic billet availability and third-party tempering services. Firms should proactively engage billet suppliers on allocation visibility and assess backup options for T6/T73 aging — including in-region partnerships — to avoid production delays.
Editorial Perspective / Industry Observation
Observably, this data point functions less as an isolated market event and more as a leading indicator of structural demand acceleration at the intersection of maritime decarbonization and vehicle lightweighting. The 195.2% new order growth reflects both global fleet renewal cycles and tightening IMO emissions timelines — both of which incentivize aluminum-intensive hull and propulsion system designs. From an industry perspective, the 41% export lift in 7xxx-series aluminum is better understood as a secondary ripple effect: shipbuilders’ material choices are reshaping procurement priorities several tiers upstream — from alloy producers to wheel fabricators. Analysis shows this is still an early-stage signal; it has not yet translated into broad-based price adjustments or long-term contract renegotiations across the aluminum value chain. Continued monitoring is warranted — particularly for divergence between reported order volume and actual steel/aluminum cutting commencement rates, which remain lagging indicators of real demand absorption.
This development underscores how macro-level industrial trends — such as surging shipbuilding activity — can rapidly propagate technical and logistical implications across seemingly adjacent sectors. It is not yet evidence of a sustained structural shift in aluminum trade flows, but rather a timely reminder that material specifications, regional certification pathways, and supply chain responsiveness matter more than headline growth percentages alone. Current conditions are best interpreted as a demand inflection point requiring tactical operational awareness — not strategic realignment.
Source Attribution
Main source: China Association of the National Shipbuilding Industry (data release dated May 12, 2026).
Areas requiring ongoing observation: Quarterly breakdown of vessel types within new orders; confirmed billet-to-wheel conversion rates in destination markets; and any forthcoming updates to national import standards affecting 7xxx-series aluminum in Turkey, Mexico, or ASEAN member states.