
Industry Portal
Related News
- 00
0000-00
ASPICE for Smart Optical Systems: Evidence Needed for Automotive Development - 00
0000-00
How to Select NVH Control Materials for Automotive Panels and Powertrain Systems - 00
0000-00
Choosing Low Rolling Resistance Tires for Longer Mileage and Lower Fleet Fuel Costs - 00
0000-00
Rain Sensing Systems Calibration: Methods for Reliable Detection and Testing - 00
0000-00
How to Evaluate a Photoelectric Sensing Supplier for Industrial Automation Projects
Tags
China's Shipbuilding New Orders Up 195% in Q1 2026
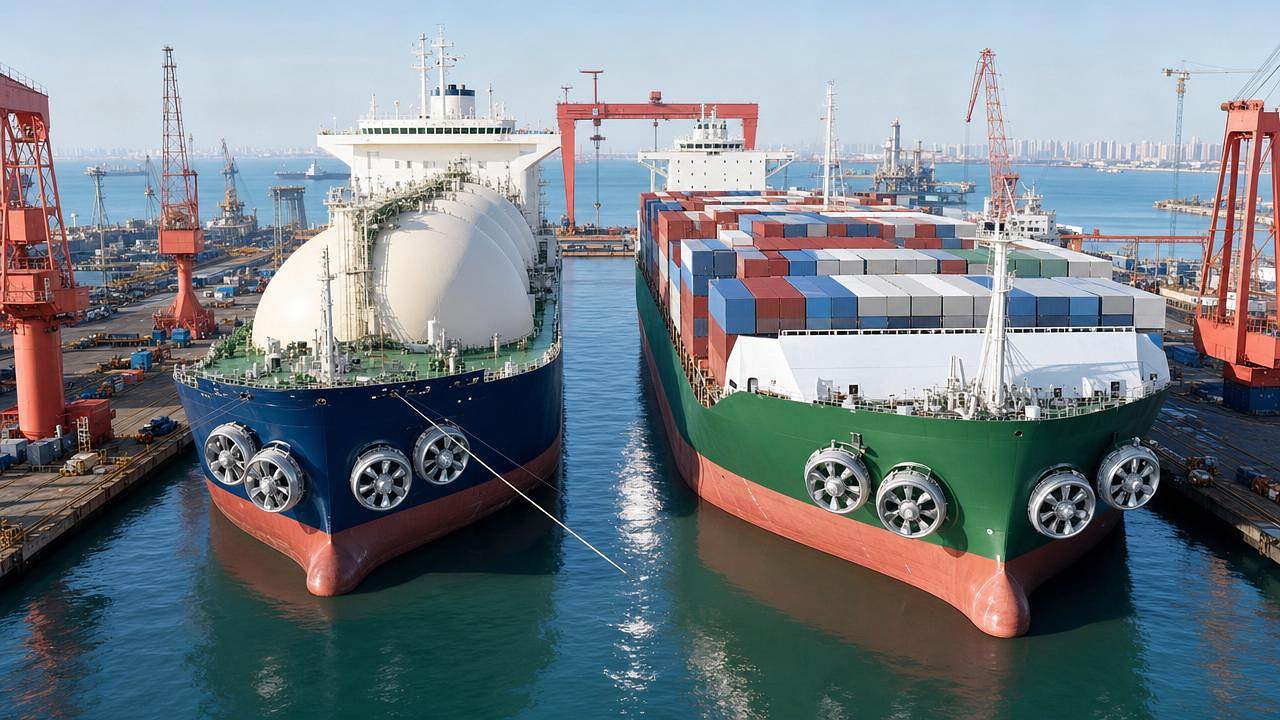
On May 14, 2026, the China Association of the National Shipbuilding Industry reported that new shipbuilding orders in China surged 195% year-on-year in Q1 2026 — a record high. This development is driving notable export growth for specialized aluminum alloys used in Aero/Low-drag Wheels, particularly impacting aluminum material suppliers, wheel manufacturers, and marine equipment exporters. The surge signals tangible shifts in global marine supply chain dynamics — especially for firms engaged in high-value marine component manufacturing and advanced alloy trade.
Event Overview
According to the China Association of the National Shipbuilding Industry’s official notification issued on May 14, 2026, China’s new shipbuilding orders in Q1 2026 increased by 195% compared to the same period in 2025. High-value vessel types accounted for over 65% of total new orders. Accompanying this trend, exports of specialized aluminum alloys for Aero/Low-drag Wheels — including modified 6061-T651 grade — rose significantly. Primary destinations include South Korea, Norway, and Singapore, where shipowners have designated Chinese wheel manufacturers as approved suppliers. Delivery lead times for these materials have extended to 14 weeks.
Impact on Specific Subsectors
Direct Exporters of Aluminum Alloys
These firms face rising demand for certified, high-strength, low-drag aluminum grades. Impact manifests in tighter production capacity utilization, longer order-to-delivery cycles, and heightened scrutiny on material certification (e.g., EN 755/EN 573 compliance, mill test reports). Export documentation timelines and customs clearance readiness are now critical path items.
Aluminum Ingot and Billet Procurement Entities
Upstream raw material buyers must contend with tighter availability of 6061-series billets meeting T651-modified mechanical property specifications. Impact includes upward pressure on spot pricing, reduced flexibility in alloy composition adjustments, and greater dependency on pre-qualified domestic smelters capable of consistent thermal-mechanical processing.
Wheel Forging and Machining Manufacturers
Firms producing Aero/Low-drag Wheels for marine applications experience cascading scheduling effects: extended material lead times directly constrain production planning windows. Impact includes revised master production schedules, increased buffer stock requirements for semi-finished forgings, and more frequent technical alignment with shipowners’ classification societies (e.g., DNV, LR, ABS) regarding material traceability and surface finish validation.
Marine Supply Chain Logistics & Certification Service Providers
Third-party inspection agencies, freight forwarders handling temperature- and humidity-sensitive aluminum shipments, and classification society liaison services see higher request volumes for pre-shipment verification, dimensional audits, and non-destructive testing coordination. Impact centers on resource allocation — particularly for time-bound certifications required by Norwegian or Singaporean flag state authorities.
Key Considerations for Relevant Enterprises and Practitioners
Monitor Official Updates on Export Classification and Licensing
While current data reflects commercial momentum, no public indication exists yet of changes to export control categories (e.g., under China’s Dual-Use Items List) for these aluminum alloys. Enterprises should track announcements from the Ministry of Commerce and General Administration of Customs for any reclassification affecting licensing or documentation requirements.
Track Lead-Time Trends by Destination Market and Alloy Grade
Delivery delays are currently reported at 14 weeks — but this figure may vary by end-customer specification (e.g., enhanced fatigue resistance vs. standard aerodynamic profile). Firms should segment order data by destination country, shipowner group, and alloy sub-grade to identify emerging bottlenecks before they escalate into contractual exposure.
Distinguish Between Order Volume Signals and Actual Revenue Recognition Timing
The 195% order growth reflects contract signings, not revenue realization. Given typical ship construction timelines (24–36 months), associated aluminum deliveries occur in phases aligned with hull block assembly milestones. Finance and sales teams should avoid conflating booking velocity with near-term cash flow impact.
Prepare for Increased Technical Documentation Demands
Shipowners and classification societies increasingly require full material pedigree packages: heat number traceability, tensile/yield strength test records per lot, and surface roughness measurement reports. Preparing standardized templates and digital archiving protocols now reduces approval cycle time for future tenders.
Editorial Perspective / Industry Observation
Observably, this Q1 data point functions less as an isolated statistic and more as a structural signal: it confirms accelerated global outsourcing of high-specification marine wheel manufacturing to China-based facilities — contingent on reliable access to qualified aluminum feedstock. Analysis shows the 195% growth is concentrated in LNG carriers, ammonia-ready vessels, and large container ships — all requiring drag-optimized propulsion systems. From an industry perspective, the extended 14-week delivery window suggests supply constraints are already operational, not merely forecasted. Current developments are better understood as early-stage supply chain recalibration — not yet a mature market equilibrium.
Concluding, this update reflects tightening integration between China’s shipbuilding output and its upstream specialty aluminum ecosystem. It does not indicate broad-based aluminum demand expansion across industrial sectors, nor does it imply immediate policy shifts. Rather, it highlights a targeted, high-value niche where material performance, certification rigor, and logistical coordination converge. Stakeholders are advised to treat this as a demand inflection point within a narrow technical corridor — one requiring precision response, not generalized scaling.
Source: China Association of the National Shipbuilding Industry — official notification issued May 14, 2026.
Notable pending observation: Whether subsequent quarterly reports sustain the 195% YoY growth rate, or whether Q2 data reveals normalization or further acceleration, remains to be verified.